• Recommended Sites & Links
  • About

Dare Something Worthy Today Too!

~ FreeCryptoBitCoins, Cryptocurrency, BitCoin, Ethereum, BitCoin Cash, Ethereum Classic, LiteCoin, DogeCoin, Gold & Precious Metals, Investing & Investments, Stocks and Stock Markets, Financial Markets & Market Timing, Technical Analysis, Oil and Energy Markets, Hard Assets Investing, BlockChain, Airdrops, Earn Free Bitcoin…

Dare Something Worthy Today Too!

Category Archives: Today

Is the Glitter Fading?

25 Wednesday Feb 2009

Posted by jschulmansr in Austrian school, Bailout News, banking crisis, banks, bear market, bull market, capitalism, China, Comex, commodities, Contrarian, Copper, Currencies, currency, Currency and Currencies, deflation, depression, DGP, dollar denominated, dollar denominated investments, Doug Casey, economic, Economic Recovery, economic trends, economy, Fed Fund Rate, Federal Deficit, federal reserve, Finance, financial, Forex, futures, futures markets, GDX, GLD, gold, Gold Bubble, Gold Bullion, Gold Investments, gold miners, Gold Price Manipulation, hard assets, How To Invest, How To Make Money, hyper-inflation, IAU, India, inflation, Investing, investments, Jschulmansr, Junior Gold Miners, Latest News, majors, Make Money Investing, Market Bubble, market crash, Markets, mid-tier, mining companies, mining stocks, monetization, oil, palladium, physical gold, platinum, platinum miners, precious, precious metals, price, price manipulation, prices, producers, production, run on banks, safety, silver, silver miners, Silver Price Manipulation, spot, spot price, stagflation, Stimulus, Stocks, TARP, Technical Analysis, The Fed, Tier 1, Tier 2, Tier 3, Today, U.S., u.s. constitution, U.S. Dollar, volatility, warrants, XAU

≈ 1 Comment

Tags

ANV, Austrian school, AUY, Bailout News, banking crisis, banks, bear market, Bollinger Bands Saudi Arabia, Brian Tang, bull market, CDE, central banks, China, Comex, commodities, Copper, Currencies, currency, deflation, Dennis Gartman, depression, DGP, dollar denominated, dollar denominated investments, Doug Casey, economic, economic trends, economy, EGO, Federal Deficit, financial, Forex, FRG, futures, futures markets, gata, GDX, GG, GLD, gold, gold miners, hard assets, HL, hyper-inflation, IAU, India, inflation, investments, Jeffrey Nichols, Jim Rogers, Keith Fitz-Gerald, majors, Marc Faber, market crash, Markets, Michael Zielinski, mid-tier, mining companies, monetization, Moving Averages, NGC, NXG, PAL, palladium, Peter Grandich, Peter Schiff, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, protection, recession, risk, run on banks, safety, Sean Rakhimov, silver, silver miners, SLW, small caps, sovereign, spot, spot price, stagflation, Technical Analysis, TIPS, U.S., U.S. Dollar, volatility, warrants, XAU

     As I write Gold is down $3.00 at $966 (nearest futures month). It is still holding around the $960 to $965 support levels. However, I want to assert this, Gold is in a long term upward trend. The only thing that would change my thinking would be a close under the $880 which represents the bottom level of the long term uprward channel. We may however in the short term see a correction downward to even as low as $900 to $910. I will be watching very closely as this may be a “bear trap” in an upward market. One thing however I am somewhat of a contrarian. Last week almost every analyst under the sun was touting Gold as the ONLY investment. When I see that I get very nervous and know that a correction is about to happen.  For those who remember the day silver hit $50 oz., Walter Cronkite announced on his evening new that “It’s time for everyone to go out and buy some silver”! The very next day the silver market tanked like a lead balloon. So a little downside action here will be a good thing to shake out the “nervous nellies” and “johnny come lately’s” out of the market. Because I have seen it time and time again as soon as that happens “Kaboom” the market takes of and does not look back. I will be watching very carefully here and will let you (those who have subscribed to this blog and are following me on twitter), when I get out of the DGP trade. I got in at $890 oz and think a little patience here will pay off.  Given the current state of things Gold could still easily hit $1050 this week as well as have a price correction. Be sure to subscibe in the top right corner and/or follow me on twitter to be kept up to date…

     The best investment in my opinion right now is to continue accumulating the Junior and Mid-tier Gold and Precious Metals mining companies. Once again there are many still selling at or near book value levels. Remember to choose companies who currently have production or are about to start producing. One exception might be those companies who have made some big strikes,  are sitting on huge “proven” reserves, and have plenty of cash and financing to bring those reserves into production in the future. Another play is to investigate “Warrants” which give you the right to buy a stock at a given price for a certain timeframe. There are many out there which could give your portfolio a couple of “home runs” gains of 2-3000%. Either way do your own good due diligence, check the companies out, their balance sheets, prospectus/s  and consult your own financial advisors before making any trades.- Good Investing! -jschulmansr

==========================

Follow Me on Twitter and be notified whenever I make a new post!


Catch the New Bull! – Buy Gold Online – Get 1 gram free just for opening account– just click here and then again on the Gold Bar!, no minimums – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

=============================

Panic=Gold – Seeking Alpha

Source: Hard Assets Investors

It’s axiomatic that gold has a role as safe haven for many investors. That this is largely a matter of collective psychology is irrelevant – it has worked for centuries, and it’s unlikely to stop working tomorrow.

 But lately, gold been more than a mere market hedge; it’s been a panic hedge.

Current Gold

Gold briefly nudged over the $1,000 mark to $1006.43 on Friday, February 20, before settling back down to close at $993.25. It was the first time since last March that gold crossed the insignificant but satisfyingly round $1k level. Technical geeks would point out that it’s still below the high of $1012.55 hit March 18th, but that’s splitting hairs.

Of course, gold didn’t stay above $1,000/ounce for long last March; it quickly reversed course and traded down all year, before bottoming at $712.41 on November 20th. Since then, gold has risen 39.4%; it was up 13.4% in January alone.

The last time I wrote about gold (Demanding Gold) was just before that November bottom. Back then I discussed the underlying demand for gold – because one of the great things about commodities is that ultimately, they’re always about supply and demand. And with the gold-bug’s most important supply and demand report out for 2008, it’s the perfect time to revisit the subject. (The full link to the World Gold Council’s Supply and Demand Statistics for Q4 and Full Year 2008 report is here.)

Looking At Demand

Gold demand can be broken into three main areas of interest – jewellery, which accounted for roughly 58% of identifiable demand in 2008, industrial and dentistry demand, and finally identifiable investment demand.

On the whole, gold saw demand grow 4% from 2007 to 2008, but the picture is a bit more complex than just that.

Not everything was rosy for gold in 2008. As we predicted, jewellery demand was down significantly. In 2007 around 68% of gold demand was attributed to jewellery consumption. In 2008, that number dropped to 58%.

At the end of December, The World Gold Council released a report entitled “What Women Want: Global Discretionary Spending Report 2008“. In it, the WGC details the values and significance different countries attribute to gold jewellery and why people buy it. One new thing the study uncovered is that gold jewellery is now competing with items such as cell phones and other everyday items for discretionary spending.

The report also states that “confidence that gold will hold its value has waned,” reflecting in part the volatility gold prices have experienced in the past year. With gold rising and falling by 30% in a single year, it’s no wonder people are feeling less comfortable with it as a store of value.

Demand on the jewelry front appears to be price elastic. In India, the largest consumer of gold jewellery, demand in the fourth quarter more than doubled compared to Q4 of 2007. While this would seem to buck the year-long numbers, it’s likely due to the fact that lower gold prices occurred precisely at the time of the Diwali festival – a peak gold-buying time in India. In 2007, gold prices were high during the festival, which depressed demand. For the full year of 2008, jewellery demand in India dropped 15%.

China was one of the only countries that posted an increase in demand for jewellery, up 8% from 2007. Much of this demand was for 24-karat jewelry, which commonly implies jewellery purchases that are doubling as investments.

The Big Stick: Gold Bugs

According to the World Gold Council report, gold demand for investment rose from 663.7 tonnes in 2007 to 1090.7 tonnes in 2008 – a somewhat staggering year-on-year increase of 64.3%. Retail investment – things like bar hoarding, official coins, medals/imitation coins and other kinds of retail investment – almost doubled, going from 410.3 tonnes in 2007 to 769.3 tonnes in 2008. That gives some credence to the wide scale anecdotal evidence throughout the year that gold coins were virtually impossible to obtain in many countries.

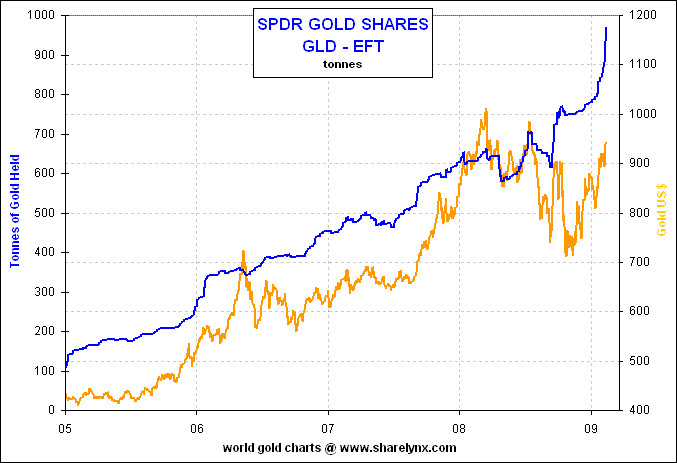
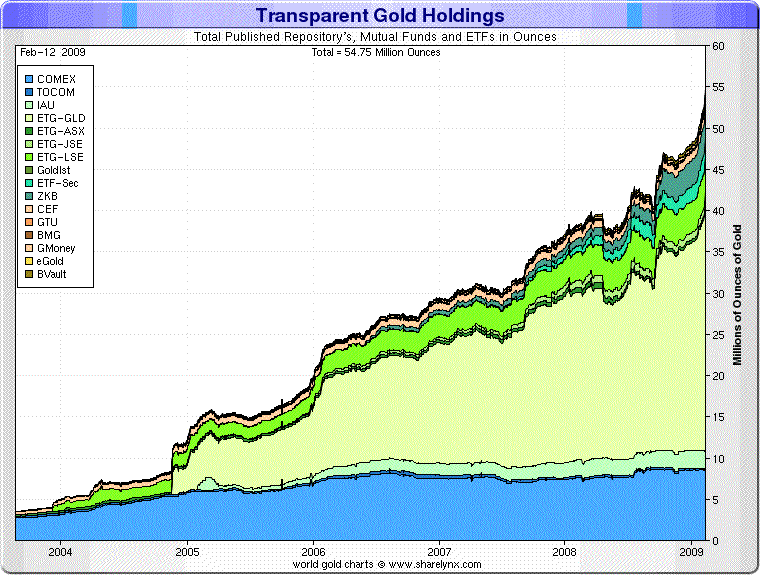
Exchange-traded funds and similar products also showed a large increase, from 253.3 tonnes to 321.4 tonnes (a 26.9% increase). This trend has continued into 2009. The SPDR Gold ETF (NYSE: GLD) – the largest physical gold trust – now has 1,028.98 tonnes in its vaults. This is a trust that started 2009 with 780.23 tonnes, meaning its gold horde has risen 31.9% in less than two months. To put that in perspective, 249 tonnes is over 10% of the total amount of gold mined in all of 2008. This acceleration happened almost entirely in a dramatic surge mid-February.

Net-net, however, if you offset the huge rush in gold investments with the significant drop in jewelry demand, the net gain in tonnage terms was just 4%.

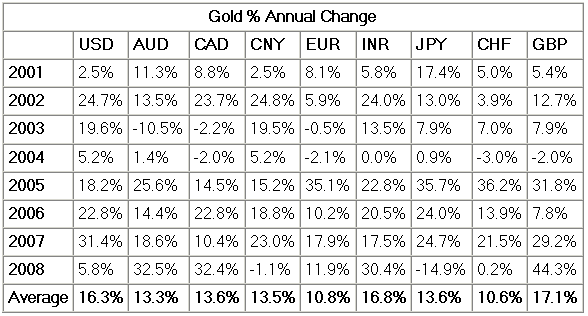
There is, however, another way to look at things. When viewed through the (occasionally depressing) lens of the dollar, gold demand seems endless:

Gold Supply in Flux

With the demand part of the picture in hand, it’s time to turn to supply. The third quarter of 2008 saw a huge supply deficit with demand far outreaching supply. In the fourth quarter, supply rose 19%, almost entirely due to an increase in gold scrap. Yes, that’s right: Those late night commercials offering to buy your old tangled gold necklaces were on to something, and people were selling.

Scrap sales for 2008 ended up 17% higher than 2007, and that along with slightly higher total mine supply just about offset lower central banks sales so that in the end, 2008 ended the year with only 1% less total supply than 2007 – practically even.

The moral of the story is simple: supply and demand remain incontrovertible laws. The unbelievable demand vs. the stagnant (mine) and dwindling (central bank) supply created a vacuum, and a new source came on line to fill the need. Thus, at least indirectly, gold went from the scrap heap into brand new shiny gold coins, just when the market needed them the most.

Which brings up the question: how long can consumers fill their own demand through scrap? And what price level is needed to support the tremendous scrap levels already in place?

=================================

Catch the New Bull! – Buy Gold Online – Get 1 gram free just for opening account– just click here and then again on the Gold Bar!, no minimums – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

==================================

 Five Weeks of Silver Backwardation – Seeking Alpha

By: Trace Mayer of Run to Gold.com

During an interview with Contrary Investors Cafe on 24 February 2009 I discussed both gold backwardation and silver backwardation. After the interview I was asked why more commentators are not discussing this issue. I do not know.

Regarding money there are two competing views: (1) money is determined by the market or (2) chartalism which asserts that ‘money is a creature of law.’ Governments can only manage money if they create it. Obviously, the market determines money because money existed before governments were created.

Regarding gold there are two competing paradigms: (1) gold is a commodity and (2) gold is money. Paradigm (1) asserts that gold is a hedge against inflation and there is no monetary demand for gold. On the other hand, paradigm (2) asserts that gold is a hedge against currency collapse and the primary demand for gold is monetary. I subscribe to the second paradigm and assert that at all times and in all circumstances gold remains money.

WHAT IS SILVER’S ROLE

Under which paradigm does silver fall? Is silver a commodity or is silver money? For a commodity to be money its primary demand must be monetary.

Like gold, for thousands of years silver functioned as money in the market. The term dollar, as used in Article 1 Section 9 Clause 1 and the Seventh Amendment of the US Constitution, is defined as 371.25 grains of fine silver under Section 9 of the Coinage Act of 1792. Governments stockpiled billions and billions of ounces. However, on 24 June 1968 the United States government defaulted on their silver certificates. Over the decades, silver, like gold, has been demonetized in ordinary daily transactions. Supposedly there are large stockpiles of gold in central bank vaults. Unlike gold there are no reported large above ground stockpiles of silver stashed in central bank vaults. Additionally, a large portion of silver demand is industrial as it is used in cell phones, refrigerators, dental equipment, computers, etc.

Therefore, it appears that silver is confused about its role. In other words, silver functions as a commodity and as quasi-money.

FIVE WEEKS OF SILVER BACKWARDATION

While similar, there are differences between future and forward contracts. For example, future contracts are traded on exchanges, use margin and are marked to market daily. In contrast, forward contracts are generally traded over-the-counter (OTC derivatives) and are not marked to market. Therefore, forward contracts are subject to greater counter-party risk than future contracts.

Because the primary reason backwardation arises is counter-party risk and because forward contracts are impregnated with greater counter-party risk than future contracts, therefore it is highly likely that backwardation would appear in the forwards markets before the futures markets.

This is precisely what has happened. While the COMEX silver futures contract have not been in backwardation the LBMA Silver Forward Mid Rates have been in backwardation for five consecutive weeks. Of particular interest is the 6 month contract.

SO WHAT?

What does all this mean? Well, I think the backwardation reflects the market’s uncertainty of silver’s role as money. The chronic silver backwardation began on 8 December 2009, the same day I wrote about gold in backwardation, and silver was priced about $9.60. Currently silver is trading about $13.82. Predictably, the gold/silver ratio is narrowing. If the backwardation persists it will be interesting to see if silver’s price in illusory FRN$ continues rising.

In my opinion, as the great credit contraction grinds on and intensifies, the commodity silver will reassert itself as money and eventually currency. As I mentioned during the interview with Contrary Investors Cafe what would be really interesting is if the central banks decide to start hoarding silver!

In the meantime it may behoove those who are bullish towards silver to increase the pressure on physical silver delivery. For example, I purchased some beautiful Austrian philharmonics at the Cambridge House Investment Conference and Silver Summit over the weekend. The beautiful coin cost $20 which was an amazing $5.50 over spot.

While there are cheaper ways to purchase physical silver bullion, like GoldMoney, these huge premiums over spot beg the question: What is the real silver price? With the specter of counter-party risk driving silver into backwardation if there is a failure to deliver then it will likely cause the silver price to shift from the COMEX just like a failure to deliver would cause the gold price to shift from the COMEX.

Bottom line: Do not get caught with your paradigms down!

===============================

Catch the New Bull! – Buy Gold Online – Get 1 gram free just for opening account– just click here and then again on the Gold Bar!, no minimums – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

================================

Doug Casey: What to Do in “The Greater Depression” — Seeking Alpha

Source: The Gold Report


Bullion and oil appear in the lineup of power players that Doug Casey thinks investors can count on as the world slips deeper and deeper into what he calls the “Greater Depression.” Despite the raging economic storm and Doug’s doubts that Western civilization’s governments will take the actions needed to quell it, though, the Chairman of Casey Research is nowhere close to calling the game. In fact, he sees silver lining in the clouds of crisis—opportunity—and expresses optimism that technological advances, coupled with capital rebuilding once over-consumption runs its course, will prevail eventually. The Gold Report caught up with the peripatetic author, publisher and professional international investor between polo matches in New Zealand, one of several nation-states he calls home from time to time.


The Gold Report: You’ve been discussing what you’re calling “crisis and opportunity,” and in fact have a summit by that same name coming up in Las Vegas next month. Could you give us a high-level overview of what you foresee?

Doug Casey: We’ve definitely entered what I describe as the Greater Depression. It’s not coming; it’s here. It’s going to get much, much worse as far as I’m concerned and unfortunately, it’s going to last a long time. It doesn’t have to last a long time, but the root cause is government intervention in the economy and everything they’re doing now is not just the wrong thing, it’s the opposite of what they should be doing. It’s almost perverse.

The distortions and misallocations of capital and the uneconomic patterns of production and consumption that have been going on for over a generation need to be liquidated and changed, but everything the government’s doing is trying to maintain these patterns. So it’s going to be horrible. In addition, the government is necessarily directing more power toward itself with all of its actions. If I were you, I’d rig for stormy running for a good long time.

TGR: By “a long time,” do you mean a couple of years, a decade, a generation?

DC: This is, in some ways, uncharted territory. Let me say that for the long run I’m very optimistic. Why? Two things act as the mainsprings of progress. Number one is technology and that’s going to keep advancing, so that’s very good. Second is capital and savings. Individuals will solve their own problems and, therefore, they will stop consuming more than they produce, which is what they’ve been doing for years, and they’ll again start producing more than they consume. The difference is savings; that builds capital.

So technology and capital are going to solve the depression. But the government can do all kinds of stupid things to make it worse. Look at the Soviet Union. They suffered a depression that lasted 70 years from its founding. Look at China. The whole reign of Mao was one long economic depression. That could certainly happen in the U.S., too, where the government misallocates capital in such a way that technology doesn’t advance as it could and people can’t build individual capital the way they would. I’m optimistic, but anything can happen.

TGR: But didn’t China and the Soviet Union have governmental structures very different from those in Western Europe and the U.S., and those structures allowed for more intervention? Are you projecting that we might slip into an era where Western civilization will allow their government to run themselves like the Soviet Union and China did?

DC: It seems to be going in that direction. Of course, Europe is going to be hurt much worse than the U.S. Europeans are much more heavily taxed and much more heavily regulated. The average European is much more reliant upon the state psychologically as well as economically. So it’s all over for Europe and this doesn’t even count the problems that they’re going to have in the continuing war against Islam, which are much more serious for Europe than they are for the U.S. So, no, Europe is fated to be nothing but a source of houseboys and maids for the Chinese in the next generation.

TGR: So do you think that societies in Western Europe—and even the U.S.—will allow themselves to be governed in the same fashion as the Soviet Union and China were during their depressions?

DC: Oh, totally. I don’t see why that would not be the case. Even Newsweek says we’re all socialists now. That seems to be the reigning ideology. In addition, psychologically, the average American—just like the average European—looks to the government to solve things. This is very bad. Most people are unaware that Homeland Security, which is one agency that should be abolished post-haste, is building a 400-acre campus in southeast Washington, D.C., where initially they’re going to put 25,000 employees. That’s as many as the Pentagon has and with 400 acres, Homeland Security has a lot more room to grow. Ironically, the property is at the site of St. Elizabeth’s Hospital, the first federal insane asylum in the United States. Once a bureaucracy has a piece of real estate and builds buildings, it’s game over. They’re just going to accrete and grow and grow, so that’s one indication. The trend is clearly in motion.

It’s all over for the U.S. In fact, let me say this. America doesn’t exist anymore. What is left is not even these United States. That was decided in the 1860s. It’s the United States. America, which is basically an idea, a concept, is dead and gone. The United States is just another of 200 awful little nation-states that have spread across the face of the earth like a skin disease. There’s no longer any difference that I can tell between the U.S. and any other country.

TGR: How would you describe the concept that America was based on that is now gone? And is there another country in the world embracing that concept? Will there be a new America?

DC: No, there is no other place. I’ve been to 175 countries and lived in 12. My feeling is that the best thing that you can do is set your life up so that you’re not to be considered the property of any one government. You might have a passport or several passports and, therefore, that government thinks they own you. But if you don’t spend time in a country, practically speaking, there’s nothing they can do about it.

So, no, there is no real haven for freedom in the world today. The best you can do is go where the governments are so unorganized that they can’t control you effectively. That’s one reason I like to spend time in Argentina. They have an incredibly stupid government, but they’re also very inefficient and ineffective. So it’s wonderful as a place to live. I also spend time in Uruguay, because it’s a tiny little country with no ambitions to conquer the world. The nice thing about New Zealand, where I am now, is that it’s a small country, only 4 million people, lots of open land. It’s got some severe problems, but it’s pleasant. I think the U.S. is going to be the epicenter of a lot of problems in the years to come.

TGR: Few of our readers are probably in positions where they could live in 12 different countries, but they have amassed assets here in the United States. What advice would you give them to safeguard those assets?

DC: The key is to remember that we’re going to have a long and deep depression, so most things that worked well over the last 20 years are unlikely to work well in the future. I’d been predicting the real estate collapse for a long time. It’s still got a way to go, too, because a lot of real estate debt remains that has to be liquidated. There’s a lot of leverage out there and there’s been a huge amount of overbuilding. So it’s far too early to get into real estate, at least in North America or Europe.

It’s also way too early to get into the general stock market, for all kinds of reasons. Dividend yields are still extremely low. Earnings are going to collapse. Government bonds are perhaps the worst single thing to be in, because with the government printing up money literally by the bushel basket, the dollar is going to start losing value radically and interest rates are going to start going up radically at some point. So you have to rule out most stocks.

I’m afraid that the most intelligent thing you can do is to own a lot of gold, preferably gold coins in your own possession. And I think speculation in gold stocks makes sense at this point, because gold stocks are about as cheap as they’ve ever been relative to other assets, really, in history. Now is an excellent time to do that as well. But that’s in terms of speculation.

Investment risk is tough enough, but the biggest problem is political risk. That’s what you have to watch out for. That means you have to diversify internationally. This is harder for most people, harder psychologically, and it takes more assets to make international diversification viable. But if you’re in a position to do it, it’s the most important thing you can do.

TGR: Since you mentioned having coins in your own possession, should we assume you’re not a big fan of the ETFs or some of these other paper gold promises, if you will?

DC: ETFs are okay for the convenience that they offer and for significant amounts of money, but gold coins should be first on your list, no question about that. If you’re only talking about $50,000 or $100,000, or $200,000, coins are fine to keep in your own possession. They won’t take up much room and you can put them in some safe place (which, incidentally, is not a bank safe deposit box).

TGR: Are you recommending putting all of your investment in gold into the bullion or are you also recommending some portion in producing junior and explorations?

DC: Both, but look at the stocks as being speculative. Most of your money should be in gold with a bit of silver, too. Silver is basically an industrial metal, but it has monetary characteristics. Now is the time to be very overweight in the metals and I think owning gold stocks is a good idea. They’re very cheap.

TGR: Anything else investors can do to preserve whatever may remain of their wealth?

DC: Owning real estate in some foreign countries is a very good idea—from a lifestyle point of view, an asset diversification point of view, and a possible capital gains point of view, too. They can’t make you repatriate foreign real estate. Having some U.S. dollar cash while we’re going through this deflationary period is very wise as well, but that’s not going to last. Eventually the U.S. dollar is going to reach its intrinsic value.

TGR: Not that you have a crystal ball, but how would you see the rest of ’09 playing out?

DC: Nothing goes straight up or straight down, but it seems that ’09 is going to see much higher gold prices and much lower stock prices and much lower bond prices, too. But remember, the worst is yet to come.

You haven’t heard an awful lot about people losing their pensions yet, but that’s going to happen because what are pensions invested in? They’re mostly invested in stocks and bonds and commercial real estate. All three of those things are disaster areas, and bonds are the big disaster area yet to come. So I think it’s going to be nothing but bad news in 2009. What happened in 2008 was just an overture to what I think is going to happen in ’09 and ’10.

TGR: Even into 2010?

DC: Yes. This isn’t going to be cured overnight, mainly because of what the government’s doing. As I said, it’s perversely exactly the opposite of what they should be doing, which is abolishing all the agencies and freeing up the economy. They’re passing lots of new regulations, they’re going to have to raise lots of taxes eventually, and they’re inflating the currency. So it has to last, at least into 2010. It’s going to be quite dismal, actually.

TGR: And what happens with the unfunded Medicare liabilities?

DC: They’re not going to be funded. They’re going to be defaulted on and, actually, that’s the best thing that could happen. That’s one of the things that should be done now; the U.S. government should default on its debt. This is shocking for people to hear, but it wouldn’t be the first time the U.S. government has done that. It did that almost at its founding in continental days.

This debt represents a tax liability that’s being foisted off on the next generations who have no moral obligation to pay and should not pay. I think as an ethical point, the U.S. should default on this debt. It’s impossible to pay it back, and it won’t be paid back. It’s more honest to acknowledge that bankruptcy now as opposed to pretend it’s going to be paid back. Defaulting even might forestall runaway inflation in the dollar, which would be a catastrophe of the first order. So it’s the smart and moral thing to do, and it’s going to happen eventually anyway. All the real wealth will still be here; a lot of it will just change ownership. The big losers will be those who lent to the State, thereby enabling its depredations, and they deserve to be punished.

But even a default tomorrow will do no good unless you put the U.S. government into reverse and disband all of these ridiculous, destructive agencies that have grown like a cancer for years. Taxes should be cut 50% to start with, just out of hand. And the defense establishment—it’s a misnomer; it’s not defense at all but rather foments wars around the world—should be cut hugely. Not with a butcher knife; but a chain saw. But none of this is going to happen; in fact, just the opposite. That’s why I’m so pessimistic now that the tipping point’s finally been reached.

TGR: Are we at the tipping point?

DC: Yes, we’ve absolutely gone over the edge. The consumer is no longer in a position to consume. Everybody is going to cut consumption to the bone and hopefully find something to produce instead. It would be better for people to start viewing themselves as producers than consumers. That would be a step in the right direction to get them psychologically more in line with reality.

TGR: In last fall’s meltdown, gold held up, but the stocks didn’t. Quite a few producers and soon-to-be producers, and some companies making discoveries, seem to have bottomed out in November and December. But worry persists in the market. Suppose another shoe drops or another black swan appears? Richard Russell (Dow Theory Letters) and others have been talking about the Dow going down to 5,000. What would that do to the gold stocks?

DC: Gold stocks are also stocks, and the best environment for gold stocks historically has always been when both gold and the stock market are going up. But since the last gold stock bull market came to an end, I think it’s entirely possible to see a bubble develop in gold stocks with all the money being created. I certainly hope so. I’m actually optimistic for gold stocks just because they’re so cheap relative to everything else.

TGR: They have been beaten down.

DC: Yes. And that fact, along with the waves of money being printed around the world and the much higher gold prices we are going to see, could cause a speculative mania to develop in the gold stocks. Nobody’s even thinking about that possibility right now, because they’re so battered. But this is the time to get into the right ones because it’s likely to happen in the future.

TGR: The ’29 crash—which was really the preamble, because ’30, ’31, ’32 and ’33 were certainly bigger—is when gold stocks such as Homestake did their best. How do you see that playing out this time around? Is it different this time or do you expect a similar pattern?

DC: You know what they say, “History doesn’t repeat itself, but it rhymes.” I think that, first of all, the gold mining industry is a much worse industry now than it’s ever been in the past, because just as all the easily defined light sweet oil basically has been discovered, all the easy-to-find high-grade gold basically has been discovered. Most mines that are going into production are low-grade, which means that you have to move a lot of dirt, which means that they’re much more capital-intensive than in the past. So gold mining’s a worse industry from that point of view.

Also, politically speaking, with the rise of the green movement, there are people who don’t want any oil burned, any dirt moved, any trees cut. They don’t want to see anything happen. This makes it much harder to do gold from a permitting and political point of view. We’re in a much higher tax environment than in the past. So it’s a tough industry. It really is. It’s just a 19th century choo-choo train type of industry that interests me only as a speculative vehicle. You’ll notice that gold went from lows of about $300 to highs of about $900 and none of these gold companies are making any money because their costs actually went up faster than the price of gold. So I’m not saying gold mining is a great business. It’s not. It’s a crappy business. Still, we could have a bubble in the stocks. I’m hoping we do.

TGR: Aren’t we going to see a change in that in ’09? Oil, which is one of the large components of that cost, has come down dramatically. A lot of these producers must be locking in oil at these lower prices. Won’t that translate into year-over-year earnings increases for the gold producers?

DC: That’s possible. The producers actually may show increases for the next couple of years. I don’t doubt that. But I don’t think oil will stay where it is. I think oil’s eventually headed back to $150 a barrel or more.

TGR: So why wouldn’t you own oil as well as gold?

DC: It’s a good idea, but we weren’t really talking about oil. I’d say that oil is a good thing to own. Oil is a real buy now. It’s as good a buy at $40 as gold is at $900 right now. Maybe a better buy; who knows?

TGR: If we go into worldwide depression, will oil continue to be a good buy or will it self-regulate around this $40 a barrel?

DC: I am bullish on oil. Although I’m philosophically not very sympathetic to the peak oil theory, I think it’s a geological fact. Also, China and India and the other developing parts of the world don’t use a whole lot of oil now. As they develop, they will to want—and almost need—to use a lot more oil. That’s going to keep pressure up on the demand side. But the supply side actually finally is constrained, so it’s going to mean higher prices. In a depression-type environment, U.S. and Western oil consumption could drop a lot, but the third world would take up most of that slack. So I have to be bullish on oil.

TGR: Are you bullish on any other sectors or commodities?

DC: I’m bullish on agricultural commodities. They ran way up last year and then collapsed again. I think a good case can be made that most of the soft commodities are quite cheap and will go higher, so I’d look at those, too. I think gold definitely, oil in the years to come has the potential to go much, much higher, and the agricultural commodities have a lot of potential.

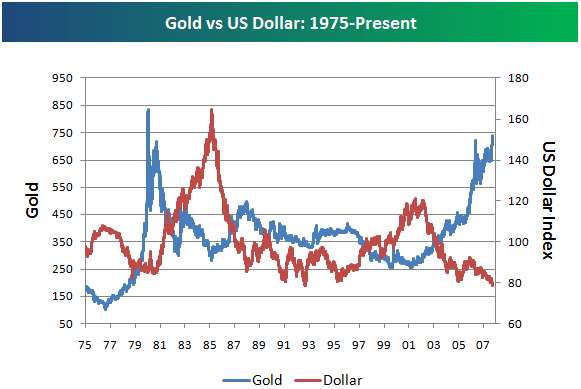
TGR: Gold appears to be uncoupling from the dollar. Historically, when the dollar was strong, gold would be weak. But we’ve had a couple of recent instances in which both the dollar and gold have been strong. Obviously, we’ve seen a total decoupling of gold from oil. It used to be when oil was running, gold was running and vice versa, but that no longer seems to be the case. Is that just an old wives’ tale or is something going on?

DC: I’ve never seen any necessary relationship between gold and oil, just like there’s no necessary relationship between rice and natural gas, or nickel and soybeans. All these commodities tend to move together, all the currencies tend to move together and stock markets tend to move together, but they all have their own dynamics. I think it makes sense to compare the relative prices of various commodities and see what may be cheap or dear relative to other things based on the fundamentals.

On any given day, somebody may have to buy or somebody may have to sell a huge amount of almost anything. It’s unpredictable and you can’t tell what constraints are out there in the market. I don’t even pay attention to day-to-day fluctuations because they’re just random noise. I watch the big trend. It’s been shown that if you just made one correct trade and stuck with it at the beginning of every decade for the last four decades, you would have realized something like 1,000 times on your money. To me, this is the proper approach to the markets, not to try to second-guess from day-to-day what’s going to happen. That’s foolish because you get chewed up with commissions and bid-ask spreads and double-thinking your own psychology and so forth.

I really just like to look at long-term trends. In terms of long-term trends, you’ve got to be long gold, long silver, long oil; you’ve got to be short bonds. I think that’s really all you need to know. The other things we mentioned such as agricultural commodities and so forth are worthy of attention. But, as I said, I’m not a day-to-day trader. I think that’s very foolish.

TGR: Are these the themes that you and your group of speakers will focus on in Las Vegas?

DC: They are. I certainly want to invite anybody who reads this interview to join us. We put on very small, very classy seminars. They’re not gigantic mob scenes, so it’s possible to get to know individual speakers and fellow attendees in a very collegial atmosphere. I think it’s something that anybody who’s seriously interested in these kinds of things should consider.

The Casey Research Crisis & Opportunity Summit, will be held March 20 – 22, 2009, at the Four Seasons Resort in Las Vegas.

A citizen of the world in more ways than most of us can imagine, Doug Casey, Chairman of Casey Research, LLC, is the international investor personified. He’s spent substantial time in about 200 different countries so far in his lifetime, living in 12 of them (currently New Zealand and Argentina). And Doug’s the one who literally wrote the book on crisis investing. In fact, he’s done it twice. After The International Man: The Complete Guidebook to the World’s Last Frontiers in 1976, Doug came out with Crisis Investing: Opportunities and Profits in the Coming Great Depression in 1979. His sequel to this groundbreaking book, which anticipated the collapse of the savings-and-loan industry and rewarded readers who followed his recommendations with spectacular returns, came in 1993, with Crisis Investing for the Rest of the Nineties. In between, his Strategic Investing: How to Profit from the Coming Inflationary Depression (Simon & Shuster, 1982) broke records for the largest advance ever paid for a financial book. Bill Bonner (The Daily Reckoning) describes Doug as “smart, hard-working, and extremely knowledgeable” with “an instinct about investments that has made him and many of those around him very rich.”

 Doug, who now spends more time as an expatriate than he does on American soil, has appeared on NBC News, CNN and National Public Radio. He’s been a guest of David Letterman, Larry King, Merv Griffin, Charlie Rose, Phil Donahue, Regis Philbin and Maury Povich. He’s been the topic of numerous features in periodicals such as Time, Forbes, People, US, Barron’s and the Washington Post – not to mention countless articles he’s written for his own various websites, publications and subscribers.

 ==================================

Catch the New Bull! – Buy Gold Online – Get 1 gram free just for opening account– just click here and then again on the Gold Bar!, no minimums – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

That’s all for Today- Enjoy! jschulmansr

Follow Me on Twitter and be notified whenever I make a new post!

================================== 

Nothing in today’s post should be considered as an offer to buy or sell any securities or other investments; it is presented for informational purposes only. As a good investor, consult your Investment Advisor/s, Do Your Due Diligence, Read All Prospectus/s and related information carefully before you make any investing decisions and/or investments. –  jschulmansr


Share this:

  • Share on Reddit (Opens in new window) Reddit
  • Share on Facebook (Opens in new window) Facebook
  • Share on LinkedIn (Opens in new window) LinkedIn
  • More
  • Share on X (Opens in new window) X
  • Share on Pinterest (Opens in new window) Pinterest
  • Share on Tumblr (Opens in new window) Tumblr
  • Print (Opens in new window) Print
  • Email a link to a friend (Opens in new window) Email
Like Loading...

Going For The Gold!

20 Friday Feb 2009

Posted by jschulmansr in banks, bull market, capitalism, central banks, China, Comex, Copper, Currencies, currency, Currency and Currencies, deflation, diamonds, dollar denominated investments, economic, Economic Recovery, economic trends, economy, Fed Fund Rate, Federal Deficit, federal reserve, Finance, financial, Forex, Fundamental Analysis, futures markets, GDX, GLD, gold, Gold Bullion, Gold Investments, gold miners, How To Invest, How To Make Money, hyper-inflation, IAU, inflation, Investing, investments, Iran, Israel, Japan, Jeffrey Nichols, Jim Sinclair, Jschulmansr, Junior Gold Miners, Latest News, majors, Make Money Investing, market crash, Markets, mid-tier, mining companies, mining stocks, oil, palladium, Peter Grandich, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, silver, silver miners, small caps, sovereign, spot, spot price, stagflation, Stimulus, Stocks, TARP, Technical Analysis, Tier 1, Tier 2, Tier 3, Today, U.S. Dollar, XAU

≈ Comments Off on Going For The Gold!

Tags

ANV, Austrian school, AUY, Bailout News, banking crisis, banks, bear market, Bollinger Bands Saudi Arabia, Brian Tang, bull market, CDE, central banks, China, Comex, commodities, Copper, Currencies, currency, deflation, Dennis Gartman, depression, DGP, dollar denominated, dollar denominated investments, Doug Casey, economic, economic trends, economy, EGO, Federal Deficit, financial, Forex, FRG, futures, futures markets, gata, GDX, GG, GLD, gold, gold miners, hard assets, HL, hyper-inflation, IAU, India, inflation, investments, Jeffrey Nichols, Jim Rogers, Keith Fitz-Gerald, majors, Marc Faber, market crash, Markets, Michael Zielinski, mid-tier, mining companies, monetization, Moving Averages, NGC, NXG, PAL, palladium, Peter Grandich, Peter Schiff, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, protection, recession, risk, run on banks, safety, Sean Rakhimov, silver, silver miners, SLW, small caps, sovereign, spot, spot price, stagflation, Technical Analysis, TIPS, U.S., U.S. Dollar, volatility, warrants, XAU

As I write Gold today has touched a high so far of $1000.30! If it breaks this level and holds then $1025-$1050 will be the next stop. At this point I would buy on any dips. This run is going to take us at least to $1050 oz. cont…

**********We officially just broke the $1003 all time high! *************** ******************Market up $28.50 to 1005.00!!!***********************

cont…

After that then we will probably see a retracement potentially down to previous resistance levels now support levels.

I would not be worried at all if we go as low as $940 – $960. That would be normal market action. However a note of caution, as Gold is not necessarily following normal market action as evidenced by the dramatic run to $1000 and then down to $690 approximately.

I am still a buyer on any dips and at this point I am holding my physical gold and still getting in to some of the Gold and Silver producers who are still selling at or near book values. As far as DGP goes I am still holding my position and will let you know when I exit that trade.

Remember in the worst case scenario with Gold, you are still locking in the “buying power” of your current dollars. With Bernake running the monetary printing presses at full steam, we will see inflation return. Already the true (not government manipulated figures) inflation rate is running at 6% – 9% depending on who you are following. However, when I go to the grocery story and see a package of hot dog buns that I could buy a few months ago at $1.00 for a package of 8, now selling for as high as $4.00 for the same package; it would seem that the true inflation rate is way higher up around 12% – 18% already!

So I am still looking at “protecting my dollars”,  by converting them into Gold. You would be wise to do the same, because soon the manipulated value of the dollar will come crashing down; along with all the other major currencies as all of the central banks are printing money and trying to flood their markets with liquidity. 

As I mentioned in yesterday’s post  Gold is on a major Bull Market run and all of the movement is based on current financial pressures, still without any major news like a new war/conflict especially in the Middle East (i.e. Israel taking out Iran’s nuclear reactor), or major terrorist act. Buy gold “wholesale” thru Comex, take physical delivery, if we all do this we’ll be putting major pressure on the “shorts” and potentially cause a “short squeeze”! Then you see Gold bid up to some amazing levels and be able to jump in and make some quick profits.

“Nothing will unnerve the paper gold shorts more quickly and do more to undercut their confidence than to strip them of the real metal and force them to come up with more hard gold bullion to make good on deliveries. “Stand and Deliver or Go Home” should be the rallying cry of the gold longs to the paper gold shorts.” –Trader Dan Norcini

Otherwise, hang on to your hats as the “Gold Express” has left the station and is barreling down the tracks! – Good Investing! – jschulmansr

Here is where I buy my Bullion, get one free gram of Gold just for opening an account! Catch the New Bull! – Buy Gold Online – Get 1 gram free just for opening account!, no minimums – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

==================================

Gold Pole Vaults to $1000 – Market Watch


By Polya Lesova, MarketWatch
Last update: 10:07 a.m. EST Feb. 20, 2009
NEW YORK (MarketWatch) — Gold futures topped the key $1,000 mark for the first time in nearly a year on Friday, as global financial and economic worries boosted the safe-haven appeal of the precious metal.
In recent action, gold for April delivery traded at $995.30 an ounce, up $19.50, or 2%, on the day. It earlier touched a high of $1,000.30.
Stocks fell to fresh bear-market lows in early action on Wall Street, with the Dow Jones Industrial Average ($INDU:
“There is a risk here of a panic sell-off in stock markets and the next leg down in the stock bear market looks imminent, as the ills of the global financial system virulently infect the global economy,” said Mark O’Byrne, executive director at Gold and Silver Investments Limited, in a research note.
“While gold has become overbought in the short term, its medium and long term fundamentals are as sound as ever,” he said.
Gold for February delivery, the front-month contract which registered very little volume, was last up $19.30, or 2%, at $995.40 an ounce on Globex. The February contract expires on Feb. 25. Earlier, February gold hit an intraday high of $999.50 an ounce.
On Thursday, the Dow industrials finished at 7,465.95, down 89.68 points to end at the weakest level since Oct. 9, 2002.
“The price slide of U.S. equities, with the Dow Jones Industrial Average falling to its lowest level since October 2002, should result in a continued positive mood of investors on gold,” said Eugen Weinberg, an analyst at Commerzbank.
Also on Globex Friday, March silver futures rose 46 cents, or 3.3%, to $14.39 an ounce, and April platinum futures gained $12.50, or 1%, to $1,089.00 an ounce.
March palladium futures gained 40 cents, while March copper futures fell 5 cents, or 3.5%, to $1.42 a pound. End of Story
Polya Lesova is a New York-based reporter for MarketWatch.
==============================
Gold has a “True Bull Run” – Financial Post
Source: MineWeb.com


Gold was, at the time of writing, close to $1,000 again. It would seem this level is inevitable sooner rather than later and this time the yellow metal may spend rather more time in the four figure area.

Author: Lawrence Williams
Posted:  Friday , 20 Feb 2009

LONDON – 

As this article was commenced, the gold price was at $997 and seemingly inexorably headed towards breaching  the US$1,000 level once again.  Indeed by the time you read this it may well already have done so.  April futures had already marginally gone through the $1,000 level.

The big question is, assuming spot gold does push through $1,000, will this be third time lucky for the gold bugs?  Gold has breached $1,000 twice beforehand and on each occasion its climb into the four figure level was shortlived.  This time it may well be a different situation with the likelihood that the price is poised to go higher still – and maintain its position above $1,000 for some little time to come.

Gold’s dollar high of $1,033.90 was achieved seemingly a very long eleven months ago but only remained at this exalted level for a few days , before crashing back.  Indeed as stock markets began to collapse and then plunged in the second half of the year, much confidence was lost in gold as an ‘insurance policy’ as it fell back to the high $600s at one stage, but the realisation came about that the main reason for the price decline was that funds and institutions were having to liquidate any tradable assets to meet their commitments, and gold s nothing if not tradable at any price.

Gold soon recovered and started a steady run back up to current levels despite rising markets and a strong dollar – usually both signs of a likely weakness in the gold price.  Indeed gold broke new price records in virtually all currencies other than the US dollar and now it looks highly likely to do so in terms of the now not-so-mighty greenback itself.  Meanwhile stock markets in general have started to fall back again as the world realises that the various stimulus packages worked out by clutching-at-straw governments are unlikely to improve matters drastically and much of the world heads for depression – or something approaching one.  There is no doubt we are already in recession in the West and depression is just the next, and infinitely more dangerous, phase of the current reality.

Gordon Brown has certainly not saved the world, and Barack Obama’s deification status is already tarnished after only a few days in office.  It is becoming apparent that what the politicians and economists with clout feel could be remedies to what is facing us ahead are nothing but untried and unproven stopgaps which patently are not working – or not at least yet.

Meanwhile banks are digging themselves further and further into the mire with more collapses and nationalisations likely, countries will default on their commitments and matters will continue to deteriorate unless some financial miracle happens.

Indeed the only world saviour may yet be China, but at what cost?  There are indications that the Chinese may have been in part responsible for the depth of the fall in commodity prices by halting industrial plants and infrastructure spending ahead of the Olympic Games and not resurrecting it afterwards as it could see an advantage in keeping prices down.  But the Chinese did not foresee the collapse in the western financial system exacerbating the situation dramatically and the global downturn came back to bite the Chinese in the bum as its exports crashed and huge numbers of people were thrown out of work – a potential cause of serious unrest.

Beijing has since taken steps to resurrect its infrastructure programmes.  Projects which were lying idle are at full swing again, but this is too little too late for much of the rest of the world. It may serve to keep China itself out of recession – and perhaps throw a lifeline to commodity producers to help them maintain output and support prices, but it’s definitely too late for much of the rest of the global economy which is in a frightening downward spiral.

But – with regards to securing commodity supplies and controlling future markets we are seeing China, with its huge funding capabilities, tieing up supplies, making major strategic investments in mining and metallurgical companies – and also in some other important western entities – and also providing loans to enable what they see as potential strategic partners stay in business.  But again, as we saw in yesterday’s European Nickel announcement on finance, there are China-benefiting clauses in most of these ‘strategic’ agreements.

It was Alfred Lord Tennyson in one of his Arthurian epic poems who used the phrase “The old order changeth, yielding place to new” and that is extremely apposite phraseology for what is happening now.  US economic imperialism has started to be replaced by a Chinese version.

But what has this to do with the gold price?  Because the Chinese were perhaps too late in re-implementing their own stimulus, which could have mitigated the global downturn at an earlier stage and possibly eased its speed, depth and perception, the realisation that gold could actually be the best way of protecting one’s assets began to filter through to previous unbelievers in the yellow metal. 

This has shown itself in the unprecedented inflow into metal purchases and ETF holdings which seem to be accelerating as the crisis deepens.  Never mind the fall-off in Eastern investment grade jewellery demand and the big rise in gold scrap sales.  ETFs are picking all this up (and global gold production is falling anyway).  But no matter, investment strength is always driven perhaps more by perception than by fundamentals (at least in full-scale bull or bear markets) and the current thought seems to be gaining more and more ground that gold is about the only serious safe haven out there.  The dollar may have proved to be a good bet of late, but everyone knows that pumping out money will ultimately be inflationary – and gold is traditionally a great inflation hedge too.

Indeed what gold is doing now is demonstrating that all western currencies are weak, rather perhaps than that gold fundamentals are strong, and the currencies are all devaluing against gold which is regaining its position as ultimate money – a position which believers say has never gone away!

So what of the performance of gold while this article was being written.  Well the price pulled back a little from the brink of bursting up through the $1,000 level and is, at the time of writing, sitting at $994 again, but the overall upwards drive for the moment seems unstoppable as financial news elsewhere continues to deteriorate.  Once gold goes through $1,000 this time it is not unreasonable to suggest it should perhaps stay there for a lot longer than last time – and maybe there is the prospect of a far higher peak.  Gold metal, ETFs, stocks and funds could have a way to run yet.

========================

Have A Great Day! – Good Investing! – jschulmansr

Catch the New Bull! – Buy Gold Online – Get 1 gram free just for opening account!, no minimums – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

========================

Nothing in today’s post should be considered as an offer to buy or sell any securities or other investments; it is presented for informational purposes only. As a good investor, consult your Investment Advisor/s, Do Your Due Diligence, Read All Prospectus/s and related information carefully before you make any investing decisions and/or investments. –  jschulmansr


Gold has a ‘true bull run’

This ‘bubble is still being blown up,’ analyst says

Jonathan Ratner, Financial Post  Published: Thursday, February 19, 2009


Safe-haven demand and a lack of investment alternatives continue to help gold break from its traditional trading relationships, rising toward a new record, despite a strong U. S. dollar and weak crude oil prices.

In fact, analysts at Genuity Capital Markets noted that gold has been trading more than US$200 per ounce above its normal value relative to the greenback. The firm also pointed out that the opportunity cost of holding bullion has diminished, with treasury yields at record lows and demand fundamentals deteriorating in the broader commodity and equity markets.

“Gold’s run since autumn, 2008, has been a true bull run, rising despite the strength of the U. S. dollar and outperforming virtually every other commodity and currency class,” said Canaccord Adams analyst Steven Butler. He told clients that bullion has set recent new highs in euros, pounds and Canadian dollar currency terms, among others.

Canaccord raised its peak gold price by another US$150, to US$1,100, now that gold has broken through the firm’s previous target of US$950.

“It is fair enough that gold may be in a bubble, but we think the bubble is still being blown up,” Mr. Butler said.

While credit risk has fallen from its recent highs, he noted that it is as elevated as during gold’s first peak last March, which coincided with the collapse of Bear Stearns. However, gold is still below the US$1,003 high set about a year ago.

Meanwhile, inflation may not be registering yet in terms of near-term expectations, but Canaccord believes that it and a general devaluation of paper currencies will be the result of the concerted monetary and fiscal policies to reflate the global economy.

Gold is known as a measure of real assets value because of its ability to preserve value during inflationary times. However, during disinflationary times like these, the current global growth and demand landscape also supports the notion of too many dollars chasing too few gold ounces, according to Ashraf Laidi, chief market strategist at CMC Markets in London.

He noted that the equity/ gold ratio has fallen about 85% from its 1999 peak, which occurred when gold stood at 20-year lows and equities reached their highs at the top of the dot-com bubble. Just as the equity/gold ratio stands at 18-year lows, the ratio of total financial assets to physical gold is near the low end of its historical range.

Mr. Ashraf also pointed out that the world’s available gold stock stands at only 5% to 6% of total global stock and bond market valuation.

Sustained investor interest in gold throughout 2008 helped push U. S. dollar demand for bullion to US$102-billion, a 29% annual increase, according to the World Gold Council. Its Gold Demand Trends report said identifiable investment demand for gold, which incorporates exchange-traded funds (ETFs), bars and coins, rose 64% last year. This is equivalent to an additional inflow of US$15-billion.

Genuity noted that holdings of the largest gold ETF, SPDR Gold Trust (GLD/NYSE), have increased by 26% since the beginning of 2009. So while bullion held in depositories on behalf of gold ETFs continues to grow from record levels, price volatility is an important consequence on both the upside and downside.

The ease of investing in gold via ETFs is matched by the ease of disinvestment, said Jeffrey Nichols, managing director of American Precious Metals Advisors.

“Just as quickly as gold-ETF depository holdings have grown, so might they shrink when sentiment changes,” he told clients.

This has already contributed to short-term volatility and may do the same for the long term, given that gold’s ultimate peak could be much higher than many had expected.

jratner@nationalpost.com

======================================

Catch the New Bull! – Buy Gold Online – Get 1 gram free just for opening account!,

no minimums – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

======================================


Gold stocks are flavour of the month again amongst major analysts – MineWeb

Source: MineWeb.com


The recent strong performance of the gold price vis a vis weak stock markets in general is again making gold stocks attractive to institutional and individual investors.

Author: Steve James and Euan Rocha – Analysis
Posted:  Friday , 20 Feb 2009

NEW YORK (Reuters) – 

The prospects for equity markets and numerous sector indexes have dimmed during the global recession, but gold and the companies that mine it have not lost their luster.

With gold prices nudging their all-time high and energy and other costs falling, mining company profit margins are widening, making their shares attractive, analysts said on Thursday.

“Within the next year, we will see the gold stocks sell at significant premiums to traditional earnings measures or net asset value measures,” said Robert Lutts, chief investment officer of Cabot Money Management in Salem, Massachusetts, which manages $400 million of client assets.

“I have owned Barrick Gold for one reason only — because it has the biggest pile of gold in the ground,” Lutts said of the world’s biggest gold producer, Canada’s Barrick Gold (ABX.N Quote)(ABX.TO: Quote).

“New interest continues in this increasingly attractive sector,” JPMorgan analyst John Bridges wrote in a note. “We feel all funds should have a core long position in the metal or the equities.”

Moreover, analysts expect acquisitions in the gold sector to accelerate, as larger players pounce on their cash-strapped smaller colleagues, in a bid to grow their asset base.

“I believe in investing in both bullion and stocks,” said Jeffrey Nichols, managing director of American Precious Metals Advisors. “Large companies with strong cash positions are in a good position to take advantage” of a higher gold price.

Lower fuel, raw materials and equipment costs, combined with weaker Canadian and Australian dollars and a flight to gold as a safe haven, have spurred gold miners’ stocks recently.

The gold and silver index , which comprises major U.S. and Canadian gold mining stocks, has more than doubled over the last four months. Spot gold was selling for $978.80 per ounce in New York on Thursday, closing in on its all-time high of $1,030.80 from last March 17.

“At these levels, we’d encourage new investors to begin by buying a little Newmont,” Bridges wrote, after Newmont Mining Corp (NEM.N: Quote), the world’s No. 2 gold producer, reported better- than-expected fourth quarter results.

Since most major gold players no longer hedge production, they stand to gain from the recent run-up in gold prices.

Nichols touts Barrick and its Canadian peer, Goldcorp Inc (G.TO: Quote). “In general, I like Barrick and Goldcorp because they are well managed, with management you can trust, providing a good return on investment.”

Credit Suisse analyst David Gagliano saw Newmont as an attractive investment after its solid fourth-quarter results.

“Newmont is entering the sweet spot,” he wrote in a research note noting higher production, lower costs and lower capital expenditures due to the proposed start-up of Boddington, which will be Australia’s biggest gold mine.

“Add to this the favorable gold backdrop and declining raw material costs, and we believe Newmont is set up nicely for a strong 2009,” wrote Gagliano.

Peter Spina, who operates Goldseek.com, a website for investors, said now is the time to invest in gold miners.

“I think mining companies are looking a lot better,” he said. “With costs down, the profit margins are expanding and people are saying: ‘Where should I invest in this market?’ The gold mining companies are the place to be.”

Spina noted that capital markets appear to be opening up.

“We are now seeing more competition for capital where three months ago it was impossible,” he added.

Spina likes the junior players, such as Denver-based Gold Resource Corp (GORO.OB: Quote), which is developing projects in Mexico.

Genuity analyst Tony Lesiak expects larger gold players to swoop in on some of the smaller miners.

“Merger and acquisition activity in the gold sector could be poised to accelerate,” Lesiak said.

He cited the improved outlook for precious metals, the disconnect between larger companies and cash-starved juniors, and a paucity of internally available quality growth projects.

Ian Nakamoto, director of research at MacDougall, MacDougall & MacTier, favored unhedged miners.

“Most producers have an unhedged book, but rising production, such as at Goldcorp and Kinross (Gold Corp (KGC.N: Quote)(K.TO: Quote,) are what come to mind,” he said.

(Reporting by Steve James, Euan Rocha and Frank Tang in New York and Cameron French in Toronto; Editing by Andre Grenon)

© Thomson Reuters 2008. All rights reserved.

==========================

In a previous post I gave you a partial list of Tier 1, Tier 2, and Tier 3 mining companies and their websites. Then in another post I gave you questions you should ask when you are doing your due diligence before making any investment in the stocks of these companies and those mentioned in today’s post. Clicks on the links to view.- jschulmansr

Catch the New Bull! – Buy Gold Online – Get 1 gram free just for opening account!, no minimums – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

=================================

Gold Sector: Mergers and Acquisitions Set to Soar – Seeking Alpha

Source: FP Trading Desk

The gold sector could see a flurry of takeover activity in the coming months, according to Genuity Capital Markets analysts Tony Lesiak, Christine Healy and Michael Gray. With that backdrop, they have broken down a number of potential targets.
They believe that 2009 could be a big year for gold M&A for a number of reasons: rising bullion prices, the growing valuation disconnect between juniors and seniors, recent financings by the seniors, and a shortage of internal growth projects for the seniors.
So who could get bought? The analysts ranked 10 junior gold producers and 20 junior development companies on the unusual measure of estimated total acquisition cost per attributable, recoverable ounce.


On that basis, the top three producer targets are Allied Nevada Gold Corp., Mineral Deposits Ltd., and Kirkland Lake Gold Inc. (KGLIF.PK), while the top junior development targets are Andean Resources Ltd. (ANDPF.PK), Colossus Minerals Inc. (CSIMF.PK), Comaplex Minerals Corp. (CXMLF.PK), Gabriel Resources Ltd. (GBRRF.PK), and Osisko Mining Corp. (OSKFF.PK).


“We recommend a basket approach to investing in any of these names given the speculative and single-asset nature of the companies,” they wrote in a note to clients.

With the exception of Gabriel, these are all companies that are often considered takeover targets. Gabriel has problems with NGO opposition in Europe, but the analysts figure that if the company can ever get government approval for its Rosia Montana project, it would be a logical target for Newmont Mining Corp. (NEM).

The most likely North American buyers in this market include Newmont, Barrick Gold Corp. (ABX), Kinross Gold Corp. (KGC), Eldorado Gold Corp. (EGO), and Alamos Gold Inc. (AGIGF.PK), they wrote.

========================================

Decoding What Gold is Telling Us – Seeking Alpha

By: Simit Patel of Informed Trades.com

Well, gold bugs around the world have been having a good chuckle of late, as the market is re-affirming the often eccentric and practically religious views of gold bugs: gold is up over 11% for the year in US dollars, and up over 4% over just the past five trading days. Which begs the question: why? There are a few possible answers to this question:

1. Deflation. This crisis is global, and everyone is flying to safe stores of wealth. Over the big picture of human history, gold has served as the best store of wealth — and thus gold is rising. In many ways this is the classic “gold is money” argument, one typically championed by Austrian economists. Robert Blumen has offered an excellent explanation of this argument.

2. Inflation. Gold is typically a hedge against inflation concerns, and as the US federal government continues to aggressively “stimulate” the economy, the rally in gold may be a reflection of increased concerns regarding inflation.

So which one is it?

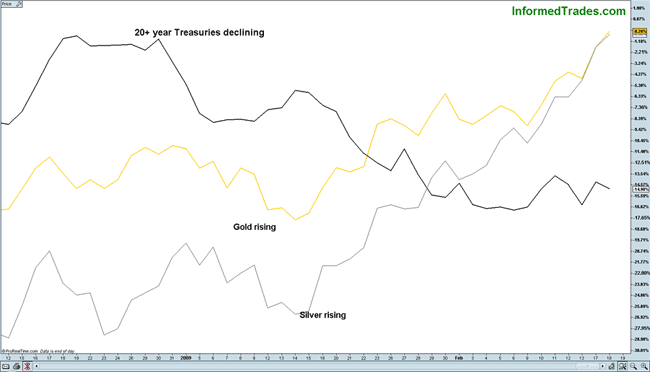
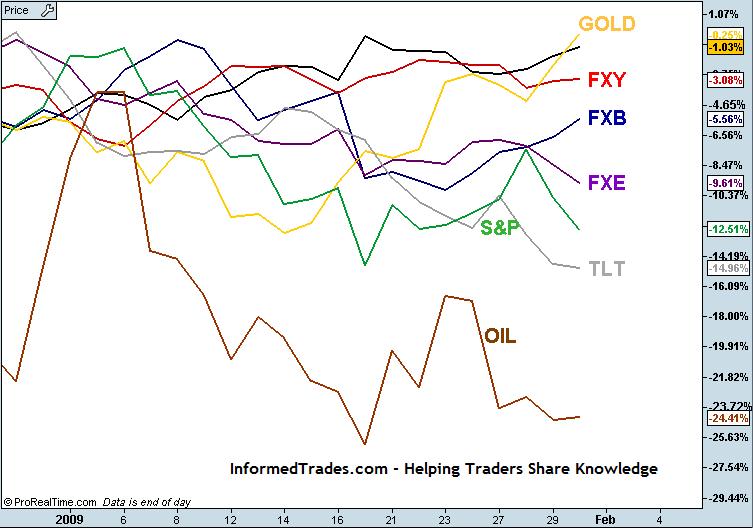
In my opinion, both. With that said, I view inflation as the larger concern, as I have said many times before. If the environment were truly deflationary, Treasury bonds would be the true recipients of flight to quality, as well as dollar holdings in FDIC insured banks. Instead, 20+ year Treasury bonds have fallen by more than 13% thus far (as measured by TLT). Negative correlation between TLT and precious metals suggests inflation, not deflation. The chart below illustrates.

click to enlarge

Deflationists will point to the fact that the US dollar may be strengthening relative to other fiat currencies — although this is not necessarily a reflection of deflation, as it could simply be interpreted as weakness of all global currencies, all of which are falling against gold. More relevant may be the rise in PPI and energy prices in January of 2009. While one month alone does not provide sufficient evidence for a substantive reversal in macroeconomic trends, it is not consistent with deflation, and may suggest that the Fed’s inflationary actions in the second half of 2008 may be kicking in.

Conclusions for Trading

The recent activity in the market has led me to make the following revisions:

1. The forex market is increasingly a trader’s environment, perhaps even a daytrader’s environment.

2. Gold and silver may retrace, perhaps even by several hundred dollars, though I would view it as an opportunity to buy on dips. The global economy is getting worse and conditions are being aggravated by the actions of central bankers. As a result, the fundamental case for gold and silver will get stronger.

3. Counterparty risk is rising — this strengthens the argument for increasing the physical delivery portion of one’s precious metals portfolio.

4. Because of inflation concerns, my bias is against short positions in all asset classes. If I were a trader of stocks or commodities, I might look into shorting positions relative to a broader index (i.e. short a particular stock while going long the sector ETF, under the rationale that the stock will do worse than the entire sector).

5. Oil’s behavior has been quite peculiar; I’ve yet to find a convincing explanation for why it’s moving the way it is. As it escapes my fundamental analysis, and as I find it less appealing than currencies from a technical analysis perspective, I’ll stay away from oil.

6. As gold becomes too expensive for many, silver will grow in appeal. And as silver fell more than gold during the second half of 2008, it may be set for a larger rally.

Disclosure: Long gold and silver.


========================================

Short Stories: Anglo American, Rio Tinto, Xstrata, Alcoa – Seeking Alpha

By: Jessica Johnson of Short Stories

Anglo American (AAUK), the mining and natural resource company, presents its results today and according to the Financial Times, its CEO, Cynthia Carroll, may face some tough questions. Falling platinum, diamond and copper prices have taken their toll on Anglo’s profit margins, and analysts will be looking for signs of progress from Ms. Carroll’s cost-cutting drive.
As you can see from this graph of Anglo’s shares outstanding on loan (%SOOL), there has been a recent increase in the short position of the stock, which, over the last ten weeks, is up from 1% to 2.2%. However, this is still a small percentage, compared to Xstrata (XSRAF.PK) (for example), which has just under 10% of its SOOL. Xstrata and Anglo’s other rival Rio Tinto [RIO/LSE] (RTP) have recently used a rights issue and a cash injection from China to shore up their balance sheets, whereas Anglo has manageable debt levels. RIO currently has 1.5% SOOL, which is up from 0.7% in January and down from 2.7% in December.


Anglo American:

click to enlarge

Anglo American

Xstrata:

click to enlarge

Xta

Rio Tinto (UK Listing)

click to enlarge

Rio plc

The S&P 500-listed stock Alcoa Inc. (AA), which produces aluminum (partly through the mining industry), has seen a rise in its %SOOL. It is up from 2% in October, but down from 8% ten days ago and currently stands at to 6%. This is in line with a fall in its share price, which over the last six months has fallen from $30 to $7. A particularly severe fall in price occurred between September and October when the stock fell from $30 to $10. Since that time, short investors have continued to take profits as the price ebbs around the $10 mark.

click to enlarge

Alcoa

Disclosure: None

=======================

My Note: With the exception of Alcoa, I think some of these Short traders are going to lose their shirts especially as Gold continues it’s Bull Stampede!- jschulmansr

Catch the New Bull! – Buy Gold Online – Get 1 gram free just for opening account!, no minimums – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

============================

Third time lucky for gold – the ultimate money? – MineWeb 


Dow Jones Industrial Average
S&P 500 Index

$INDU 7,336.68, -129.27, -1.7%) off more than 100 points, or 1.5%, at 7,357, and the broad S&P 500 index ($SPX: $SPX 764.48, -14.46, -1.9%) down 10 points, or 1.4%, at 768.

METALS STOCKS

Gold tops $1,000 for first time in nearly a year!

Share this:

  • Share on Reddit (Opens in new window) Reddit
  • Share on Facebook (Opens in new window) Facebook
  • Share on LinkedIn (Opens in new window) LinkedIn
  • More
  • Share on X (Opens in new window) X
  • Share on Pinterest (Opens in new window) Pinterest
  • Share on Tumblr (Opens in new window) Tumblr
  • Print (Opens in new window) Print
  • Email a link to a friend (Opens in new window) Email
Like Loading...

Need A Second Chance?

19 Thursday Feb 2009

Posted by jschulmansr in 10 year Treasuries, 20 yr Treasuries, Bailout News, banking crisis, bull market, capitalism, China, Comex, commodities, Copper, Credit Default, Currencies, currency, Currency and Currencies, deflation, depression, DGP, dollar denominated, dollar denominated investments, economic, Economic Recovery, economic trends, economy, Fed Fund Rate, Federal Deficit, federal reserve, Finance, financial, Forex, Fundamental Analysis, futures markets, gata, GDX, GLD, gold, Gold Bullion, Gold Investments, gold miners, hard assets, How To Invest, How To Make Money, hyper-inflation, IAU, IMF, India, inflation, Investing, investments, Iran, Israel, Jschulmansr, Junior Gold Miners, Keith Fitz-Gerald, Latest News, majors, Make Money Investing, market crash, Markets, mid-tier, mining companies, mining stocks, palladium, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, recession, risk, silver, silver miners, spot, spot price, stagflation, Stimulus, Stocks, TARP, Technical Analysis, The Fed, Tier 1, Tier 2, Tier 3, Today, U.S., U.S. Dollar, volatility

≈ Comments Off on Need A Second Chance?

Tags

ANV, Austrian school, AUY, Bailout News, banking crisis, banks, bear market, Bollinger Bands Saudi Arabia, Brian Tang, bull market, CDE, central banks, China, Comex, commodities, Copper, Currencies, currency, deflation, Dennis Gartman, depression, DGP, dollar denominated, dollar denominated investments, Doug Casey, economic, economic trends, economy, EGO, Federal Deficit, financial, Forex, FRG, futures, futures markets, gata, GDX, GG, GLD, gold, gold miners, hard assets, HL, hyper-inflation, IAU, India, inflation, investments, Jeffrey Nichols, Jim Rogers, Keith Fitz-Gerald, majors, Marc Faber, market crash, Markets, Michael Zielinski, mid-tier, mining companies, monetization, Moving Averages, NGC, NXG, PAL, palladium, Peter Grandich, Peter Schiff, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, protection, recession, risk, run on banks, safety, Sean Rakhimov, silver, silver miners, SLW, small caps, sovereign, spot, spot price, stagflation, Technical Analysis, TIPS, U.S., U.S. Dollar, volatility, warrants, XAU

Gold today is trading on Feb Contract between $975 – $985 oz, a little more consolidation and base building before the launch to $1000+.  Currently Gold is up $3.80 at $982.00. The push to $1000 could come as early as today. Do you need a second chance? Well here it is- get into Gold now or you’ll be kicking yourself later.  If Gold breaks the $1003 all time high then we’ll see at least $1050 gold, if it breaks that we have a straight shot to $1100 – $1250. This is without any major news, such as Israel attacking Iran nuclear facilities, or China moving in and taking back the disputed territories in India, or a major terrorist attack event like 911. If any of those happen then $1500 or greater. True Inflation Rate while still roughly 7-8% could easily jump to 12 – 18% or higher, as the printing presses around the world are spinning out of control around the world. This eventually will lead to even more devaluation of all the currencies as Governments are madly trying to stop Deflation. The Gold market is saying the stimulus packages around the world are failing. Buy a wheelbarrow to haul your cash around and Gold to preserve the buying power of your Dollars. Even if you only allocate 10% of your portfolio- BUY GOLD NOW! As Always Good Investing – jschulmansr

Here is where I buy my Bullion, get one free gram of Gold just for opening an account! Catch the New Bull! – Buy Gold Online – Get 1 gram free just for opening account!, no minimums – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

==========================================

Gold Continues to Climb as Economic Catastrophe Looms – Seeking Alpha

By: John Browne of Euro Pacific Capital


Last week, when Congress passed its $787 billion stimulus package, the size of the plan caused many observers to forget the water that has already passed under the bridge. Fewer still are wondering what havoc will erupt when all this liquidity eventually washes ashore.


With gold prices only 7% away from their record highs and the main equity indices 45-50% below their highs, an analysis of the equity/gold ratio is amid the many rationalizations for prolonged gains in the precious metal. The equity/gold ratio highlights a commonly used measure of corporate market value versus a decades-long measure of real asset value. Gold is known as a measure of real assets value because of its ability to preserve value during inflationary times. But during these disinflationary times, the current global growth/demand landscape also supports the notion of too many dollars chasing too few gold ounces.


The questions can be separated into three general topics: Corporate, Projects, and Capital.


  • How did the company get started?
  • What are the company’s near-term, mid-term, and long-term goals?
  • How much experience does the management, board of directors, and technical team have in achieving the company’s goals? Is there a past history of success?
  • How does management plan to market and promote the company? Does the company plan to go on road shows? Do they plan to do newsletter, magazine, or website advertising?
  • How much of experience does management have in promotion?

Projects

  • How many gold projects does the company have? Are all of the gold projects considered assets?
  • Where are they located? Are they located in geopolitically safe regions? Are they easily accessible? Is there a labor force nearby? Is there easy access to power and water?
  • What stage is each property in: Grassroots? Exploration? Development? Production?
  • For grassroots stage projects, why does the company wish to pursue exploration? Has there been any historic evidence of gold on or near the projects? What does the company have planned for the future of its grassroots projects?
  • For exploration stage projects, what kind of exploration progress have been made so far? How much has the company drilled? What have been the results? What kind of exploration is planned for the future? Is there currently a resource estimate? Will there be one in the future?
  • For development stage projects, what is the status of development? When will the project become a gold producing mine?
  • For production stage projects, how much gold does the mine produce? What are the future production and revenue expectations? How long is the life of the mine?
  • What is the resource or reserve status of each property?
  • What, if any, royalties are or will be due?

Capital

  • What is the company’s cash flow, if any?
  • What is the company’s cash position?
  • Does the company have any debt? How much and what kind of debt does the company have?
  • Will the company need to raise new capital for future projects? How much money will the company need to raise? How much experience does management have in raising new capital?
  • How much capital will the company need to reach its 12-month goals? How will they get the money?
  • What is the company’s monthly burn rate? Are they being responsible spending it?
  • How many shares of the company’s stock are issued and outstanding?
  • How many shares of the company’s stock are there fully diluted? At what price are the warrants and options set?

This is not a stock-specific list, so these questions are best used as a guideline to form your own questions for investor relations.

This is also not a complete list, but should definitely be enough to get you started. If you like a company’s answers to the questions above, it should be more seriously considered as a position in your junior gold stock portfolio.

Good Investing,

Luke Burgess and the Gold World Staff

P.S. The opportunities in the gold market have already proven to be huge winners for readers of our Mining Speculator advisory service. As a matter of fact, for five years running the Mining Speculator portfolio had an average gain of 212%! Most of these gains can be attributed to Greg McCoach’s expertise in picking junior gold mining stocks, which, as we’ve just discussed, are getting ready to explode. And we’re expecting even bigger gains from the gold mining stocks in the Mining Speculator portfolio over the next 24 months. That means there’s never been a better time to become a member of Mining Speculator and get in on the tips and information for which some people invest millions of dollars with hedge funds. Click here to find out how you can join us in the Mining Speculator for as little as $25.  

========================================

EGO: A Particularly Healthy Gold Stock – Hard Assets Investor

By: Brad Zigler of Hard Assets Investor

Real-time Inflation Indicator (per annum): 7.5%

We wrote about gold stocks last week (“Whither Gold Stocks”) , waving a $38 red cape for the Market Vectors Gold Miners ETF (NYSE Arca: GDX) in front of a four-month-old bull market. Yesterday, as gold picked up $10, GDX’s horns got close. Very close.

 Intraday, the ETF traded as high as $37.80 before falling back to close at $37. The fund is working itself into the target area nicely, thankyewverymuch. One of GDX’s better-performing component stocks, in fact, might be a herald of the fund’s future.

 El Dorado Gold Corp. (NYSE Alternext: EGO) has risen 11.4% this year, just barely ahead of the 9.2% gain posted by GDX. Oh sure, a 2.2% performance difference may seem significant now, but given the relatively low volatility in both securities, the spread seems unlikely to widen much. Barring something unforeseen, of course.


Gold Miners ETF (GDX vs. El Dorado Gold (EGO)

 GDX Graph

The good news for EGO and, indirectly, GDX, is EGO’s cost structure. For fiscal 2008, EGO’s cash cost of gold is only $257 an ounce. Volatility in bullion prices is least likely to impact EGO,  compared to its peers.

E-G-O could spell peerless performance for GDX. 

=====================================

My Disclosure: Long EGO (El Dorado Gold)- jschulmansr

===============================

Gold Breaks from Traditional Trading Versus Oil and USD, Looks Strong – Seeking Alpha

Source: Financial Post Trading Desk

Safe haven demand and a lack of investment alternatives continues to help gold break from its traditional trading relationships, rising despite a strong U.S. dollar and weak crude oil prices. In fact, analysts at Genuity Capital noted that gold is more than $200 per ounce above its normal value relative to the greenback.

Meanwhile, sustained investor interest in gold throughout 2008 helped push dollar demand for bullion to $102-billion, a 29% annual increase, according to World Gold Council’s Gold Demand Trends. The organization also said identifiable investment demand for gold, which incorporates exchange traded funds (ETFs), bars and coins, rose 64% last year. This is equivalent to an additional inflow of $15-billion.

Genuity also pointed out that the opportunity cost of holding bullion has diminished, with treasury yields at record lows and demand fundamentals deteriorating in the broader commodity and equity markets.

Concerns about the stability of the global banking system and credit rating of the U.S. Treasury has been a major driver of physical demand for gold. Until clear evidence of stabilization in the global financial system emerges, analysts at Genuity expect this trend to continue.

“If the U.S. dollar weakening resumes in the medium term, as we believe it shall, and oil prices improve, gold should continue to prosper,” they said in a research note. As a result, Genuity continue to recommend gold over base metals in the near term.

Aram Shishmanian, CEO of World Gold Council, said:

The economic downturn and uncertainty in the global markets, that has affected us all, is unlikely to abate in the short term. Consequently, I anticipate that gold, as a unique asset class, will continue to play a vital role in providing stability to both household and professional investors around the world.

North American gold equities have risen more than twice as much as gold itself in the past month, showing stronger than typical leverage. Silver has also begun to outperform.

Genuity highlighted Silver Wheaton Corp. (SLW) was a name that provides leverage to the metal and has the potential for a re-rating.

The firm’s top gold picks in the intermediate space are Allied Nevada Gold Corp. (ANV), IAMGOLD Corp. (IAG) and Northgate Minerals Corp. (NXG). It also favours seniors Goldcorp Inc. (GG) and Yamana Gold Inc. (AUY). The firm also raised its target prices for gold stocks by an average of 28% to reflect higher price assumptions for the metal.

Genuity said:

While our target multiples are now mainly near the top of the typical valuation range (1.0x to 1.7x), we believe that continuing positive momentum in the gold price should support further outperformance from the gold equities.

With the arrival of fourth quarter and year-end earnings season, one area of reporting that will see additional focus is the updates on gold reserves.

RBC Capital Markets expects gold producers to increase the gold price assumption used to calculate reserves from the previous range of $550-$575 per ounce to $675-$725. This will better match the three-year historical gold price as suggested for use by the SEC.

“With this increase, we expect most producers should be able to more than replace gold reserves mined during 2008, and show net gains from the end of 2007,” RBC analysts told clients.

===========================================

My Disclosure: Long AUY, NXG, SLW – jschulmansr

Need a Second Chance? – Well Here It Is – Buy Gold and Invest In Yourself…

Good Trading! -jschulmansr

Catch the New Bull! – Buy Gold Online – Get 1 gram free just for opening account!, no minimums – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

=====================================


Nothing in today’s post should be considered as an offer to buy or sell any securities or other investments; it is presented for informational purposes only. As a good investor, consult your Investment Advisor/s, Do Your Due Diligence, Read All Prospectus/s and related information carefully before you make any investing decisions and/or investments. –  jschulmansr


Gold prices are quickly on their way to breaking another all-time high this year.


“uhhh…yeah…sure….this is investor relations” 

In whatever form you find investor relations, they should be able to give you all of the most up-to-date information. Or they should at least be able to tell you where to find any information they don’t have.

To help you get the most out of speaking to investor relations of junior gold companies, Gold World has made a basic list of questions that you should be sure ask.

And an expected parabolic rise in investment demand will throw the gold bull market into the long-awaited mania buying phase, which should last between 6 and 12 months and could push gold prices as high as $3,000 to $5,000 an ounce, maybe higher.

That means right now is the time to start seriously researching and buying back all those quality junior gold stocks that have collapsed over the past few months.

How To Pick the Right Junior Gold Stocks

The best place to start research on a company is its website. There, you’ll generally find most of the information that you need. However, more often than not, you won’t be able to find all of the detailed information. And that’s when you need to call the company’s investor relations department.

Investor relations for junior gold companies are sometimes one or two in-house employees of the company. Other times investor relations is contracted out to a third party. Or sometimes it will be a member of management. And sometimes there is no formal investor relations at all; sometimes investor relations is just whoever picks up the phone…


Corporate


click to enlarge


The equity/gold ratio (using the Dow or S&P500) has fallen about 85% from its 1999 peak, which occurred when gold stood at 20-year lows and equities reached their highs at the top of the dot-com bubble. Since the 1920s, the equity/gold ratio has peaked twice at nearly 35-year intervals: 1929 to 1965, and 1965 to 1999. After each of those three peaks, stocks descended in multiyear sell-offs, accompanied by a rally in gold. But the converse was not true when stocks recovered in 2003-2007. As the above chart shows, the 2002-3 start of the commodity-wide bull market failed to prevent the equity/gold rally from extending its decline.

The 100 years of equity/gold analysis indicate each peak in the ratio was followed by a full retracement back to the preceding lows. The emerging fundamentals indicate a recurrence of this trend and the equity/gold ratio has further declines ahead until a possible recapture of the 1980 lows. In 2002-2007, the falling ratio emerged on a rally in both equities and gold, albeit a faster appreciation in the latter. From 2008 to the present, the persistent decline in the ratio emerged on a combination of a divergence in the pace of declines (slower fall in gold than in equity indices) or divergence in the direction (rising gold and falling/neutral equities).

In assessing the interaction between gold and monetary assets, it is worth weighing in on the current gold rally by comparing the amount of gold available versus the creation of monetary assets. Just as the equity/gold ratio stands at 18-year lows, the ratio of total financial assets to physical gold is near the low end of its historical range. Additionally, The world’s available gold stock stands at a mere 5-6% of total global stock and bond market valuation, which is about 4 times lower than in the 1980s. It is no coincidence that the difference between today’s gold/equity ratio and that of the 1980 low was also 6 times greater.

The Road Ahead

A return in the equity/gold ratio towards the cyclical lows of 1980 is highly plausible. Rather than simply arguing this point on the basis of further declines in equities (see Tuesday’s note in my website on long term equity cycles), the prospects for prolonged gold rallies are emboldened by the refuge towards the metal as a yield substitute resulting from emerging depreciation in the secular value of currencies. And as we have seen in 2005-7, returning rate hikes pose no challenge to gold.

Instead, higher rates are accompanied by improved global growth, resurging demand for industrial commodities and a broader backdrop for the precious metal. The all time lows of 1980 in the Dow/gold and S&P500/gold ratios stood at 1.33 and 0.18 respectively, compared to the current levels of 7.8 and 0.81. Assuming a return in the ratios to their 1980 lows, these would have to fall by another 75%-80%. Taking a more conservative scenario of a 50% decline in the equity/gold ratio and a target gold price of $1,250-1,300/ounce, the implied value of the Dow and the S&P500 would stand at 4,500-5000 and 500-520 respectively.

=====================================

How To Pick Junior Gold Stocks – GoldWorld

Source: GoldWorld.com


The latest spending, signed into law yesterday by President Obama, came on top of $300 billion committed to Citigroup (C), $700 billion for TARP 1, $300 billion for the FHA, $200 billion for TAF and some $300 billion for Fannie (FNM) and Freddy (FRE). Just over the last six months, which excludes the initial Bush stimulus and several massive, unfunded Federal guarantees, nearly $5 trillion has been committed by the government to the financial industry. Rational observers cannot be faulted for concluding, despite Administration claims to the contrary, that the government is merely throwing money at the problem.

Although the rhetoric has managed to convince many observers of the possibility of success, the gold market appears to clearly understand the implications of this unprecedented spending.

The feeling that the government has no idea how to proceed has created palpable panic. In response, pragmatic investors are seeking the ultimate store of wealth. In 2009, as has occurred countless times throughout history, that store will be stocked with gold. Thus, whether the Federal government’s interventions will succeed or fail will be anticipated by the price of gold. Right now, the market is screaming failure.

Prior to the latest round of Federal spending, the Federal government had committed $4 trillion to postpone bank collapses and to lay the groundwork for subsequent restructuring. But has any of this activity actually rescued the banking system? In light of the evidence of deepening recession, is it likely that the additional $787 billion in the latest stimulus will instill enough confidence to restore economic growth? If not, what damage will it do to the eventual recovery?

Congressional rescue packages rarely work. Nevertheless, Congress is turning up the heat with previously unimaginable increases of government debt to fund stimulus and rescue packages. Senator McCain rightly describes the scheme as “generational theft”. Each package of debt will encumber many future generations, halt restructuring and also threaten latent hyperinflation.

While Congress claims that the seriously over-leveraged economy is in desperate need of restructuring, it appears blind to the fact that deleveraging will encourage such restructuring. Instead, Congressional leaders actively seek to increase leverage and add debt. They warn of fire, while pouring petrol on the flames.

The seriousness of the situation is magnified by the rapidly increasing scale of the problem. Just today, the release of the latest minutes of the Federal Reserve confirmed that even that bastion of eternal optimism is sobering. The American economy, which shrank by 3.8 percent in the last quarter of 2008, is forecast to decline by some 5.5 percent in the first quarter of this year. In some pockets, the unemployment rate is already in double figures. Despite massive Government spending on rescue and stimulus, the American consumer clearly is becoming increasingly nervous, and the credit markets show few signs of recovery.

With bad news only getting worse, investment markets are turning into quagmires. The Dow Jones Average is testing new lows, and the commodities markets show few signs of life. In such times, the price of gold should fall along with the prices of other assets and commodities. But, the reverse has occurred. In the past two months, gold has staged a remarkable rally. This is despite the activity of price-depressants such as official gold sales by the IMF and official ‘approval’ for massive naked short positions to be opened by new ‘bullion’ banks.

Not only have gold spot prices risen in the face of such selling pressure, but the price of physical gold is now some $20 to $40 per ounce above spot. This would indicate that investors are now so nervous that they are insisting on taking physical delivery.

Make no mistake, the economy will not turn around soon. When the recovery fails to materialize, look for governments around the world, and especially in the U.S., to send another massive wave of liquidity downriver. When it does, the value of nearly everything, except for gold, will diminish. Don’t be intimidated by the recent spike in gold. Buy now while you still can.

======================================

As I have been saying Buy Gold Now! – jschulmansr

Catch the New Bull! – Buy Gold Online – Get 1 gram free just for opening account!, no minimums – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

=====================================

Equity / Gold Ratio’s 40 Year Cycle – Seeking Alpha

By: Ashraf Laidi of AshrafLaidi.com

Share this:

  • Share on Reddit (Opens in new window) Reddit
  • Share on Facebook (Opens in new window) Facebook
  • Share on LinkedIn (Opens in new window) LinkedIn
  • More
  • Share on X (Opens in new window) X
  • Share on Pinterest (Opens in new window) Pinterest
  • Share on Tumblr (Opens in new window) Tumblr
  • Print (Opens in new window) Print
  • Email a link to a friend (Opens in new window) Email
Like Loading...

Twitter and Tweeting – The Basics plus Gold Update

18 Wednesday Feb 2009

Posted by jschulmansr in Bailout News, banking crisis, bull market, Comex, commodities, Copper, Currencies, currency, Currency and Currencies, DGP, dollar denominated, dollar denominated investments, economic, Economic Recovery, economic trends, economy, Finance, financial, Forex, futures markets, GDX, GLD, gold, Gold Bullion, Gold Investments, gold miners, hard assets, How To Invest, How To Make Money, IAU, inflation, Investing, investments, Junior Gold Miners, Latest News, majors, Make Money Investing, market crash, Markets, mid-tier, mining companies, mining stocks, palladium, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, recession, resistance, risk, run on banks, silver, silver miners, spot, spot price, stagflation, Stimulus, Stocks, TARP, Technical Analysis, The Fed, Tier 1, Tier 2, Tier 3, TIPS, Today, Tweeting, Twitter, U.S. Dollar, XAU

≈ Comments Off on Twitter and Tweeting – The Basics plus Gold Update

Tags

#(subject), @replies, advertising, appscout, ask for help, Austrian school, Bailout News, banking crisis, banks, bear market, Bollinger Bands Saudi Arabia, Brian Tang, bull market, categorize your tweets, cell phone, central banks, China, Comex, commodities, Copper, Currencies, currency, deflation, Dennis Gartman, depression, desktop client, DGP, direct-messaging, dollar denominated, dollar denominated investments, Doug Casey, economic, economic trends, economy, Federal Deficit, financial, follow the news, Forex, futures, futures markets, gata, GDX, gearlog, GLD, gold, gold miners, hard assets, how to use twitter, hyper-inflation, IAU, India, inflation, investments, Jeffrey Nichols, Jim Rogers, Keith Fitz-Gerald, majors, Marc Faber, market crash, Markets, Michael Zielinski, mid-tier, mining companies, mobile client, monetization, Moving Averages, palladium, pcmag, Peter Grandich, Peter Schiff, physical gold, platinum, platinum miners, pockettweets, pr, precious metals, price, price manipulation, prices, producers, production, promote, promotion, protection, recession, risk, RT, run on banks, safety, Sean Rakhimov, search, search twitter, search.twitter.com, silver, silver miners, small caps, sovereign, spot, spot price, stagflation, tag, tag and search, Technical Analysis, text message, tiny url, TIPS, tricks, tweet from your phone, tweetdeck, Tweeting, tweets, twhirl, twidroid, twitpic, Twitter, twitter for beginners, twitterberry, TwitterFox, twitterific, twitterverse, U.S., U.S. Dollar, use @, volatility, warrants, XAU

Have you ever Tweeted? In this Special Edition of Dare Something Worthy Today Too!, In this special edition I am including articles dedicated to Twitter and Tweeting Basics. In my earlier post today I stated Gold was consolidating for another thrust to test the All Time High of $1003 an oz. Gold was trading around the $965 level. Now checkout what happened… – Good Investing and Good Tweeting! -jschulmansr

ps-after today’s action it seems like every “forecaster” is now finally heralding a “New” Bull market in Gold. How much money do these guys charge? If you have been following this blog and my notes you would be up $150+ oz in Physical Gold, not to mention some excellent gains in Gold Stocks too, and for Free! Remember you heard it here first! – jschulmansr

============================

Gold tops $980 as safety buying continues – MarketWatch

Source: MarketWatch

METALS STOCKS

Gold up for second day as safety

buying continues

By Moming Zhou, MarketWatch
Last update: 2:24 p.m. EST Feb. 18, 2009
 
NEW YORK (MarketWatch) — Gold futures rose Wednesday for a second session, ending at the highest level in seven months after briefly hitting $980 an ounce, as safe-haven buying continued.
 
 
Meanwhile, holdings in the biggest gold exchange-traded fund surpassed 1,000 tons for the first time ever, according to latest data.
 
Gold for February delivery ended up $10.70, or 1.1%, at $977.70 an ounce on the Comex division of the New York Mercantile Exchange, the highest closing level for a front-month contract since July 15, when gold closed at the same price.
 
The February contract, which expires on Feb. 25, rose to $980.80 earlier. Trading more actively, the April contract also ended higher at $978.20.
Gold is now about $26 below its all-time high above $1,003 an ounce, hit in March 2008. Talk of “gunning for the $1,000 level” should keep buyers at the helm, said Jon Nadler, senior analyst at Kitco Bullion Dealers.
 
Helping gold prices hold firm Wednesday was more gloomy news from the U.S. economy.
 
Construction on new U.S. housing units plunged 16.8% to a seasonally adjusted annual rate of 466,000, the Commerce Department reported Wednesday, with housing starts now far below the weakest levels of construction in the post-World War II era.
 
Such news tends to boost gold prices, as some investors buy the metal as a safe haven against economic troubles.
 
Meanwhile, the Obama administration released details Wednesday of a program to help millions of at-risk homeowners modify their mortgages. See full story on Obama housing plan.
 
Demand surpasses $100 billion
 
Demand for gold surpassed $100 billion last year for the first time ever, amid increased industrial and jewelry consumption and investors’ purchase of the metal as a safe haven, the World Gold Council reported Wednesday.
 
Gold demand — including jewelry consumption, industrial demand and identifiable investments such as bars, coins and gold exchange-traded funds — hit $102 billion in 2008, up 29% from a year ago.
In tonnage terms, gold demand rose 4% to 3,659 tons, the WGC said
Gold holdings in SPDR Gold Shares, the largest gold exchange-traded fund, rose to 1,008.80 tons Tuesday, surpassing the 1,000 ton level for the first time, according to latest data from the fund. The total was up more than 200 tons from a month ago.
 
The SPDR Gold Trust GLD 96.44, +0.99, +1.0%) gained 1.1% to $96.45.
 
In spot trading, the London afternoon gold-fixing price — a benchmark for gold traded directly between big institutions — stood at $964 an ounce Wednesday, down $4 from the previous day.
 
Other metals, equities
 
In other metals trading, March copper rose 1% to $1.436 a pound, while March silver gained 2% to $14.29 an ounce.
March palladium added 0.5% to $219.10 an ounce, and the April contract for sister metal platinum rose slightly to $1,098.90 an ounce.
 
In equities, shares of Barrick Gold Corp. (ABX 37.88, +0.59, +1.6%) , the world’s largest gold-mining company, added 2.2% to $38.13, while Goldcorp Inc. (GG 32.14, +0.30, +0.9%) gained 1.6% to $32.36, and South Africa’s Gold Fields Ltd. (GFI 11.79, -0.04, -0.3%) was up 0.3% to $11.85.
 
The Amex Gold Bugs Index (HUI 320.54, +1.35, +0.4%) , which tracks the share prices of major gold companies, gained 0.7% to 321.41.
 
The iShares Gold Trust ETF (IAU 96.48, +0.94, +1.0%) rose 1% to $96.50, while the iShares Silver Trust ETF (SLV 14.20, +0.21, +1.5%) rose 1.4% to $14.18. End of Story
 
Moming Zhou is a MarketWatch reporter based in New York.
=========================

Catch the New Bull! – Buy Gold Online – Get 1 gram free just for opening account!, no minimums – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

================================

 
Twitter and Tweeting – The Basics
 
Top 10 Twitter Tips for Beginners – PC Magazine
 
 by Sean Ludwig
 
Ready to jump into Twitter, but don’t know how to get started? Follow these 10 tips and you’ll fit right in.
 
Is it finally time to take the Twitter plunge? The free service that lets users micro-blog 140 characters at a time had accumulated around 1.9 million users as of December 2008, according to comScore. If you are just now jumping on the Twitter bandwagon, or are intimidated by your inexperience with Twitter etiquette and acronyms, allow us to share some Twittery tips that will make your experience easier and more enjoyable.
1. Shrink Your URLs
Shrink Your URLs
 
 One of the most common uses of Twitter is sharing links. But you only have 140 characters to work with, so instead of sharing a long URL, use one of several URL-shortening services to shrink that link. Some of our favorites include tinyurl.com, is.gd, ow.ly, and bit.ly. 
2. RT = Retweet
2. RT = Retweet
If you want to copy and paste someone else’s tweet, that’s totally accepted and appreciated, as long as you give the original tweeter credit for it. Just put “RT @name” in front of their tweet and post it yourself.
3. Direct Messaging
Direct Messaging
With Twitter’s direct-messaging (DM) function, you can send a private 140-character message to another user, kind of like abbreviated e-mail. However, you can only direct message Twitter users that are following you.
4. Use the @ Sign
Use the @ Sign
To create a reply or to give someone props on Twitter, simply place an @ sign in front of their Twitter name. If it is a reply, the @ sign must be the first character of the tweet. To see replies to your own tweets, click on @Replies from your profile page.
5. Search For Your Friends
Search For Your Friends
Search.twitter.com works well for finding your friends, celebrities, or organizations, or for searching for specific topics you’re interested in.  
6. Categorize Your Tweets for Added Visibility    
 

Categorize Your Tweets for Added Visibility
If you’re tweeting about a popular subject (Obama, Lost, etc) putting a # in front of the subject makes it easy for others to find your tweet, and perhaps they will want to follow you. For example, when the plane crashed into the Hudson River in January, #flight1549 became a popular tag and search term.
7. Share Pictures
Share Pictures
People love sharing their photos with the world, and some even break news with them, like Janis Krums, who used TwitPic to post one of the first up-close photos of Flight 1549 on his Twitter feed. Services like TwitPic let users easily upload their photos and post them directly to Twitter.
8. Tweet from Your Phone
Tweet from Your Phone
Twitter allows you to update your status and receive updates via text message. Under Settings, go to the Devices tab and enter your phone number to start sending and receiving mobile tweets. If your incoming tweets/texts are overwhelming you, disable this option by going back to the same panel and following the instructions.
9. Pick a Good Desktop Client
Pick a Good Desktop Client
With desktop clients such as TweetDeck, Twhirl, and TwitterFox, you can receive tweets in a much more manageable fashion, especially if you follow a lot of people, respond often, and use direct messages a lot. TweetDeck, for example, allows you to create specific groups, if you want to split your feed into individual columns.
10. Download a Mobile Client
Download a Mobile Client
If you have a BlackBerry, an iPhone, or another smartphone with Wi-Fi or 3G access, a mobile client might be a better option than using text messages. Mobile Twitter clients worth checking out include Twitterific, TwitterBerry, PocketTweets, and Twidroid. You can even follow PCMag on Twitter! Find us at http://twitter.com/pcmag, and follow AppScout and Gearlog too!
=======================
My Note: you can follow me on Twitter too!
http://twitter.com/jschulmansr  or click here.
=======================
Six Ways to Make Twitter Useful – PC Magazine
Source: PCMAG.com by Nick Douglas

02.17.09

Twitter’s usefulness goes far beyond finding out what strangers ate for lunch. Read breaking news, get customer service, or even chat with your favorite celebrities.

Twitter is vapid, Twitter is narcissistic—Twitter is actually terribly useful if you can ignore knee-jerk backlash. The casual, instant nature of the service lends itself to solving small problems quickly, distributing live-on-the-scene news reports, and keeping track of people. Here are six easy ways to transform Twitter from a time sink into an indispensable tool.


Follow the News

In general, the Web at large is still a more complete news source. Twitter is for keeping track of one niche you care about, staying informed on a news-heavy day, and getting live updates from Twitter users on the scene (like from an Apple keynote or a plane crash in the Hudson River). @CNN posts headlines with story links, but I prefer the one-sentence story summaries on the unofficial @cnnbrk. @NYTimes posts headlines and links too, but it also follows the accounts of 80 NYT sections and writers. Other popular news feeds include @BreakingNewsOn, @nprnews, @weirdnews, @macrumors, @MarsPhoenix, @Astronautics, and several feeds from Digg. PCMag offers a feed for tech news, as do Gearlog and AppScout. You can also hand-roll feeds from a news site’s RSS using Twitterfeed, but don’t publicize it too hard lest the site owners complain.

Get Better Customer Service

Conducting customer service on Twitter doesn’t make much sense—for the company. It just won’t scale well once Twitter gets another ten million users. But right now you can get more attention than you deserve as a single customer by talking to one of these companies on Twitter: Zappos, Starbucks, Whole Foods, JetBlue, and many, many others. Next time you have a customer complaint, just Google the search string “[Company name] Twitter” to see if you can make your case in 140 characters. Or just post a gripe about the company or product and wait for someone in the Twitterverse to respond.

Ask for Help

As with blogs and forums, Twitter is a great place to ask questions you’re too lazy to find the answers for yourself. And the service is absolutely perfect for asking favors (“Can anyone help me move on Friday?”), gathering opinions (“Do organic bananas taste better?”), or getting advice (“How much RAM should I get for my new MacBook?”) Twitter takes a problem you can solve by spending 5 minutes at a computer and makes it solvable in 10 seconds from the produce aisle. Of course, this works best when your real-life friends are following you, as developer Owen Winkler explains. Especially if you ask your followers to help you lose weight. The flip side is that Twitter communication is meant to be two-way. Build your network of followers and your Twitter karma by jumping in with answers and help of your own.

Promote Your Work/Company

Again, Twitter isn’t the first service to solve this problem; the immediacy of the service just makes it a good option. If you don’t abuse it, you can use an occasional link to promote an app you’ve built, an article you’ve written, or a longer plea for someone to please, please help you move on Friday. Just keep it to three links a week; any more and you’ll alienate followers who already know about your work or couldn’t care less.

Keep Up with Friends

Other than entertaining strangers, this is my favorite use of Twitter. One message at a time, knowing who has a cold or who got in a fender bender is dull. But in aggregate, skimming your Twitter feed gives you a sixth sense about what your social circle is up to, what moods they’re in, whether they’re free for a drink that night and whether you’d better offer to pay. Unlike the more intense location-based services, Twitter still has a built-in casualness: You’re not necessarily asking people to meet you right here right now, you’re just asking if anyone’s free for lunch.

Meet Celebrities

Not all of the most-followed Twitter users pay attention to messages from their followers, but Brent Spiner (Star Trek‘s Data) is pretty friendly, as is comedian Stephen Fry. And if you have heroes in the tech media world, you’re set for life here.

===========================

Final Note: Get involved in investing in precious metals whatever form, i.e. bullion, stocks, etf’s and etc. NOW!

I can be tweeted @jschulmansr or jschulmansr

Enjoy and Have A Great Evening! -jschulmansr

===========================

Nothing in today’s post should be considered as an offer to buy or sell any securities or other investments; it is presented for informational purposes only. As a good investor, consult your Investment Advisor/s, Do Your Due Diligence, Read All Prospectus/s and related information carefully before you make any investing decisions and/or investments. –  jschulmansr

Share this:

  • Share on Reddit (Opens in new window) Reddit
  • Share on Facebook (Opens in new window) Facebook
  • Share on LinkedIn (Opens in new window) LinkedIn
  • More
  • Share on X (Opens in new window) X
  • Share on Pinterest (Opens in new window) Pinterest
  • Share on Tumblr (Opens in new window) Tumblr
  • Print (Opens in new window) Print
  • Email a link to a friend (Opens in new window) Email
Like Loading...

Catch Me If You Can!

18 Wednesday Feb 2009

Posted by jschulmansr in 10 year Treasuries, 20 yr Treasuries, banking crisis, banks, bull market, central banks, China, Comex, commodities, Currencies, currency, Currency and Currencies, DGP, dollar denominated, dollar denominated investments, economic, Economic Recovery, economic trends, economy, Fed Fund Rate, Federal Deficit, federal reserve, Finance, financial, Forex, Fundamental Analysis, futures, futures markets, gata, GDX, GLD, gold, Gold Bullion, Gold Investments, gold miners, hard assets, How To Invest, How To Make Money, hyper-inflation, IAU, IMF, India, inflation, Investing, investments, Japan, Jschulmansr, Junior Gold Miners, Latest News, majors, Make Money Investing, market crash, Markets, mid-tier, mining companies, mining stocks, monetization, palladium, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, Saudi Arabia, silver, silver miners, spot, spot price, stagflation, Stimulus, Stocks, Technical Analysis, The Fed, Tier 1, Tier 2, Tier 3, Today, U.S., U.S. Dollar

≈ Comments Off on Catch Me If You Can!

Tags

Austrian school, Bailout News, banking crisis, banks, bear market, Bollinger Bands Saudi Arabia, Brian Tang, bull market, central banks, China, Comex, commodities, Copper, Currencies, currency, deflation, Dennis Gartman, depression, DGP, dollar denominated, dollar denominated investments, Doug Casey, economic, economic trends, economy, Federal Deficit, financial, Forex, futures, futures markets, gata, GDX, GLD, gold, gold miners, hard assets, hyper-inflation, IAU, India, inflation, investments, Jeffrey Nichols, Jim Rogers, Keith Fitz-Gerald, majors, Marc Faber, market crash, Markets, Michael Zielinski, mid-tier, mining companies, monetization, Moving Averages, palladium, Peter Grandich, Peter Schiff, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, protection, recession, risk, run on banks, safety, Sean Rakhimov, silver, silver miners, small caps, sovereign, spot, spot price, stagflation, Technical Analysis, TIPS, U.S., U.S. Dollar, volatility, warrants, XAU

As I write this Gold is taking a breather and consolidating at the $960 level, this is before I believe the next launch to test the $1000 mark+ which can easily come in the next few days. Gold is certainly saying “catch me if you can!”. Todays articles include several different vehicles with which to cash in on gold! Good Investing – jschulmansr

============================

Jschulmansr Recommended:

Here is where I buy my Bullion, get one free gram of Gold just for opening an account! Catch the New Bull! – Buy Gold Online – Get 1 gram free just for opening account!, no minimums – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

===================================

Riding the Gold and Silver Uptrend with ETF’s – Seeking Alpha

By: The Sun of The Sun’s Financial Diary

As I mentioned earlier, gold has had a tremendous run lately. The main force behind the gold rally is the deterioration of economies around world. Despite the passage of the $789 billion economic stimulus package over the weekend, gold price has continued to climb since the holiday.

Currently, spot gold is traded at $967 an ounce, up more than $10 from last Friday’s close, breaking the key $950/ounce level. That’s the seven-month high for gold. Also, major stock benchmarks are likely to test the November lows amid jitters in the financial sector.

 Even though there are predictions that gold could back fall after the stimulus plan became a law, that hasn’t happened. In contrast, investors are increasing their holdings of gold as a safe haven to preserve their wealth while the stock market continues to decline. Right now, gold is trading well above its 50- and 200-day moving averages, a clear indication of the uptrend of gold. (click to enlarge)

Gold rally

Investors’ appetite for physical gold, such as bars and coins, has driven up share prices of exchange-traded funds (ETFs) specializing in precious metal as well. For instance, take a look at SPDR Gold Trust Shares (GLD), the world’s largest gold-backed ETF. GLD gained 3% in 2008 and 6.9% so far in 2009.

The reason investors are also chasing GLD is that it offers investors an easy way to invest in the bullion without having to hold the metal themselves (you will have many more things to consider, such as storage and insurance, if you want to hold physical gold yourself). If you invest in GLD instead, your investment will reflect directly the price of gold because GLD’s share price is determined based on 1/10th of an ounce of gold. SPDR Gold Trust buys and stores physical gold to back GLD prices. In fact by tracking holdings of SPDR Gold Trust, you can get a sense of the demand for gold. Currently holding 985.86 tonnes of gold, a record level for GLD, the indication is that demand is strong.

If you are interested in investing in precious metal ETFs, check out these funds in gold and silver:

  • SPDR Gold Shares
  • iShares COMEX Gold Trust (IAU)
  • Market Vectors Gold Miners ETF (GDX)
  • PowerShares DB Gold (DGL)
  • iShares Silver Trust (SLV)
  • PowerShares DB Gold Double Long ETN (DGP)
  • PowerShares DB Precious Metals (DBP)
  • PowerShares DB Silver (DBS)

Among them, GLD has the largest daily trading volume according to Morningstar data, followed GDX and SLV. Remember, volume matters when trading an ETF. Not only because of the bid/ask spread, but also for the survival of the fund.

Stock chart from INO Stock Analysis

======================================

My Disclosure: Long DGP and GLD – jschulmansr

Catch the New Bull! – Buy Gold Online – Get 1 gram free just for opening account!, no minimums – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

======================================

Want a Way Out of the Economic Stupidity? Buy Gold – Seeking Alpha

By: Adam Lass of Wave Strength Options Weekly

For every analyst arguing one side of the above arguments, you have another analyst strongly arguing the opposite. And often you have the majority of analysts taking one position in the above arguments and then flip-flopping like a politician to the opposite position just two months later if things move the opposite way from their predictions.

Make 203% as Washington becomes a global laughing stock

According to our nation’s new “Intel Czar,” the economy is the number one threat to the U.S. right now.

In testimony before the Senate Intelligence Committee, National Intelligence Director Dennis Blair warned that: “The longer it takes for the recovery to begin, the greater the likelihood of serious damage to U.S. strategic interests.”

Now, one ought to keep in mind that Blair was addressing the committee just a day or so before Congress would be disgorging the bolus known as the 2009 Stimulus Act. As such, Blair, with his 49-page statement, was just one more player in the administration’s full court press.

Our Own Worst Enemy

Still, Blair does make some interesting points: Suddenly, al-Qaeda is no longer the top-listed actor. Indeed, most of the “Axis of Evil” has fallen several notches down the old hit parade.

North Korea’s current or Iran’s future nukes? Still salient, but not “Number One with a Bullet,” as old Casey Kasem used to say. Russian territorial belligerence and Chinese currency intransigence? Worrisome in the long run, but still not the top threat.

No, Washington’s Numero Uno spy tells us that our worst problems stem from the rot within. Or, to quote the ever-so-sage Walt Kelly: “We have met the enemy, and he is us.”

Our Newest Secret Weapon: The Dollar Bomb

The grand economic downturn (wow, that is such an elaborate way to avoid saying “depression”) presents two key security issues. The first seems obvious enough: We need cash to fully fund our military.

I suspect that this is less of a problem than it seems at first blush. Coming up with more dollars these days is actually remarkably easy: Washington just prints as many as it wants.

In fact, this may even turn out to be a bit of a blessing in disguise (okay, it’s a really good disguise, but bear with me here). A great way to get more bang for your newly imagined bucks would be to hand them off to military contractors, who could then hire more workers to build more armored troop carriers, which could then be blown up in Afghanistan. Then we just do it all again!

Bingo: You’ve cut unemployment and sopped up excess industrial capacity in one fell swoop! Hey, it worked for LBJ and Nixon, right? Right? Hey, stop throwing those “Whip Inflation Now” buttons at me!

The Price of Weakness

Let’s move on to issue two: The longer this debacle continues, the more folks in odd corners of the world might get the idea that maybe those “‘Mericans ain’t so smart after all.”

Much like Britain in its day (an apt comparison, since we pretty much bought our empire used from the Brits at the end of WWI), global control pretty much depends on the projection of the image of power. When that image falters, suddenly café agitators round the world have a much easier time persuading recruits to run around with Kalashnikovs and C4 undergarments.

And indeed, if you dig deep into Admiral Blair’s report, he does mention that al-Qaeda’s successful recruitment of Westerners over the past two years is making it increasingly difficult to play “Spot the Terrorist” at airports.

Hard to March When You’ve Shot Yourself in the Foot

But a mere economic downturn could not make us look but so dumb. Seriously, these things happen all the time, without risking national security. No, what makes us look inane and weak is the way in which our ineptitude has exacerbated a downturn into a full-blown crisis.

An example: Over the past few days, Justice and I have both bemoaned the current Secretary of Treasury’s glacial pace. It’s not so much that we want to see trillions in funny money dumped on us. It’s just that we wish they would rip the damn bandage off and move on already.

After weeks of promising to reveal his latest scheme, the best we got was a promise to come up with a schedule for formulating a plan, along with some vague threats to further “stress test” banks that have obviously already failed any sort of common sense test.

“It’s the Other Guy’s Fault. Oh Wait, I Am the Other Guy”

After calming down a bit, I actually went so far as to check with some connections I have in Washington as to why Geithner is moving so slowly. The current excuse coming out of the Treasury? The “New Team” has been unable to hire adequate expertise to figure out what to do next.

As I pointed out last week, the “New Team” is pretty much the “Same Old Team” that screwed things up in the first place. Indeed, the whole reason we were told to tolerate them was because their prolonged exposure supposedly ensured their expertise on the topic.

No wonder folks outside our borders are beginning to think we are stupid.

Turning Ineptitude Into Gold

There is one place where they are treasuring our fiscal inanities. Canada is enjoying a (relative) boom at our expense. Whereas the benchmark drop for most of the world’s markets has been hovering around 7.3% so far in 2009, Toronto’s TSX composite is down a mere 2.7%.

What’s propping things up north of the border? Gold, my friends.

Barrick Gold (ABX) and 11 of their fellow miners are up some 5.2% as a group this year. And it looks like this boom is nowhere near clapped out.

And why should it be, when guys like Euro Pacific Capital’s Peter Schiff are calling for gold to increase another 60% before the dust settles. Think that’s a speculative call? Heck, you can make a pure value argument for these guys.

After being bludgeoned by 14 months of recession and a 47% share price crash, one might imagine that U.S. stocks ought to be pretty darned cheap right now. And despite all this damage, the S&P 500’s trailing P/E is hanging out around 29.1, some 40% higher than at the market’s absolute top back in October 2007. Barrick’s P/E of 18.88 beats that by some 35%!

Now if you were looking for a way to turn our foolishness into treasure, you could simply do as the Canadians do, and buy shares of ABX. That increase in gold ought to bump up the share price some $20 between now and mid-summer.

If you were interested in a bit of leverage, you could easily pick up mid-dated ABX call options. That same $20 spike would offer you gains as high as 203%.

Disclosure: no positions- Adam Lass

==================================

My Note: Of course I agree with the above article but “no positions?”. You gotta play if you want to get paid!… – jschulmansr

Catch the New Bull! – Buy Gold Online – Get 1 gram free just for opening account!, no minimums – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

=================================

The following is a Very Interesting Article! – jschulmansr

In Today’s Enviroment, Neither Technical Nor Fundamental Analysis Alone Will Work-Seeking Alpha

By: J.S. Kim of SmartKnowledgeU


In an extremely difficult investment environment, it is often difficult to know who to believe. Deflation or inflation? Have financial stocks bottomed or do they have much more to fall? When gold corrects sharply, is the gold bull over or still alive? Is oil heading to $20 a barrel or $80 a barrel?

For example, when we look at oil prices, oil has plunged from $147 a barrel to less than $35 a barrel in 7 months! During this time, the deflationists have been out en masse in the mainstream media, claiming that plunging oil prices were directly attributable to plunging demand worldwide from economies that were stagnant. For example, here’s a link to a story that seems to infer that plunging oil prices are caused primarily by plunging U.S. demand and growing U.S. inventories. Though it would be ignorant to ignore the effect of a slowing global economy on demand for crude oil and its effect on lower crude oil prices in the futures markets, it would be equally ignorant to attribute the majority of crude oil’s plunge to a shrinking global economy as well.

How many people really believed that when we had $147 a barrel crude oil prices that this price was solely attributable to skyrocketing demand?

Instead, I can assure you that these stories have been planted to distract you from the real culprit of plunging oil prices –fraud, manipulation of crude oil futures, and political scheming to try to save the U.S. dollar. The plunge in oil prices, after the fraud that caused the run-up to $147 a barrel, is most likely more significantly attributable to the root of this global crisis – a monetary crisis – than slowing GDP rates of world economies. There is much more to the story of any continuing and extended weakness in the United States Oil Fund, LP (NYSE:USO) than just sluggish demand from slowing world economies. Has global demand really shriveled so drastically to account for a 76% free fall in crude oil futures prices?

I’ve taken the stance for a long time now that the extreme volatility we have experienced in gold, silver, and oil futures markets is most likely nearly entirely driven by Wall Street manipulation and free market interventions executed by the U.S. Treasury and the U.S. Federal Reserve. For years, I’ve argued that Central Bank and government intervention into these markets have created massive distortions. In fact, the free-market interventions are so obvious now that even mainstream investment figures such as Donald Coxe, chairman and chief strategist of Harris Investment Management in Chicago, have made similar claims in recent months.

Unfortunately, if you rely solely on technical analysis and fundamental analysis in today’s investment arena without accounting for or anticipating government and Central Bank interference into free markets, you will not understand how to make money. The problem with U.S. regulatory agencies is that they have been asleep at the wheel for the last decade and have been non-responsive to those individuals that have been awake. Repeated requests to investigate fraud in stock markets and commodity markets have been ignored over the past decade by top U.S. regulatory agencies, even when the requests were accompanied by overwhelming evidence.

U.S. Representative Gary Ackerman [D, NY] demonstrated his understanding of the worthlessness of these regulatory agencies when he berated the SEC for aiding and abetting massive fraud in U.S. Securities markets. (Click to view)

I strongly believe that fraud on a similar scale is taking place right now and has taken place for years on the COMEX gold and silver futures markets. In the future, if U.S. Congressmen finally realize this, you will see U.S. Congressional hearings of a similar contentious nature occur with the U.S. Commodity Futures Trading Commission. Currently, there is a mountain of circumstantial evidence of very large players attempting to manipulate gold and silver futures contract prices, even during this recent spike in gold and silver futures prices.

Remember, Harry Markopolos presented evidence of the Bernard Madoff $50 billion fraudulent Ponzi scheme to the SEC over a period of 9 years and was repeatedly stonewalled and ignored by the SEC (Securities Exchange Commission). Markopolos stated in testimony before the U.S. Congress that the SEC was protecting fraudsters instead of prosecuting them and “that’s why they shy away from the big cases.”

Asked by lawmakers if his warnings to the SEC could have been more explicit, Markopolos said, “I even drew pictures so I don’t know how I could’ve been more explicit.” He added the agency “roars like a lion and bites like a flea…The SEC was never capable of catching Mr. Madoff. He could have gone to $100 billion” without being discovered, Markopolos testified. “It took me about five minutes to figure out he was a fraud.”

Just like Markopolos, it did not take me long to conclude that massive fraud is and has been occurring in the New York-based gold and silver futures COMEX markets. And just like Markopolos, I also presented what I believed to be strong evidence of this fraud to the commissioners of the overseeing regulatory agency, the Commodities Futures Trading Commission [CFTC]. While my efforts were acknowledged by the CFTC, in their own words, as “great info”, no action has been taken upon my request for an investigation into fraudulent activity in the gold futures markets. I felt that I certainly presented enough compelling circumstantial evidence enough to warrant an investigation, but so did Markopolous, and he was ignored for nine years.

On the other hand, Ted Butler’s tireless efforts in presenting fraudulent COMEX activity to the CFTC has resulted in an internal investigation but as of yet, there still has been zero action as a result of this investigation. In the end, all investigations are ultimately worthless to the common investor unless the investigations are sincere. As Markopolos stated in recent U.S. Congressional testimony, he believes that the regulatory agencies’ intent will never be sincere until a drastic overhaul of the agencies occurs.

Markopolos hit the nail on the head for the biggest reason why the efforts of people such as myself and and many others to expose fraud in certain markets is being ignored by regulatory agencies: “What you’ll see is the [regulatory agencies are] busy protecting the big financial predators from investors and that’s their modus operandi right now.” In the case of gold and silver futures markets, when the agencies involved in the fraud most likely include the U.S. Treasury and the U.S. Federal Reserve, you will never see a true investigation materialize. So if, as investors, we are all fighting an uphill battle against fraud that has been imprinted within the “system” for a while, what is my point, right? My points are the following:

(1) Fraud has been part of the system for a while now, it will continue to be part of the system, and every investor needs to anticipate fraudulent activity to be profitable in these markets. Reliance on technical and fundamental analysis only will most likely lead to poor analysis.

(2)During periods of great economic crisis such as the one we are facing today, fraudulent activity will increase.

(3) Fraudulent activity manifests itself in the form of great distortions in stock markets and commodity markets. Why do you think you have seen financial stocks bounce around from $40 a share one month to $85 two months later, back down to $30 a share six months later, and up to $90 a share one month later? Why do you think you’ve seen gold plunge from over $1,000 an ounce in futures markets to $680 an ounce and then climb right back to more than $950 an ounce?

So the lessons to be learned are these:

(1) Volatility, due to massive fraud and free market intervention, is here to stay.

(2) To know how to play this volatility, you have to be able to analyze the situations properly and understand if fraudulent schemes are sustainable over the long-term or if they are only sustainable over the short-term.

(3) By taking step (2) into consideration above, you will know if rising financial share prices are a house of cards ready to tumble again or if they are a good long term play; if tumbles in gold prices should be interpreted as the end of a gold bull or a great buying opportunity; if oil prices are likely to remain low for a while or if a rapid spike in prices is likely in the future; and so on.

Do this, and you can make volatility your friend and not your enemy, because for now, volatility is here to stay.

My Note: I highly Recommend visiting SmartKowledgeU and signing up for the free newsletter, I did… – jschulmansr

==============================

One other note: In Comex Silver it is a few large banks which represent over 90% of the short interest, and Gold has a similar situation where the shorts there are in on an average around $750 – $850oz, where the short positions where initiated. How long will they be able to hang in there? If Comex actually follows thru along with the CFTC in their investigation and these positions come to light… Wow what a potential “Short Squeeze”! We could see a frenzy where Gold will shoot to $1500 and Silver to $25-$50 oz  easy. – We will see… – jschulmansr

Catch the New Bull! – Buy Gold Online – Get 1 gram free just for opening account!, no minimums – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

==============================

Gold Around the Globe: Setting Records – Seeking Alpha

Source: Monday Morning

Gold’s performance in 2008 could look like a real yawner.

After all, it only managed to eke out a 5.7% gain. Not the kind you’d normally brag about over cocktails.

As we rang in the 2009 New Year, gold at $850 an ounce (in U.S. dollars) was roughly 15% below its all-time record high, set in March 2008.

But everything in life is perspective. In a year when oil lost 59%, the Standard & Poor’s 500 Index was down 38%, and the Dow Jones Industrial Average gave back 30%, things could certainly be worse for gold bullion investors. Much worse, in fact. Just ask the typical investor about his portfolio: He’s likely to grumble, and change the subject.

As it turns out, 2008 marks the eighth consecutive year that gold has clocked a positive annual return. It’s now starting to look like the trade of the decade.

Truth be told, many are disappointed with gold’s behavior during the October-November stock-market panic, too. But here again, it’s all relative. When we compare the Standard & Poor 500 Index (a proxy for the market) with the SPDR GLD Trust (an ETF proxy for Gold) (GLD), we know where we’d rather have our money.

As this chart shows, from September to December, gold, despite its volatility, ended essentially flat in U.S. dollar terms, yet shows a marked recovery since the end of November. The S&P, on the other hand, looks like an Alpine ski hill heading for Jackson Hole. The divergence between the two is remarkable.

During last fall’s violent stock market downdraft, the U.S. Dollar Index (USDX) put on a spectacular, unprecedented two month – 15% rally. Spectacular, because to get even a 10% move over an entire year is a big deal for any major currency.

But gold is still (mistakenly) considered by many as the “anti-dollar.” So its behavior during a U.S. dollar rally does not come as a complete shock in hindsight.

Yet the gold price we see is misleading in two significant ways.

First, try going out there and buying an ounce of physical gold. In normal times, the average coin dealer will charge in the neighborhood of 3% above spot price. This past November, that premium shot up by 3-5 times, with many charging 10%-15% above spot, plus eight weeks or more for delivery. So when buying an ounce of gold, how realistic is the spot price, especially during a panic? In the midst of the mayhem, one larger Canadian precious metals dealer, Kitco, saw its list of products shrivel overnight from about 16 items to merely three, due to a lack of supply.

Second, gold is quoted in U.S. dollars around the world. But India is the single-largest gold market, with the rest of Asia showing a strong affinity for the universally cherished yellow metal. Throw in Europe and Latin America, and you can see how most of the world looks at gold through entirely different lenses – through their own currencies.

To be fair, let’s gain some distance from our own provincial viewpoint by taking a small trip around the globe. This way, we can get a handle on how the price of gold has behaved elsewhere.

Euro Gold

During the anomalous spike in the U.S. dollar last fall, the European euro lost considerable ground against it. So gold priced in euros shot up. March saw the record of near € 650 gold bettered in September by € 670 gold. Europeans were clearly happy with gold’s behavior, which currently sits around an all-time euro high of € 720.

UK Gold

Gold priced in British pounds sterling has performed astoundingly well. Brits saw gold at £500 per ounce in March, then £530 in September, and £600 by year’s end. Gold, now at £650, is still setting new record levels, dating back to 1717 when they began keeping records.

Canadian Gold

Canadian gold investors have few gripes. In March of last year, gold was trading at C$1,003; by late September, the price was up by nearly C$50. And right now, it hovers at a record C$1,160 level. Despite the amazing strength the Canadian dollar has shown in recent years, gold has performed very well in this resource-based currency.

Brazilian Gold

Brazil is the most populous country in Latin America. And gold’s performance in the Brazilian real did not disappoint either. The record set in March at R$ 1,719 per ounce was easily surpassed in September with a sharp spike to R$2,069. Today, it sits at R$2,115; which is R$415, or 24%, above its March levels.

Indian Gold

India’s currency is the rupee (INR). And for traditional, cultural, and even practical reasons, Indians are the biggest gold investors on the planet. As in much of the rest of the world, gold set a record near INR41,000 in March. It then pulled back in July, but spiked to a new record near INR43,000 in September. At roughly INR45,800 today, gold is priced way above its previous March and September 2008 record levels.

Chinese and Japanese Gold

If anyone should be disappointed with the performance of gold over the past year, it is investors in China and Japan. Gold’s record in March, at CNY (yuan) 7,050, has not been bettered yet. September saw a spike back near the CNY6,250 level, and gold currently rests at a price of roughly CNY6,400 per ounce.

Japan’s gold price hasn’t fared much better. The March record near ¥100,000 per ounce remains unchallenged. Gold managed a rally to ¥95,000 in September, but has since fallen back to the ¥84,850 level.

So as the U.S. dollar rose late last year, the Chinese yuan and Japanese yen were the two major currencies that tagged along, making gold investors relative losers in those nations. The Chinese and Japanese 2008 gold experience differs little from the American one. And yet, gold in U.S. dollars is currently just 8% shy of its all time record at $1,023.50.

Despite the recent American, Chinese and Japanese gold experience, most of the rest of the world’s gold investors are a happy lot. When converting the price back into their home currency, those investors are basking in its glow, while gold sits at or near all-time record highs.

For now, however, gold is still priced in dollars for many market participants. The same is true for all other commodities. I expect that will change over the next several years. Scores of foreign central banks have indicated their intentions to lower levels of dollar-denominated reserves to reduce exposure. Meanwhile, Kuwait has dropped its dollar peg, opting instead for a basket of currencies. And Iran already trades some of its oil for non-U.S. dollar currencies.

As the U.S. dollar continues to lose value – and hence, its influence – on the world stage, commodities are increasingly likely to be priced either in local money, or to be quoted in a variety of currencies.

Heck, commodities may even be priced in quantities of gold before this is all over. Gold investors can only hope. For now, as new price records are regularly being established, most aren’t complaining about the value of their gold.

With their sights set on breathtaking new heights to come, American, Chinese, and Japanese gold investors are sure to see their patience rewarded, as have already so many of their fellow investors the world over.

Original post

======================================
Catch the New Bull! – Buy Gold Online – Get 1 gram free just for opening account!, no minimums – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

======================================

 In yesterday’s post I included a partial list of tier 2, tier 3 junior mining companies to check out, and after doing your due diligence; potentially invest in. Some Bargains in there at or near book values.

======================================

Look to Junior Miners as Gold Feeding Frenzy Ensues – Seeking Alpha

By: James West of Midas Letter

Ever seen what happens to a piece of meat thrown into a tank full of vicious piranhas?  

The water is whipped into a froth and within seconds the meatless bone sinks to the bottom. There’s virtually nothing left.

The same thing is about to happen in the gold bullion market.

After some apparent weakness in Asian markets, gold powered higher Monday as news of the Japanese economic rout sent global markets into freefall. The only thing that stopped it from happening in the Unites States was the mixed blessing of a holiday keeping markets closed.

I say mixed, because a second day of selling overseas means the American market will have two days of pent up selling pressure to be unleashed as the market opened Tuesday morning.

The news keeps getting worse out of global G7 economies, and that has investors flocking to gold in recognition of its safe haven role.

ETFs are the biggest consumers of physical gold right now, and last week global ETFs took down the equivalent of 5% of the annual world gold production in just one week.

SPDR Gold Trust GLD.PGLD.A, popularly known as GLD, said the gold bullion it owned rose by more than 100 tonnes to 970.57 tonnes as of Thursday, which marked the biggest weekly gain in the history of the gold-backed exchange-traded fund.

One does want to bear in mind that all ETFs are not created equally. There are very few, in fact, that hold their full portfolio worth completely in physical bullion. It is incumbent upon the investor to read carefully the information provided by ETF vendors. While there has yet to be an instance of ETF-related fraud (that I’m aware of), ETFs are nonetheless a paper representation of the physical bullion, and therefore presents the opportunity for subterfuge.

This is the phase of the secular gold bull that silences all gold critics, and puts smiles on the faces of gold bugs that is so wide their heads threaten to fall in half! This is also the phase where the herd mentality starts to get folks looking around for the nearest bandwagon to jump on. Most of the bandwagons have rattled off into the sunset, though, so there will be a lot of head scratching as the left behind try to figure out how to get in the game.

Investors need to beware though. As gold demand increases so will volatility, as the sheer number of investors means profit-taking is likely to cause same-day leaps and drops by as much as $100 per ounce.

That’s because there are a lot of investors who will be taking profit off the table as the price ratchets higher, and the see-saw effect threatens tender hearts with life-threatening cardiac sincerity.

If you’re late to the game, the trick might be to a look a little further down the road than where the vultures are already fighting over the last few American Eagles or Krugerrands to what will inevitably be the next meal for the hungry mob – mining companies.

In particular, mining companies that boast near-to-production Canadian National Instrument 43-101 compliant resources. There are more than a few of them out there. With the intense interest that will follow a gold price spike, these companies will be able to raise a lot of capital at premium levels, and that will speed up the timeline to production in a lot of cases.

Other companies are not going to themselves go into production, and instead are developing huge deposits for joint venture or outright sale to major and mid-tier mining companies. Important here is the existence of agreements with aboriginal groups (if applicable) and stable democratic jurisdictions. Projects in Canada, the United States, Australia, and Mexico rank highest, with those in Peru, Chile, Colombia and Argentina, followed by African nations. Highest risk are those with socialist governments or military regimes, such as Ecuador, Venezuela, Russia, Mongolia.

Information is the key to successfully investing in the juniors, and keeping abreast of developments on a day-by-day basis is the secret to not losing your shirt.

Investing in juniors is risky, but in the current environment, investing in blue chip stocks, treasuries, mutual funds and financials is far riskier.

====================================

Gold Set To Rise Even Higher – Seeking Alpha

By: Mark O’Byrne of Gold and Silver Investments

After another strong week last week (both gold and silver were up some 3%) despite falling stock markets, gold continues its outperformance of other asset classes due to safe haven demand. It has surged again overnight in Asia and is now at 7 month highs and looks very likely to target its record high of $1,000/oz in the coming days.

Resistance at $950/oz was sailed through very easily overnight and the next level of resistance is $980/oz prior to a likely challenge of $1,000/oz in the coming days.

click to enlarge

With the global economy slowing very sharply, international demand remains very strong as seen in gold coin, bar, certificate and exchange traded fund demand. ETF holdings of the world’s largest gold-backed exchange-traded reached a record 985.86 tonnes as of February 13, up 15.29 tonnes or 1.6% from the previous day. The trust’s gold holdings are up a very significant 205 tonnes, or 26% in just the first six weeks of the year (see chart below).

Besides increasing retail, pension and institutional demand, many central banks are increasingly favourable to gold. Russia’s central bank has increased gold’s share in reserves, and plans to continue this trend in 2009, first deputy chairman told Reuters in an interview on Monday. The ECB Eurosystem’s reserves of gold and gold receivables increased EUR 1 million to EUR218.320 billion in the week ended Jan. 30.

Gold’s strength in recent days is particularly impressive as it comes in conjunction with a stronger dollar. However, this “strength” is more a function of a weakening in most fiat currencies internationally versus the dollar.

Gold has risen above £675/oz and €760/oz reached new record highs in many other currencies such as the South African rand and the Canadian dollar.

This bodes well for gold prices in the coming weeks as when the dollar begins to weaken again in the coming weeks, which seems very likely, then gold should rise even more sharply and target levels above $1,200/oz in the coming months.

Importantly, the commonly quoted COMEX gold price is actually lagging considering the extent of international demand as seen in the charts above.

And this marked rise in demand comes at a time when world gold production is actually falling.

While investment demand remains very strong and is increasing, there are growing fears about the declining supply of gold – the world’s mine gold supply has been falling in recent years and it fell to 2,385 tonnes last year, down 3.6 per cent from 2007 (despite the rise in prices in recent years).

This is a recipe for markedly higher prices in the coming months and the inflation adjusted high of some $2,400/oz looks more and more likely in the next few years.

Disclosure: no positions

=====================================

Gold -“Catch Me If You Can” – Whichever way you invest remember to do your due diligence especially if investing in the “junior” gold mining companies. I usually only invest in those companies which have production or are set to start producing in the very near term future…       – Good Investing! – jschulmansr


Catch the New Bull! – Buy Gold Online – Get 1 gram free just for opening account!, no minimums – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

======================================


Nothing in today’s post should be considered as an offer to buy or sell any securities or other investments; it is presented for informational purposes only. As a good investor, consult your Investment Advisor/s, Do Your Due Diligence, Read All Prospectus/s and related information carefully before you make any investing decisions and/or investments. –  jschulmansr

Share this:

  • Share on Reddit (Opens in new window) Reddit
  • Share on Facebook (Opens in new window) Facebook
  • Share on LinkedIn (Opens in new window) LinkedIn
  • More
  • Share on X (Opens in new window) X
  • Share on Pinterest (Opens in new window) Pinterest
  • Share on Tumblr (Opens in new window) Tumblr
  • Print (Opens in new window) Print
  • Email a link to a friend (Opens in new window) Email
Like Loading...

It’s Starting Again!

17 Tuesday Feb 2009

Posted by jschulmansr in 10 year Treasuries, 20 yr Treasuries, banking crisis, banks, Barack Obama, bear market, bull market, capitalism, central banks, China, commodities, Contrarian, Copper, Credit Default, Currencies, currency, Currency and Currencies, DGP, dollar denominated, dollar denominated investments, economic, Economic Recovery, economic trends, Fed Fund Rate, Federal Deficit, federal reserve, Finance, financial, Forex, Fundamental Analysis, futures, futures markets, gata, GDX, GLD, gold, Gold Bullion, Gold Investments, gold miners, hard assets, How To Invest, How To Make Money, hyper-inflation, IAU, IMF, India, inflation, Investing, investments, Junior Gold Miners, Latest News, Long Bonds, Make Money Investing, market crash, Markets, mid-tier, mining companies, mining stocks, monetization, Moving Averages, palladium, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, rare earth metals, run on banks, silver, silver miners, sovereign, spot price, stagflation, Stimulus, Stocks, TARP, Technical Analysis, TIPS, Today, U.S., U.S. Dollar, XAU

≈ Comments Off on It’s Starting Again!

Tags

Austrian school, Bailout News, banking crisis, banks, bear market, Bollinger Bands Saudi Arabia, bull market, central banks, China, Comex, commodities, Copper, Currencies, currency, deflation, Dennis Gartman, depression, dollar denominated, dollar denominated investments, economic, economic trends, economy, Federal Deficit, financial, Forex, futures, futures markets, gata, GDX, GLD, gold, gold miners, hard assets, hyper-inflation, India, inflation, investments, Jim Rogers, Keith Fitz-Gerald, majors, Marc Faber, market crash, Markets, mid-tier, mining companies, monetization, Moving Averages, palladium, Peter Grandich, Peter Schiff, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, protection, recession, risk, run on banks, safety, Sean Rakhimov, silver, silver miners, small caps, sovereign, spot, spot price, stagflation, Technical Analysis, TIPS, U.S., U.S. Dollar, volatility, warrants, XAU

It’s starting again, time to get aboard now, next stop $1000 to $1500! Gold cleared the $950 price mark today with a vengeance. During trading today Gold was up over $970 oz and closing at $967.50 up $25.30. Today’s main headline on MarketWatch was “Bears test November lows- Technical support levels in peril; Investors pile into Gold, Treasuries”. As I have mentioned in a recent post about Gold if we successfully clear and close above the $950 – $960 level the Gold will zoom up and have a retest of the all time highs! To answer my question I posted here… Gold has passed it’s first test with an A++. If you haven’t already invested in gold and precious metals you definitely need to do so now! Some of the following articles explain why… – Good Investing – jschulmansr

===========================

Here is where I buy my bullion:

Catch the New Bull! – Buy Gold Online –Get 1 Gram Free! Just for Opening and Account, No minimums, Buy Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

================================

Don’t Kick Yourself Later for Not Buying Gold and Silver Now – Seeking Alpha

By: Peter Cooper of Arabian Money.net

Gold is powering up towards $1,000 an ounce, and while the odd hesitation along the way is possible it will shortly cross this boundary, hit a new all-time high and then head upwards again.

A trend is your friend, especially if you take advantage of it. For gold the question is how best to leverage the up trend.

Gold and silver stocks are the answer. Conveniently precious metal stocks got really thrashed last autumn – along with gold and silver and every other asset class except bonds. So they are dirt cheap.

Rising prices

But will gold and silver equities not fall again if global stock markets tank, as they surely must with profit forecasts for the non-financials still ludicrously optimistic (face facts, for many major companies there will be losses and not profits in 2009)?

No they will not if precious metal prices are rising – and not falling as they did last autumn. And why will gold and silver prices keep on rising this time?

Well, investors are now very worried about bonds and currency rates, and that leaves gold and silver as the last safe haven in the investment universe. If there is only one investment class left to buy that ought to simplify things for investors.

Rising profits

Gold and silver producers are also big beneficiaries of falling energy prices this year, as up to a quarter of production costs go on energy. In addition, most mines are in non-dollar economies, so manufacturers have costs in depreciated currencies and income in the strong dollar.

That means that even if precious metal prices stagnate – and that looks highly unlikely – gold and silver producers are among the only commodity producers that will see profits jump in 2009.

My blog contains many articles on gold and silver which can point you towards some of the better, and riskier equity investments in this sector, and taking a risk in a rising market usually pays off handsomely.

The people who will be kicking themselves later in the year will be those who do not buy gold and silver stocks now.

This reminds me of my warning to those who did not buy Dubai property when they first had the chance, and even after a 50 per cent fall in house prices they are still 300 per cent up on their original investment!

========================

My Note: If you have been following my Blog “Dare Something Worthy Today Too!”, for any length of time this is exactly what I have been saying – many gold and silver stocks with production are still selling at or near book values! -jschulmansr

Catch the New Bull! – Buy Gold Online –Get 1 Gram Free! Just for Opening and Account, No minimums, Buy Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

========================

Gold Strikes Record Levels in Most Currencies – Seeking Alpha

By: Toni Straka of The Prudent Investor

With all equities markets deep in the red, MSM and bloggers have missed out on this easy scoop for several weeks: Gold currently strikes new all-time highs in most currencies. This sensational news, omitted in all those media that are normally quick to recommend this or that paper ‘asset’, which in the end is always only somebody else’s obligation, can be revealed at this blog exclusively, a Google news search shows. 😉

Gold traded for more than €771 and GBP 682 for the first time in history. The strong rise in the price of gold to new historic records in most countries except the USA is a logical reaction to the credit and solvency crisis that engulfs the globe as investors, nervous about a total market fallout, flee all paper promises and seek a truly safe haven.

Gold has never lost its value in more than 3,500 years, whereas no fiat currency survived longer than a human’s lifespan so far. Check out its resistance against inflation here.

click to enlarge

GRAPH: Gold priced in Euro has been on a tear since late November. It also outpaced all other asset classes. Chart courtesy of Stockcharts.com

I have been recommending investments in gold and mining shares since 2005. Licking my wounds from last year’s biggest and longest decline in this equity sector in 80 years, I will at least have a story to tell to my grandchildren.

But the fundamental outlook has only worsened in the past 4 years. Having correctly called for a sharp economic downturn in the USA since 2005, I nevertheless failed to recognize the dramatic situation in the Eurozone and the recent hard landing of China. This worsening global situation only underscores the value of holding the only asset that is not someone else’s obligation. The Euro is as doomed as are Federal Reserve Notes and nobody outside the UK cares about Sterling anymore.

We are about to witness the era of busted major fiat currencies that will go out the same way as did all unbacked fiat curencies in the past 1,000 years.

The Chinese tried it in the 11th century and it ended in a revolt. The same happened in France in the 18th century where it gave birth to the Republic. The decline of the Austro-Hungarian empire in WWI came on the heels of hyper-inflation and Germany’s fate could have taken another turn in the 1920s, if it were not for the hyper-inflation that paved the way for Adolf Hitler.

Unfortunately, we could very well end up as happened in past crises, with everyone a millionaire beggar.

========================

Bullish Long Term Outlook for Gold – Seeking Alpha

By: Peter Degraaf of pdegraaf.com

The long-term outlook for gold is very bullish, for to paraphrase Sir Winston Churchill’s famous remark, “never before in history have so many dollars chased so few ounces of gold (and silver)”.* The mountains of currency are rising, while the number of ounces of gold produced by gold mines is dropping.

The passing of the Stimulus Bill, referred to by some as the Porkulus Bill, will add billions of dollars to an already ballooning deficit. Instead of allowing the excesses in the credit markets to work themselves out by letting healthy institutions prosper, while allowing unhealthy institutions to fail, the new administration, aided by Congress, is throwing gasoline at the fire by rewarding shoddy business practices. People like Barney Frank and Christopher Dodd, who strong-armed the banking industry to make questionable mortgage loans, are now helping to shape the decisions that will prolong the problems. The foxes are still in the henhouse.

In the 1960’s it was James U. Blanchard III who pointed to the growing US deficits as the trigger that would cause gold prices to rise. In those days the deficits were still counted in millions of dollars. One wonders what Jim would say about deficits that are now counted in trillions of dollars. His advice would surely be: “Buy Gold”.

It was my pleasure to meet Jim Blanchard at one of his hard money conferences in New Orleans. Jim founded the National Committee to legalize the ownership of gold in the USA. In 1973, during the inauguration of President Nixon, Jim hired a small plane that flew near the inauguration site towing a banner that read: “Legalize Gold”.

Jim did everything with style and ingenuity. During one of his conferences he needed to move about one thousand of us from the convention hotel to a nearby convention center. He hired a marching band, and while police controlled several intersections the marching band led us to the center.

Let’s now look at some charts.

Featured is the chart (courtesy www.stockcharts.com that compares the price of gold to the XAU index (top), and compares this picture to the HUI index (bottom). The blue vertical lines draw your attention to a ‘link’ when the Gold/XAU rises above 5 and the HUI index begins a multi-month rise from a bottom. The red vertical line points to the only exception to this trend, since 2002. In that last seven years this early warning signal has worked 7 out of 8 times.

The last link is the ‘mother of all signals’, as the index rose to a record high of 11.5, while the Huey put in a four year bottom.

According to research done by John Hussman, in the past, when the gold/XAU ratio reached a point above 5, while the ISM purchasing managers index registers a reading below 50 (indicating the US manufacturing sector is decreasing), gold shares advanced at an annual rate of 125%. The current reading for the PMI is 35.6%, while the gold/XAU is at 7.2.

Featured is the ‘real interest rate’ chart, as reported by the Federal Reserve Bank of St. Louis. The bank shows the real rate at zero percent, having risen up from -3%. If we use the figures supplied by John Williams (see next chart), we arrive at a negative ‘real interest rate’ of -3.5%. Unless and until real rates turn positive by at least 2%, and for at least 6 months, we can depend on gold continuing its bull market rise.

This chart courtesy www.shadowstats.com compares the official CPI rate in orange to the John Williams interpretation in blue. With the Williams CPI-U at 3.5% and short-term bills at 0% interest, the ‘real interest rates’ are negative by 3.5%.

Featured is a chart (courtesy www.stockcharts.com) that compares the HUI index to the US dollar for the year 2005. For those who feel that gold stocks cannot rise unless the US dollar falls, this chart tells us that both gold stocks and the US dollar ended the year higher than at the start of the year.

As long as other currencies, such as the Euro, Yen, Pound and Canadian dollar are having problems of their own (caused by monetary inflation), the US dollar does not need fall, and gold and gold stocks can still rise.

Featured is the weekly gold chart (courtesy www.stockcharts.com). The blue arrows point to bottoms in the 7 – 8 week gold cycle. The last 3 cycles were short, thus the expectation is that we are due for a longer one, perhaps 9 or 10 weeks. The black arrow points to the upside breakout that occurred last week. This breakout came from beneath resistance that went back all the way to March 2008 AD. The green arrow points to the target for this breakout. The supporting indicators (RSI & MACD) are positive, with room on the upside.

The Gold Direction Indicator moved up from a reading of + 20% on Feb. 9th, when gold bullion was 895.00, to the current reading of +60% with gold bullion at 941.00.

Featured is the weekly silver chart (courtesy www.stockcharts.com) . Price has risen four weeks in a row and is expected to meet resistance at the purple arrow. Once this resistance is overcome, the target is at the green arrow. The supporting indicators, (RSI & MACD), are positive with room to rise.

Featured is the price progression for silver during the past five years (annual average – data supplied by the Silver Institute).

Summary: Last week’s breakout by the gold price confirms that the Christmas rally that started in November is ongoing. In the short-term we can expect a lot of volatility, as commercial traders and bullion banks that are ‘short’ gold will do their utmost to suppress the price. They will do this by testing the current breakout. They will use the threat of ‘asset deflation’ (which has nothing to do with the effects of monetary inflation, which always leads to price inflation), and they will use the threat of IMF gold sales to try to cap the gold price rallies.

In the longer term the huge increases in currency (both paper and digital), on a worldwide basis, tell us that the gold bull still has a lot of running room left.

*(“Never in the field of human conflict was so much owed by so many to so few” – Sir Winston Churchill referring to the Battle of Britain).

DISCLAIMER: Please do your own due diligence. I am NOT responsible for your trading decisions.- P. Degraaf

========================

Catch the New Bull! – Buy Gold Online –Get 1 Gram Free! Just for Opening and Account, No minimums, Buy Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

===============================

Upwrds momentum builds as gold breaches $950 – MineWeb

Source: MineWeb.com

EXPLOSIVE INCREASE AHEAD?

Upwards momentum builds as

gold breaches $950

The gold price this morning moved quickly through the psychological $950 an ounce level and predictions of $1000 gold being seen sooner rather than later seem far from far-fetched.

Author: Lawrence Williams
Posted:  Tuesday , 17 Feb 2009

LONDON –

In what has been a relatively steady climb over the past few weeks, gold moved back well above the psychological $950 an ounce mark in this morning’s trading (over $960 at the time of writing) – the first time in seven months it has achieved this level – while silver was approaching $14 an ounce, being pulled upwards by the gold price.  Platinum and palladium were also better as platinum maintained its differential price advantage over gold.

Indeed gold looked poised to move higher still with ETF inflows continuing and a glimmer of renewed demand interest in India as sentiment may be moving towards a growing feeling that the price is poised to increase further.  Previously India, the world’s largest area of consumption,  has seen gold sales and imports at their lowest level for some time with traders anticipating lower prices.  Today, though, the gold price in rupees hit a new record at over 15,000 rupees per 10 grams and there has been wide expectation of the price moving to 16,000 rupees in the short term with open interest in metal for April increasing a little.

In the Far East in general there appears to be a movement into gold developing strongly as the stock market continues to drift downwards.  The market has seen the dollar price gold consolidating above $930 of late and there has been a strong feeling that the metal is poised to move higher which is now turning into real purchases and becoming reality.

Bloomberg reports that there is also talk of Central Banks buying gold rather than selling .  The newswire quotes Steven Zhu of Shanghai Tonglian Futures Co. as saying “There’s been a lot of talk about central banks buying but they are quiet about it because they don’t want to disrupt the market, so the market tends to react when there’s some fresh news.”   There is also a report today that Russia’s Central Bank has raised gold’s share of its reserves and plans to continue doing so.

To an extent $950 an ounce is seen by some as an important trigger point towards the movement to $1,000 gold and it certainly seems that the momentum is with the yellow metal at the moment.  Stock markets remain weak, and in reality there seems to be little but gloomy news ahead.  Economies are very definitely in recession and confidence in the dollar is not strong.  Gold is increasingly being seen by many as the best way of protecting wealth in the current environment.

The only weakness has been the fall-off in demand from the traditionally strong Eastern markets, and if the realization that gold is more likely to move higher than fall back takes serious hold there then, coupled with the continuing movement by western investors into gold, the price increase could accelerate.  $1,000 gold may be with us again sooner than expected and this time there is a growing feeling that it could stay there for an extended period.  Virtually no-one seems to be betting against this occurring in the very short term – indeed as momentum builds, which it appears to be doing, there could be an explosive price increase ahead in the months ahead.

=============================

Catch the New Bull! – Buy Gold Online –Get 1 Gram Free! Just for Opening and Account, No minimums, Buy Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

===================================

Remember: Don’t Forget about Silver too!

Listed Gold and Silver Stocks Soar – Mineweb

Source: Mineweb.com

SILVER BEST PERFORMING

Listed gold (and silver) stocks soar

Gold bullion, and listed gold stocks, decouple from a strange and troubled world.

Author: Barry Sergeant
Posted:  Tuesday , 17 Feb 2009

JOHANNESBURG –

Precious metal prices moved strongly higher on Tuesday, led by gold bullion, which hopped more than USD 30 an ounce to above USD 970 at one stage, prompting yet another sparkling performance by listed gold equities. Gold bullion is currently trading around seven month highs, and just 6% below the record level it set in March 2008.

At just over USD 14 an ounce, silver is around 34% off its record highs, while platinum at USD 1,085 an ounce is 52% off, and palladium at USD 219 an ounce, a significant 63% off.  Demand for platinum group metals has been deeply damaged by reduced demand from the auto sector, which uses the metals in auto catalysts.

Silver stocks, which command a combined global market value (capitalisation) of USD 13bn, currently rank as the best performing equity sub-sector in the world, led by stellar performances from  Silver Standard, Fresnillo, and First Majestic. The global grouping of primary silver producers is relatively small, given that the majority of silver is produced as a byproduct at bigger mines; BHP Billiton, the world’s biggest diversified resources stock, ranks as the world’s biggest silver miner.

There are, however, hundreds of listed stocks that rank as primary gold producers. This global grouping currently carries a combined market value of just over USD 230bn, dominated by Tier I stocks; Barrick, the world’s biggest gold name by production and value, currently holds a market value of just below USD 34bn. This ranks Barrick as the world’s No 5 overall mining stock, after BHP Billiton, Vale, Shenhua, and Rio Tinto. Two other Tier I gold producers, Goldcorp and Newmont, now also rank as members of the world’s top 10 mining groups.

While silver stocks, as the small cousin of precious metals, may rank as top equity performers, on a relative basis, the Tier II gold grouping, seen alone, ranks as the world’s leading equity subsector. Some of the top performances in this grouping have been produced by recovery stocks such as Centerra, while JSC Polymetal represents the recovery Russian stock, from a jurisdiction where stock prices were savaged to an extent rarely seen elsewhere.

It is also of interest that some stocks in the global Tier II gold grouping are currently trading close to 12-month highs – a factor virtually unthinkable in any other sector – as seen in the cases of Iamgold, Eldorado, Red Back, and also Franco-Nevada, a royalty, rather than operating, company. It is of further interest that investors have at long last started to move back into Chinese gold stocks in the past few weeks, benefiting the likes of Zijin (Tier I), Zhongjin, and Shandong (Tier II), and Hunan Chenzhou and Lingbao (Tier III).

The SPDR Gold Shares exchange traded fund (ETF), which holds gold bullion on behalf of investors, rather than mining the stuff, is close to trading at all time record levels. The fund currently holds physical gold bullion worth just under USD 31bn; if it were an operating entity, it would rank second only to Barrick. However, if other gold ETFs around the world are also taken into account, the amount of bullion currently held on behalf of investors is worth well above USD 40bn. Silver ETFs, which are trading in price terms in line with silver bullion’s 34% discount from its record high, currently hold close to USD 4bn worth of physical metal.

In terms of individual performances by gold stocks, the top overall Tier I performance award is probably deserved by Kinross; the Tier II award is most difficult, but would likely go to Iamgold, while Novagold appears to be a clear winner among the Tier III grouping. Among developers and explorers, spectacular performances have been put in by La Mancha Resources, Azteca Gold, and San Anton Resource; Central Sun Mining has also shown radical price moves, possibly assisted by corporate action.

Global tier I gold stocks      
  Stock From From Value  
  price high* low* USD bn  
Goldcorp USD 32.66 -38.0% 136.0% 23.829  
Polyus USD 32.00 -60.0% 128.6% 6.100  
Harmony USD 11.96 -17.9% 118.6% 5.005  
Lihir AUD 3.47 -21.0% 128.3% 4.840  
AngloGold Ashanti USD 31.10 -20.5% 132.6% 10.995  
Zijin CNY 8.28 -62.4% 120.2% 12.475  
Barrick USD 38.71 -29.3% 124.1% 33.773  
Newcrest AUD 34.28 -15.4% 107.1% 10.502  
Gold Fields USD 11.47 -31.9% 147.2% 7.495  
Kinross USD 19.36 -29.3% 182.6% 12.875  
Newmont USD 42.60 -22.8% 101.2% 20.152  
Buenaventura USD 21.75 -49.3% 141.7% 5.979  
Freeport-McMoRan USD 27.89 -78.1% 77.6% 11.469  
[[SPDR Gold Shares ETF]] USD 95.28 -5.1% 44.4% 30.709  
Tier I averages/total -36.6% 126.6% 165.489  
Weighted averages -43.4% 122.9%    
         
TIER II Stock From From Value  
  price high* low* USD bn  
Zhongjin CNY 50.48 -58.8% 121.4% 2.594  
Iamgold USD 8.24 -4.8% 271.3% 2.437  
Simmer & Jack ZAR 3.24 -48.7% 120.4% 0.335  
Yamana USD 9.42 -52.7% 184.6% 6.903  
High River CAD 0.13 -96.4% 212.5% 0.058  
Eldorado USD 8.68 -7.1% 264.7% 3.197  
Agnico-Eagle USD 55.42 -33.6% 165.5% 8.577  
Centerra CAD 5.23 -66.2% 481.1% 0.895  
Randgold Resources USD 48.49 -13.8% 117.6% 3.709  
Shandong CNY 66.94 -43.5% 153.6% 3.406  
Peter Hambro GBP 5.66 -63.3% 262.8% 0.785  
Hecla Mining USD 1.77 -86.5% 78.9% 0.385  
Golden Star USD 1.69 -60.9% 322.5% 0.315  
Franco-Nevada CAD 27.20 -0.1% 134.1% 2.158  
Fresnillo GBP 4.00 -30.4% 330.1% 4.094  
JSC Polymetal USD 5.30 -46.2% 430.0% 1.670  
Red Back CAD 8.50 -8.1% 197.2% 1.533  
New Gold CAD 2.93 -69.9% 211.7% 0.493  
Northgate CAD 1.74 -50.1% 159.7% 0.352  
Tier II averages/total -44.3% 222.1% 43.897  
Weighted averages -42.3% 188.1%    
           
TIER III Stock From From Value  
  price high* low* USD bn  
Western Goldfields CAD 2.35 -40.8% 370.0% 0.254  
Great Basin CAD 2.10 -45.2% 130.8% 0.357  
Sino Gold AUD 5.59 -26.6% 135.9% 1.040  
Alamos CAD 8.25 -9.7% 135.7% 0.687  
Highland GBP 0.60 -72.0% 185.7% 0.278  
PanAust AUD 0.17 -86.8% 101.2% 0.167  
Kingsgate AUD 4.20 -33.3% 90.9% 0.249  
Int’l Minerals CAD 3.28 -50.7% 180.3% 0.243  
Allied Gold AUD 0.41 -50.3% 121.6% 0.107  
First Uranium CAD 5.15 -45.4% 404.9% 0.617  
Novagold CAD 4.75 -59.4% 900.0% 0.680  
Gold Wheaton CAD 0.29 -84.6% 1325.0% 0.213  
Oxus Gold GBP 0.08 -74.3% 113.9% 0.042  
Pan African GBP 0.04 -47.5% 113.3% 0.063  
Citigold AUD 0.23 -49.4% 50.0% 0.106  
Jaguar CAD 7.15 -47.7% 199.2% 0.362  
Pamodzi Gold ZAR 1.40 -88.3% 185.7% 0.013  
Oceanagold AUD 0.58 -81.9% 286.7% 0.060  
DRDGold ZAR 9.25 -9.8% 223.4% 0.340  
Dominion Mining AUD 4.82 -1.2% 152.4% 0.316  
Avoca Resources AUD 1.92 -34.2% 118.9% 0.338  
Integra Mining AUD 0.23 -67.6% 142.1% 0.057  
Royal Gold USD 43.33 -13.0% 90.5% 1.474  
Hunan Chenzhou CNY 12.84 -62.0% 115.8% 1.005  
Aurizon CAD 4.59 -15.5% 279.3% 0.538  
Kazakh Gold USD 6.80 -74.8% 209.1% 0.285  
Gammon Gold CAD 8.74 -22.0% 226.1% 0.829  
Crew Gold CAD 0.11 -94.6% 110.0% 0.071  
Lingbao HKD 2.42 -56.0% 202.5% 0.093  
Zhao Jin HKD 8.57 -54.7% 360.8% 0.483  
Rusoro Mining CAD 0.70 -63.7% 197.9% 0.216  
Minefinders CAD 6.59 -51.2% 97.9% 0.308  
Andina Minerals CAD 1.98 -57.3% 280.8% 0.125  
Crystallex CAD 0.36 -87.6% 260.0% 0.084  
Ramelius Resources AUD 0.57 -54.0% 52.0% 0.067  
Tanzanian Royalty CAD 4.96 -21.5% 149.2% 0.349  
Minera Andes CAD 0.64 -66.7% 100.0% 0.096  
Semafo CAD 2.07 -1.4% 176.0% 0.381  
Tier III averages/total -50.1% 225.7% 12.991  
Weighted averages -51.9% 170.0%    
                 

====================

In my opinion you need to move now and move quickly and get on this great Bull Market in Gold and ALL Precious Metals -jschulmansr

My Disclosure: Long Many of the Tier’s 1, 2, 3 mining stocks, Precious Metals Bullion, Long DGP,GDX, CES, ROY. You might say I am a Gold Bug and Proud of it! Good Investing! – jschulmansr

Catch the New Bull! – Buy Gold Online –Get 1 Gram Free! Just for Opening and Account, No minimums, Buy Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

============================

Nothing in today’s post should be considered as an offer to buy or sell any securities or other investments, it is presented for informational purposes only. As a good investor, consult your Investment Advisor, Do Your Due Diligence, Read All Prospectus/s and related information carefully before you make any investments. – jschulmansr

Share this:

  • Share on Reddit (Opens in new window) Reddit
  • Share on Facebook (Opens in new window) Facebook
  • Share on LinkedIn (Opens in new window) LinkedIn
  • More
  • Share on X (Opens in new window) X
  • Share on Pinterest (Opens in new window) Pinterest
  • Share on Tumblr (Opens in new window) Tumblr
  • Print (Opens in new window) Print
  • Email a link to a friend (Opens in new window) Email
Like Loading...

Wake Up Call!

16 Monday Feb 2009

Posted by jschulmansr in 10 year Treasuries, 20 yr Treasuries, Bailout News, banks, Barack Obama, bear market, bull market, capitalism, central banks, China, Comex, commodities, Copper, Currencies, currency, Currency and Currencies, depression, dollar denominated, dollar denominated investments, economic, Economic Recovery, economic trends, economy, Federal Deficit, federal reserve, Finance, financial, Forex, Fundamental Analysis, futures markets, GDX, GLD, gold, Gold Bullion, Gold Investments, gold miners, hard assets, How To Invest, How To Make Money, hyper-inflation, inflation, Investing, investments, Japan, Jschulmansr, Junior Gold Miners, Latest News, majors, Make Money Investing, market crash, Markets, mid-tier, mining companies, mining stocks, monetization, palladium, Peter Brimelow, physical gold, platinum, platinum miners, precious metals, price, prices, producers, production, rare earth metals, recession, resistance, risk, run on banks, safety, Saudi Arabia, silver, silver miners, small caps, spot, spot price, stagflation, Stimulus, Stocks, The Fed, TIPS, Today, U.S. Dollar, uranium

≈ 1 Comment

Tags

Austrian school, Bailout News, banking crisis, banks, bear market, Bollinger Bands Saudi Arabia, Brian Tang, bull market, central banks, China, Comex, commodities, Copper, Currencies, currency, deflation, Dennis Gartman, depression, dollar denominated, dollar denominated investments, Doug Casey, economic, economic trends, economy, Federal Deficit, financial, Forex, futures, futures markets, gata, GDX, GLD, gold, gold miners, hard assets, hyper-inflation, India, inflation, investments, Jeffrey Nichols, Jim Rogers, Keith Fitz-Gerald, majors, Marc Faber, market crash, Markets, Michael Zielinski, mid-tier, mining companies, monetization, Moving Averages, palladium, Peter Grandich, Peter Schiff, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, protection, recession, risk, run on banks, safety, Sean Rakhimov, silver, silver miners, small caps, sovereign, spot, spot price, stagflation, Technical Analysis, TIPS, U.S., U.S. Dollar, volatility, warrants, XAU

The U.S. Markets are closed today yet something very interesting is starting to happen. Can you sense it? The shift from deflation to inflation. The “smart money” big investors are sensing it and starting to jump into Gold in a big way! Gold Prices are holding steady overseas above the $935 support level. Todays articles show the why and how of this move by big money into Gold, read on… and Good Investing! – jschulmansr

==============================

 Something still stirring in precious-metals pond – Market Watch

By: Peter Brimelow of Market Watch

With some wild swings, gold gained about 3% on the week, closing Friday at $941. The Phx Gold Silver Index (XAU:

Technicians were impressed. Long-term chartist Martin Pring is deflationary-minded at present. Two weeks ago, he remarked that if certain trend lines were broken, “I would be dragged kicking and screaming into the bullish camp”. But now he simply says in his recent weekly Intermarket Review: “Not much to add to my recent bullish comments. Both the metals and shares recently broke out of giant patterns … With our Global Gold Index at a new all-time high – enjoy the ride!”
Pring also flags a powerful conceptual reason for the gold move. Discussing a chart of the inflation proofed Treasuries, and using the iShares:Lehm TIPS TIPT as a proxy, Pring says: “Here we see the inflation protected bonds, or TIPs. Who needs these in a deflation? But look, the price just broke to the upside … and volume is expanding! When we look at the longer term we see it’s still in a primary bear market … However this week’s breakout suggests a turn is likely.”
In other words, the bond market is getting seriously concerned about inflation. See Website
The Privateer, being Australian, is even more direct in its weekly remarks: “Why is gold going up? It is certainly not in spite of the global mania for bailout programs now sweeping the world. It is because of these programs. The more ‘liquid’ the global financial powers that be make their money — by creating it in ever larger swathes — the more they run the risk that the world starts to look elsewhere for a viable and trustworthy way to exchange goods and services.”
The Privateer’s invaluable $US 5X3 point and figure chart has now broken above its last downtrend, although its proprietor would like more progress: “This week the chart got up to and just above the second of the two downtrends. The ‘poke’ above the line which came with Gold’s close above $U.S. 945 on Feb. 12 is not yet decisive, a close above $U.S. 960 would be.” See Website
Silver, which I reported last week was exciting the gold bugs by showing unusual leadership characteristics, persisted — rising 3.5% on the week, including on Friday despite gold’s fall, and pushing the Gold/Silver ratio to 68.9 from last week’s 69.5.
But the star of the week was the reported bullion holdings of Spdr Gold Trust. (GLD:
GLD is regarded with deep suspicion by the radical gold bugs who think the metal’s price is manipulated. But at the least it has to been seen as a measure of the Western Hemisphere investment appetite for gold.
In contrast, Le Metropole Cafe monitors Indian gold imports and reports that, unusual in the past few years, the world’s largest gold consumer is standing aside for now. See Website
Interestingly, two sentiment indicators did not react much this past week. Mark Hulbert’s HGNSI on Friday stood unchanged at 60.90%. MarketVane’s Bullish Consensus actually lost a point on Friday to 78%, gaining only 3 points on the week. See Website
In serious gold moves, MarketVane excursions into the 90s are reportedly common.
===================================

Here is where I buy my Bullion, get one free gram of Gold just for opening an account! Catch the New Bull! – Buy Gold Online – Get 1 gram free! – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

===================================
Major Investors Piling into Gold – Seeking Alpha
By: James West of Midas Letter

Endeavour Financial Corp (TSX:EDV) closed a $100 million equity offering last week, and several other “bought deal” financings point to a strengthening trend: major investors are piling into gold.

The Offering was underwritten by a syndicate co-led by GMP Securities L.P. and Canaccord Capital Corporation (the “Underwriters”). Endeavour will use the funds to support its investment activity in the mining sector with an emphasis in the short term on precious metals.

The first quarter of 2009 has seen well over $1 billion flow into near term and existing mining companies, which is a reflection of the strong gold price amid safe haven demand. With estimates of U.S. government spending reaching as high as $2 trillion, large value investors are increasingly deterred by U.S. Treasury related securities in favour of precious metals.

  • Newmont Mining (NYSE:NEM), one of the world’s largest gold mining companies, raised US$1.7 billion in a combined common share/convertible debt deal which it will use primarily to fund the acquisition of the remaining 33.33% interest in the Boddington project in Western Australia that it does not already own and the additional capital expenditures that will result from its increased ownership in the Boddington project, as well as for general corporate purposes. Citigroup Global Markets and J.P. Morgan Securities led the placement.
  • Freeport McMoran Copper and Gold (NYSE:FCX) raised US$740 million through the issuance of 26.8 million common shares at $28 per share;
  • Kinross Gold Corporation (KGC) announced a “bought deal” financing for US$360 through the issuance of 24,035,000 million common shares US$17.25 per common share. The underwriters were led by UBS Securities Canada Inc.;
  • Osisko Mining Corporation (OSKFF.PK) entered into another “bought deal” led by Thomas Weisel Partners and BMO Capital Markets. The offering of 77 million units at $CA4.55 a share will gross CA$350.4 million. Osisko is developing the 6.28 million ounce Canadian Malartic Project Quebec.

Smaller deals are becoming more common for junior emerging gold companies as well. Among the recent actions:

  • Centamin Egypt (CELTF.PK) raised $CA69 million through the issuance of 106.2 million shares at CA$0.65 per share for development and construction of the Sukari Project in Egypt. This financing was led by Thomas Weisel Partners and Cormark Securities.
  • Romarco Minerals Inc. (TSX.V:R) announced a bought deal Friday worth $20 million for the development of the Haile Gold Mine in South Carolina. Romarco issued 54 million units at $0.38 each. The financing was led by a syndicate of underwriters led by Macquarie Capital Markets Canada Ltd. and including Paradigm Capital Inc. and GMP Securities L.P.
  • International Tower Hill Mines (THM) sold 2 million common shares at $2.50 per share for gross proceeds of CA$5 million, which will be directed towards further development of its projects in Alaska and Nevada. The placement was a “bought deal” led by a syndicate of underwriters led by Canaccord Capital Corporation and including Genuity Capital Markets and GMP Securities L.P.
  • Exeter Resource Corporation (AMEX:XRA) raised CA$25.2 million at $2.40 a share for development of its assets in Argentina and Chile.

And it isn’t just gold that is attracting big financing. On February 10th, Uranium One (SXRZF.PK) announced a $270 million investment by a Japanese Consortium comprised of Tokyo Electric Power Company, Incorporated (TKECF.PK), Toshiba Corporation (TOSBF.PK), and The Japan Bank for International Cooperation.

Concurrently with the execution of the subscription agreement, Uranium One has also entered into a long-term off-take agreement and a strategic relationship agreement with the Japanese consortium, both of which will become effective upon closing of the private placement.

The off-take agreement provides the consortium with an option to purchase, on industry-standard terms, up to 20% of Uranium One’s available production from assets in respect of which Uranium One has the marketing rights.

Junior Uranium company First Uranium Corp. (FURAF.PK) was also the beneficiary of a bought deal financing led by Macquarie Capital Markets this week, which saw First Uranium place 20.5 million units of its shares at $3.00 per unit for gross proceeds of $61.5 million. First Uranium will direct the funds towards the development of the Ezulwini Mine in South Africa.

Endeavour Financial is followed by many analysts and newsletter writers for its robust project pipeline.

Brien Lundin, who publishes the Gold Newsletter, says one of the main reasons he follows Endeavour Financials is because of management – especially Mr. Frank Giustra. He says this team now senses a market bottom, as they are raising capital to go after assets that now cost a fraction of what they did last year, or even six months ago. He intimates strongly that his subscribers should do the same, using Endeavour as their proxy. A mix of entrepreneurial expertise and value investing, he outlines what the smart money is doing now.

=============================

Here is where I buy my Bullion, get one free gram of Gold just for opening an account! Catch the New Bull! – Buy Gold Online – Get 1 gram free! – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

====================================

Gold: Now Demonstrating Trust in Obama – Seeking Alpha

By: Boris Sobolev of Resource Stock Guide

Gold is Starting to Believe the Obama Administration

Despite making loud headlines about stimulating the economy, the US government has been unable to raise the level of optimism among the general public, while the stock market seemed to drop into a deep state of apathy.  


Last week we received the long-awaited economic stimulus packet as well as the so-called plan for the rescue of the US financial system. We have already voiced our skepticism regarding the structure of the stimulus and its potential effect on the economy in a prior article.


As far as the size of the $787 billion package, it is clear that it is too small and too spread out into 2010 and beyond to be called a stimulus. $787 billion is just 5.6% of the GDP and when spread over two years will account for just 2.8% at a time when many industrial economies around the world are contracting by 5-10% per year. It can only be called a life support package, not a stimulus.

Japan, which got into a deflationary spiral as a result of a real estate bust, spent much more than 100% of its GDP since 1991 just to see its economy stagnate. Construction related investment alone ate up $6.3 trillion of public funds over the 17 years since 1991. Infrastructure spending accounted for $350 billion to $400 billion per year for the first half of the 1990s for an economy half the size of the United States.

The results of the Japanese fiscal stimulus were unimpressive, although it could be argued that without this stimulus, it could have been much worse.

With the United States facing similar post bubble dynamics as Japan did twenty years ago, how can we expect greater effectiveness of the Obama stimulus plan when it is insufficient and much of is clearly misdirected?

In reality, this economic stimulus package has to be viewed as only the first one of many yet to come. By having the US dollar as a world reserve currency, the US government can be much more effective than its Japanese counterpart in printing its own currency.

We will soon be quantifying the size of the government stimulus plans in trillions rather than in billions. Within the next 3 to 4 years, government spending can easily reach $10 trillion, doubling the size of the US government debt.

One of the main problems with this crisis is that the majority of the debt bubble is related to residential real estate, which does not produce cash flow, but only seems to eat it up. As home prices decline and unemployment rises, debt serviceability is worsening dramatically.

In order to avoid social unrest and to maintain popularity, the Democratic majority will face two realistic options which could begin to address the economic disaster:

  1. Forgive portions of mortgage debt which cannot be serviced. But who will pay for the losses – clearly not the weak banks. Uncle Sam would pick up the tab by printing more currency.
  2. Print new dollars to increase the nominal income of the indebted population through tax cuts, job creation, jobless benefits and various social spending.

There is no other politically possible way out of this mess other than to run the printing press. The way of the free market via bankruptcies is not popular so there is no sense to even discuss it.

Within hours President Obama will sign the stimulus into law, but we are sure that this is just the beginning of the government spending campaign.

As far as the US banks, the new US Treasury Secretary seems to be mimicking his predecessor, Hank Paulson. The essence of the announced “plan” is as follows: “We are absolutely sure that we will save our banking system, but are yet unsure of how we will do so. We will find out very soon, however. Stay tuned”.

While not knowing what to do with the banking system, the government is trying to temporarily act as one. The only specific point in Geithner’s announcement is the plan to increase the Term Asset-Backed Securities Loan Facility (TALF) facility from $200 billion to $1 trillion. This joint initiative with the Federal Reserve expands the resources of the previously announced, but not yet implemented TALF.

In essence, TALF will support the purchase of loans by providing the financing to private investors. In theory, this should help unfreeze and lower interest rates for auto, small business, credit card and other consumer and business credit. Treasury will use $100 billion to leverage $1 trillion of lending from the Federal Reserve. The TALF, which will potentially have greater effect than the stimulus plan, passed in a blink of an eye without any debate.

The markets around the world have deteriorated in deep state of indifference to the first round of actions of the new US government. Only gold is starting to demonstrate its trust in the Democratic majority. Since the inauguration, investors poured $6 billion into gold purchases through GLD alone. This is an increase of 210 tonnes in gold holdings or 24% in less than a month.

click to enlarge

Huge investment demand around the world has put an end to a steep gold correction of the second half of 2008. Most intermediate and long term technical indicators for gold have turned decisively bullish. A test of new highs by gold is very probable this spring.

In sum, gold investors are starting to believe that the Obama Administration sees one way out of economic problems which will for sure resurrect inflation.

================================

My Note: Did you catch that? They’re believing alright, not that Obama will get the situation fixed, just that he will cause inflation; yes even hyper-inflation , maybe even stagflation! Jump into Gold now before it’s too late… -jschulmansr


Here is where I buy my Bullion, get one free gram of Gold just for opening an account! Catch the New Bull! – Buy Gold Online – Get 1 gram free! – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

====================================

Moody’s, S&P Dole Out Global Downgrades – Time to Go Gold? – Seeking Alpha

By: Mark O’Byrne of Gold and Silver Investments

 Gold rose again on Thursday, briefly rising above $950/oz and was up 0.6% on the day. Determined selling on the open in Asia saw gold fall and profit taking has seen gold fall in Asia and in early trading in London. This is to be expected as gold had risen by more than 15% in less than a month.


US, UK Credit Ratings Look Set to Be Downgraded

The credit rating agency Moody’s has said that the UK and US credit ratings were being “tested”. In a novel and somewhat bizarre departure, Moody’s has split various “AAA” sovereign countries into three categories based on their strength in weathering the economic storm, denoting Ireland and Spain as the weakest, with the UK and US somewhere in the middle and Germany, France, Canada and the Scandinavian nations at the top.

This will in time be seen as gimmickry. Standard and Poor’s have already downgraded Spain to AA+ and did not create sub grades within the credit rating system.

Some have criticized Moody’s for being “unfair” to Ireland, Spain, the UK and US and have argued that these agencies previously gave almost everybody good ratings, and underestimated risks, but were now going to the other extreme.

This is errant nonsense and the unfortunate fact is that Moody’s, the other credit rating agencies and the vested interests in the financial services industry continue to underestimate risks, as they have done for months and years.

Given the massive deterioration in the public finances and economies of these nations, by right they should be downgraded and unfortunately in the coming months they will inevitably be downgraded.

But Moody’s and all the rating agencies realize that this would compound an already disastrous financial and economic crisis. Many pension funds internationally have mandates or investment guidelines to only invest in “AAA” rated government bonds and if these countries bonds were downgraded, they would be forced to sell those bonds en masse. This would likely see a crash in the already very overvalued government bond markets and see long term interest rates rise quickly and sharply.

The creditors of the US in Russia and China have rightly criticized the ratings agencies for their highly irresponsible practices in recent years and are increasingly nervous about their US denominated assets.

Ratings agency Standard and Poor’s in January downgraded Spain’s sovereign debt rating to “AA+” from “AAA” in January, citing insufficient means to deal with weak growth and a ballooning budget deficit. As they did the sovereign rating of New Zealand. The fiscal position in the UK and US is arguably much worse than in these two countries (Martin Wolf of the Financial Times recently said that major US banks, with their humongous Wall Street liabilities, are insolvent) and thus it seems inevitable that the UK and US will be downgraded in the coming months.

If the US is downgraded, then in effect the reserve currency of the world is being downgraded and this has huge implications for the international monetary system. Not surprisingly there have been op-ed pieces in the Financial Times and the Wall Street Journal calling for a return to some form of gold standard.

The governments of the world are nationalizing and socializing the meltdown in the shadow banking system and the international system with potentially disastrous consequences for us all.

Conditions are set to get markedly worse before they get better and the experience of Argentina and other previously wealthy South American countries may be instructive. The IMF is called in and there are structural adjustments, social services are affected or discontinued, banks nationalized, savings inaccessible, food and energy insecurity rise.

This is a potential reality for large western economies, especially if governments keep trying to inflate their way out of the current crisis. This is leading to massive currency debasement and will potentially lead to very significant stagflation and maybe even what could be called hyper stagflation.

Now more than ever, it is essential that individual savers and investors, companies, pension funds and sovereign wealth funds have an allocation to and directly own actual physical gold bullion. Paper exchange traded funds with all the attendant counter party, custodian, sub custodian, auditing and indemnification risk are speculative trading vehicles and not physical gold.

In these unprecedented economic times, it is irresponsible and extremely high risk not to have an allocation to gold bullion in an investment portfolio.

Disclosure: no positions

==========================================

My Note: No Positions??? Mr. O’Byrne I think you need to follow your own advice above! Here is where I buy my Bullion, get one free gram of Gold just for opening an account! Catch the New Bull! – Buy Gold Online – Get 1 gram free! – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

==========================================

Is Gold the only salvation from this Financial Armageddon? – MineWeb

Source: MineWeb

Indications are that the global financial situation could yet get far worse before it starts getting better – particularly in Europe – and gold may again prove to be the only real way of protecting wealth in a continuing global financial meltdown.

Author: Lawrence Williams
Posted:  Monday , 16 Feb 2009
LONDON – 


“It ain’t over ’til its over” is one of the best known quotations from baseball catcher and coach Yogi Berra and as the global financial crisis unwinds it is very apposite yet again.  We ain’t anywhere near the end yet and possibly the worst is yet to come as far as European banks in particular are concerned.  Markets have breathed sighs of relief as various banks have been bailed out and stimulation packages are being approved if not already implemented. 


But, one gets the feeling that any relief is premature.  The debt situation in a huge number of debtor nations – virtually the whole of Eastern Europe falls into this category – is dire and has not really yet fallen into the sights of the investment world – but bankers must be quaking in their shoes as surely they are aware of the potential financial Armageddon that still lies ahead. 

And this time it is the already shaky Western European banking sector that is most at risk.  US Banks, accused of starting this all, maybe far less vulnerable to the times ahead.  True the US financial sector may have got us into this mess, but European bankers followed suit and, in the event, may be shown to have behaved far more recklessly than their American counterparts.  It would seem that some of the potential shortfalls being faced would be beyond the financial ability of Central Banks, Governments and transnational agencies like the IMF to sort out.  The system is like a house of cards.  One major failure could bring the whole house tumbling down. 

This is the kind of situation that leads to global nightmares – wars even.  Radical extremists get elected to positions of power – as with the rise of National Socialism in Germany after the crash of the Weimar Republic with its hyperinflation.  We could be in for a very sticky time ahead as the real implications, and depth, of the financial meltdown catch up with us. 

The problems ahead may not be beyond the wit of man to devise a solution which can ‘save the world’, but that is unlikely to come from UK Prime Minister Gordon Brown who appears to have laid claim to this cachet in a freudian moment of rhetorical madness.  Don’t forget this is the same Gordon Brown who decimated the UK’s gold reserves by selling half of them off (395 tonnes) at gold’s low points from 1999-2002 – amounting to some $12bn at today’s prices – a sum the UK treasury would give its eye teeth for in the current financial crisis, although this is small beer relative to the sums squandered by the UK banks.  But it is an indicator of Gordon Brown’s acumen, or lack of it, in dealing with global financial trends. 

Indeed Gordon Brown’s thinking is probably echoed by many others in the European and perhaps the US financial hierarchy which doesn’t bode well for any rescue package that will actually work to stem the flow of toxic debt which has built up all around the world and may almost certainly amount in total to a greater sum than all the world’s financial reserves combined,  But then that is the nature of banking.  It only takes a run on almost any bank to bring the whole institution crashing down, and to allow any country to fail – and there are signs that the European Central Bankers may let some Eastern European states go under, thus triggering a domino effect of defaults worldwide, to bring the world banking system to its knees – or worse.  There are even fears that past high flyers like the Irish Republic could be forced to default on its debts, and undoubtedly the situation for, say, the Baltic states is far worse still. 

What solution is there out there.  Printing money on an unprecedented scale will expose the world to huge inflationary pressures for years to come, but this may be the only way forward using more conventional solutions.  Perhaps a huge revaluation in the price of gold could help bolster some treasuries and bring some confidence back into the system.  And, as with any bank run it is confidence which is needed to stem the tide, not necessarily actual money! 

But where does all this leave the investor?  Not in a happy position.  The logic of further financial collapses and bank failures would be to knock the markets down and down, which in turn takes wealth out of the system and decimates pensions upon which an increasingly aging society is dependent. 

Buy gold may be an answer to protect oneself, but as we saw last year, gold too can be vulnerable as in times  of reduced liquidity funds and individuals have to sell any liquid assets to cover their positions.  But then gold is probably not as vulnerable as other assets – again as we have seen over the past year.  Those who were invested in gold at the beginning of 2008, for example, and did not sell during the year, at least maintained the value of their holdings while virtually all other investment options crashed, although this was not true of most gold stocks. 

Now we are seeing professional and institutional investors moving into gold in a big way just to try and protect their, and their clients’  wealth.  As we have pointed out here frequently, gold ETFs are seeing an unprecedented inflow of funds, although there are those out there who would say it is better to hold physical gold than any form of paper gold because of a growing distrust of financial institutions and paper solutions. 

And perhaps rather gold than other precious metals – notably silver.  Silver would be sure to be dragged up on gold’s coattails, but perhaps not as much  this time – even though history tells us that silver’s volatility leads it to perform better than gold in percentage terms on the upside and worse on the downside.  We are in a different situation with silver not really a monetary metal any longer.  Industrial demand pressures on silver may well mitigate any price rises here. 

Gold’s performance, though, is perhaps also dependent on investment demand outstripping a fall off in the jewellery market and an increase in liquidation of such holdings into the scrap sector.  If the big Asian economies like India and China, where mark-ups on gold jewellery are minuscule compared with the West, falter significantly then reduced demand and increased supply from this sector will need to be soaked up by the investment sector.  At the moment this seems to be capable of doing this hence the recent gold price strength, but unless sentiment changes in India in particular, where buyers seem to be waiting for lower prices, the fall in gold purchases there may limit global gold price growth.  If liquidity becomes a problem in the North American markets again, this could also dent upward movement. 

But overall, physical gold, gold ETFs and selected gold stocks would seem to be the best wealth protectors out there.  As commentators have pointed out, prices may remain relatively volatile, but currently the overall price trend tends to be upwards movement, followed by stabilisation, before the next upwards resistance levels are tested.  Gold does look to be steadily climbing back towards the psychological $1,000 an ounce level but it has had trouble sustaining increases beyond this level in the past.  Perhaps it will be third time lucky for the gold bulls.

=================================

My Note: Prudence dictates at least 10% of your portfolio should be in Gold. Personally, I have that and also a lot of my discretionary funds invested in precious metals Stocks, ETF’s, Bullion…jschulmansr

Here is where I buy my Bullion, get one free gram of Gold just for opening an account! Catch the New Bull! – Buy Gold Online – Get 1 gram free! – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

=======================================

Nothing in today’s post should be considered as an offer to buy or sell any securities or other investments; it is presented for informational purposes only. As a good investor, consult your Investment Advisor, Do Your Due Diligence, Read All Prospectus/s and related information carefully before you make any investments. –  jschulmansr


GLD

GLD, , ) GLD . These rocketed a startling 13.7% to 985 tonnes, setting records each day.

XAU

Delayed quote dataHUI, , ) added 1.36% to 311.16. The stock market, in case you missed it, lost ground.

Commentary: Gold’s gains for week catch bugs’ interest

By Peter Brimelow, MarketWatch
NEW YORK (MarketWatch) — Something was indeed stirring in the precious metals pond, as I reported a week ago. Key investment letters say it still is. See Feb. 8 column


Here is where I buy my Bullion, get one free gram of Gold just for opening an account! Catch the New Bull! – Buy Gold Online – Get 1 gram free! – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com


==================================

Share this:

  • Share on Reddit (Opens in new window) Reddit
  • Share on Facebook (Opens in new window) Facebook
  • Share on LinkedIn (Opens in new window) LinkedIn
  • More
  • Share on X (Opens in new window) X
  • Share on Pinterest (Opens in new window) Pinterest
  • Share on Tumblr (Opens in new window) Tumblr
  • Print (Opens in new window) Print
  • Email a link to a friend (Opens in new window) Email
Like Loading...

Gold’s Big Test – Will it Pass?

12 Thursday Feb 2009

Posted by jschulmansr in 10 year Treasuries, 20 yr Treasuries, Bailout News, banking crisis, banks, Barack Obama, bull market, capitalism, central banks, China, Comex, commodities, Credit Default, Currencies, currency, Currency and Currencies, DGP, dollar denominated, dollar denominated investments, economic, Economic Recovery, economic trends, economy, futures markets, GDX, GLD, gold, Gold Bullion, Gold Investments, gold miners, hard assets, How To Invest, How To Make Money, hyper-inflation, IMF, inflation, Investing, investments, Jschulmansr, Junior Gold Miners, Latest News, Make Money Investing, market crash, Markets, mining companies, mining stocks, palladium, physical gold, platinum, platinum miners, precious metals, price, prices, producers, production, rare earth metals, recession, silver, silver miners, small caps, spot, spot price, stagflation, Stimulus, Stocks, TARP, The Fed, Today, U.S. Dollar, uranium

≈ 1 Comment

Sorry for the late post today, as I am writing gold closed today at $949.20 up another $4.70 oz. We are now at Gold’s big test, if it can successfully clear and close over $950 -$960 oz. then ther is nothing stopping it to go for a new test of the all time highs. Today’s action was a feint like a boxer about to deliver the knockout punch! However a word of caution if Gold fails after 2-3 attempts at clearing the $950 level then a retracement back to the $875-$890 level will occur. It will consolidate and then come back up to retest the $950 level. Personally however, in my opinion I think this is it the 2nd successful close over $940, I think we are getting ready to see Gold go back and test all time highs. If you hurry you can still get aboard! – Good Investing! – jschulmansr

==================================

Catch the New Bull! – Buy Gold Online – Get 1 gram free! – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

======================================

Stocks Are Doomed, Only Cash or Precious Metals May Survive – Seeking Alpha

By: Doctor O of Sell The Rally


President Obama, his administration, and the Democratically controlled Congress are working as quickly as possible to spend as much money as possible on their constituent base, to consolidate their stranglehold on power. There is still no bank rescue plan, nothing in the “stimulus” bill to create or even slow job losses, and seemingly no understanding about the enormous amount of bad debt that is rapidly losing value and destroying the financial system from the inside out.


=============================

Catch the New Bull! – Buy Gold Online – Get 1 gram free! – Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com

=================================

Will Gold Hit $1,000 – Seeking Alpha


Gold prices broke out Wednesday and traded above $940/ounce. This is a new 6-month high! In my article last week, on 2/4/09, I said:


Catch the New Bull! – Buy Gold Online – Get 1 gram free! – Just open an Account, Buy Safely, quickly, and at low prices, guaranteed! – Bullion Vault.com


In the three months ending January 31, SLV led its benchmark index by nearly 25%, trumping PowerShares’ DB Silver offering, DBS, by a narrow 1.25%. If analyst predictions play out, the demand for silver could continue to grow in upcoming weeks, even as a dismal holiday season for jewelry persists well into the new year. In a recent report, UBS upped forecasts for both silver and gold, citing expectations of speculation and investor interest, as uncertainty still reigns in U.S. markets.

Supporting the hypothesis that the flight to precious metals still results from investor uncertainty is UBS strategist John Reade, who noted that “purchases of physical gold have jumped over the past six months as investors’ fears about the current financial crisis and the possible outcomes from government efforts to support banks and economies have intensified.” UBS also estimates that investor interest in precious metals such as gold will double in 2009, compared with 2007. If this prediction plays out, gold could reach an average of $1,000 before interest wanes.

Shares of SLV track the spot prices of silver and are backed by physical silver reserves. On February 3, New York–based SLV announced that the bullion holdings for the fund rose 77 tons, approximately 1%. This increase puts the fund at a record 7,530.2 tons of bullion, up 11% since January 2. While other factors come into play during the intraday trading of SLV shares, increasing stocks of bullion underscore the growing interest that SLV is seeing in 2009.

Futures, currency and commodity prices are extremely volatile and unpredictable, so understanding the reasons behind silver’s recent spike is an important step in avoiding the swell and vacuum of SLV’s swings. As currency concerns continue to plague investors worldwide, an increasing number of people have turned to silver as a “why-not” alternative to investing in unpredictable notes. India, whose citizens seize silver as a tangible alternative to currency, imports an average of 3,000 tons of silver per year. The Economic Times recently reported that banks may not be able to import regular amounts of silver in the future, a factor that could drive silver prices there drastically higher in black market arenas.

So what makes SLV stand apart from the ever-expanding sea of commodity ETF choices? Its track record, size, and liquidity are all comforting factors for investors looking to jump into the silver fray. With 245 million shares outstanding and an average of 6 million shares traded per day over the last three months, SLV simply dwarfs peers such as DBS. Launched in January 2007, DBS has a three-month average daily trading volume of nearly 200,000—a factor that makes SLV a more liquid choice in white-knuckle times.

Investors should also be wary because while SLV tracks the spot price of silver, other important factors come into play during the intraday trading of the ETF. In addition to reflecting the price of physical silver, SLV also takes into account counterparty risk and the ever-changing emotions of investors in the open marketplace. While the silver is likely “there,” the ratings on even the most venerable of banks—like SLV keeper Barclays—could come into question in perilous economic conditions. Success in the fund is also contingent on the increasing price of silver. Placing funds in SLV is not the same as under the mattress—management fees and “iShares Silver Trust expenses” are exacted by the issuer on a regular basis, slowly eroding the value of one’s investment over time, if the price of silver does not continue to rise.

The longer the economic stimulus plan is stripped and scrubbed across the floor of the Senate, the more investors could continue to pile into a tangible investment like SLV until the storm passes. When the outcome becomes clearer, one-tune investments like SLV may become a more proportionate segment of portfolios and lose steam as the attention that has prompted their rise refocuses on other sectors.

=============================================

Will Gold Reach $5000 an Ounce? – Seeking Alpha

By: Mark O’Byrne of Gold and Silver Investments


Gold surged a further 3.3% yesterday to $942.45 (as did silver) as worries about the US and global financial system and economy continue to grow and governments print money on an unprecedented scale to combat the economic crisis. Asian and European stock markets are again under pressure this morning.

The strong close above $930/oz yesterday should see us once again challenge the record highs of $1,003/oz seen last March (March 17th) when Bear Stearns collapsed.

We have since had a long period (nearly 12 months) of correction and consolidation and thus a solid foundation has been built from which the next leg of the bull market will likely be launched. Our forecast at the beginning of the year for gold to rise as high as $1,250/oz looks increasingly conservative.

Gold Surges to New Records in Euros and Sterling as Crisis Deepens

Gold continues to surge to record highs in other major currencies (the London AM Fix this morning was at $944.00 USD, £666.33 GBP and €737.04 EUR. Worries about the health of the financial system and economy in the UK and EU are leading to weakness in the euro and sterling that has seen them fall in value versus gold. Gold has surged to €737/oz and over £666.33/oz (see charts below).

Gold to Reach $5000/oz According to Respected Goldcorp Founder

The respected founder of Goldcorp (GG), Rob McEwen told Bloomberg how he sees gold rising to as high as $5,000/oz in the next four years. Goldcorp is the second largest gold mining company in the world by market capitalization.

As governments increase the money supply to combat recession, bullion will more than double to $2,000 an ounce by the end of next year. “Politicians around the world are listening to cries from their electorates and they’re giving money to all callers,” McEwen said yesterday.

McEwen has more than $100 million in gold investments and said he also has a “big, big” holding in bullion. McEwen said he started buying bullion in August 2007, at the beginning of the subprime mortgage crisis. “I realized we had reached an inflection point regarding money,” McEwen said. “It was all about protecting money, and gold served that purpose.”

The recent trend of fiat currencies falling vis a vis gold looks set to continue for the foreseeable future. McEwen’s bold prediction looks outlandish now (as did predictions of gold at over $1,000/oz in 2001) but given the confluence of extremely strong fundamentals, gold will likely rise to levels in the coming years that seem unfathomable today.

====================================

My Note:- I think a more realistic view would be Gold at $2500 to $3000 in next 2-3 years. However if everything goes to H*** in a Handbasket then yes $5000 and more! – Good Investing! – jschulmansr

Nothing in today’s post should be considered as an offer to buy or sell any securities or other investments; it is presented for informational purposes only. As a good investor, consult your Investment Advisor, Do Your Due Diligence, Read All Prospectus/s and related information carefully before you make any investments. –  jschulmansr

=======================================

Silver The Other Precious Metal – Seeking Alpha

By Don Dion of Fidelity Independent Advisor


In a global economic crisis for which the media has seemingly exhausted its cache of negative adjectives to describe the meltdown, one is hard-pressed to find an example of success in the quagmire that has become the marketplace. When scanning the ranks of the ETF Sector Momentum Table, however, one fund’s sweeping forward progress makes it a glinting example among its peers. iShares’ Silver Trust (SLV) vaulted from the No. 60 position in the rankings on December 2, 2008, to the No. 14 spot on February 3, 2009. If precious metals continue to outpace agricultural commodities, and the “flight to safety” extends into a probable “odyssey toward conservative investing,” SLV will be an interesting fund to track in upcoming months.


“We’ll wait for GLD to confirm that $88 will hold. Above $90, we should see more buyers coming in. March in-the-money calls are reasonably priced. AEM is another good vehicle to play gold. Although it is very volatile, it is a momentum stock and can run up fast!”

GLD successfully tested $88 and closed above $90 on Tuesday. On Wednesday, it jumped on high volume, more than twice the average volume!! GLD closed at $92.29, up +2.31%. AEM also did well, gaining +6.58%, or $3.48, finally breaking above $55.

click to enlarge

GLD

GLD added $2.08 to close at $92.29. It jumped on very high volume Wednesday. It closed just below the resistance at $92.5. This is only a soft resistance. The nearest hard resistance is between $95-$97.5.

Compared to the stock market, which had been treading water in a tight range since November last year, GLD had done much better. We can see a big divergence in this comparson chart:

The SPX has basically traded flat. On the other hand, GLD has risen nearly +30%, from $72 to $92!

GLD’s chart is still very strong. Its daily MAs are curving higher and still holding a bullish formation. The MACD is also turning up. I think GLD can easily revisit $100 within the next few months, which means gold can retest $1,000, and likely go above. Again, March “within-the-money” calls are reasonably priced. If GLD goes to $100 within the next few weeks, these options will probably double.

Good day and HappyTrading! ™.

Disclosure: no positions

========================================

My Note: Yes! Gold will hit $1000 in fact will go and test the $1050 level. I n the case above the writer Mr Wang did an excellent forcast but notice no positions! I hope he follows his own advice and jumps on either (GLD) or if you want more bang for the buck (DGP). My disclosure I am Long (DGP), and (GLD). Also Long Bullion, Large, mid-tier and junior mining shares in the whole Precious metals spectrum including Rare Earths and Strategic Metals. Also Don’t forget silver as the next article points out. Finally do not forget Platinum and Palladium their time is coming too, mark my words! – jschulmansr


Home foreclosures are accelerating. We await a tidal wave of personal and corporate bankruptcies and the implosion of the commercial real estate market that will trigger more massive losses in the banking system.

In short, I have no confidence in the U.S. Government to “solve” the current depression. In fact, they will no doubt make it worse by socializing the economy and spending money obscenely. No wonder the only thing that’s working is precious metals.

I cannot consider investing in any stock until this virulently anti-business administration is either voted out of office or starts to see things more rationally.

The Last Depression, Coming to a Town Near You

Keep Away from U.S. Stocks as They Cascade Down

Gold Threatening to Break Out To New Highs Against the U.S. Dollar

Share this:

  • Share on Reddit (Opens in new window) Reddit
  • Share on Facebook (Opens in new window) Facebook
  • Share on LinkedIn (Opens in new window) LinkedIn
  • More
  • Share on X (Opens in new window) X
  • Share on Pinterest (Opens in new window) Pinterest
  • Share on Tumblr (Opens in new window) Tumblr
  • Print (Opens in new window) Print
  • Email a link to a friend (Opens in new window) Email
Like Loading...

Resurgence! Gold Demand is Picking Up!

06 Friday Feb 2009

Posted by jschulmansr in bull market, China, Comex, Currencies, currency, Currency and Currencies, dollar denominated, dollar denominated investments, economic, economic trends, economy, Forex, Fundamental Analysis, futures, futures markets, GDX, GLD, gold, Gold Bullion, Gold Investments, gold miners, How To Invest, How To Make Money, hyper-inflation, India, inflation, Investing, investments, Latest News, Make Money Investing, Markets, Michael Zielinski, mining companies, mining stocks, Peter Grandich, physical gold, platinum, platinum miners, precious metals, price, prices, producers, production, silver, silver miners, small caps, spot, spot price, stagflation, Stimulus, Stocks, Technical Analysis, Today, U.S. Dollar

≈ 1 Comment

As I write this post Gold is consolidating after another $12 oz rise yesterday, currently off $1.70 at $912.00. Today’s post has some must read articles if you are or are about to invest in Gold. Demand is experiencing a strong resurgence, and all the factors are lining up for a spectacular rally! Time to get aboard the Gold Train! – Good Investing – jschulmansr

======================================

This is where I am buying my Gold Bullion…

Catch the New Bull! – Buy Gold Online – Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

==========================================

Gold Demand Resurges – Seeking Alpha

By: Nicholas Jones of Bourbon and Bayonets

We love to analyze gold in issues of Bourbon and Bayonets, especially with a focus on the macroeconomic issues that are extremely bullish for our favorite yellow metal. The economic crisis and complete lack of competence from our leaders has resulted in a current financial climate that will result in the most fantastic run the price of gold has ever experienced. The quantitative easing around the globe is definitely the greatest single bullish fundamental that will drive gold going forward. It’s not the only reason gold will rise in price, but it definitely carries the most weight.

The thing is, gold is a sort of hybrid investment vehicle. Essentially it’s part commodity part currency. When I discuss things like monetary inflation and the stimulus package, I’m referring to the aspect of gold that acts as a monetary vehicle. I absolutely don’t want to downplay that importance of this notion, but it’s not the whole story. Gold, like all other assets, is affected by supply and demand fundamentals. Monetary issues may be the driving force behind gold, but looking at supply and demand figures can be very telling, especially in the short run. In this article I am going to dig through the recent 3Q global S&D figures released by the World Gold Council. The numbers are very interesting.

Gold Demand Resurges

Gold demand in the 3Q of 2008 was very strong after being weak for several quarters. Identifiable demand was 1,133.4 tonnes. That figure was up 170.1 tonnes or 18% year over year. Valued in U.S. dollars gold demand was $31.8 billion and up 51% year over year. That number is a record and marks a 45% increase from the record numbers set in the 2Q.

The sector experiencing the largest increase was identifiable investment which was up 137.5 tonnes or 56% year over year. Breaking down the identifiable investment, the largest increase in that subset was net retail investment. Net retail investment increased 121% to 232.1 tonnes.

Leading the growth in demand was Switzerland, Germany, India, and the U.S. At this point in the report, the authors made a statement that there were noticeable shortages of bars and coins around the world. We’ve discussed this story extensively at Bourbon & Bayonets. A result of the dealer shortages has been the divergence between the spot and futures price of gold. Please refer to past issues for a more extensive explanation.

Gold ETFs also had a record net quarterly inflow of 150 tonnes. The report mentions that peak inflows occurred after the collapse of Lehman. In the 5 days following the debacle inflows increased by 111 tonnes ($7 billion). Once the treasury market collapses, gold will revert back to its rightful place as the number one flight to safety asset in the world. I would like to put a precaution on using ETFs. When using ETFs to buy gold, you remove one very important element. Physical gold has no counterparty risk. ETFs do. This will become more important going forward from here, but in the mean time just think of what the Hunt Brothers would have to say about PM ETFs.

Moving back to the WGC report, early demand in the 4Q has picked up where it left off in the 3Q. They also mention that gold shortages are expected to continue, de-hedging will continue to abate, and central bank sales will be weak.

[All figures provided by the World Gold Council 3Q Gold Demand Trends report.]

Monetary forces may be the driver in the gold market, but we can use these reports to help with short term expectations. Demand is strong, really strong. There were record figures across the board. On the other side of the story, supplies are tight and will continue to be tight. The players are coming back to the game and this will provide strong underlying support in the gold market going forward. I still hold to my views that gold may test $1000 in the near term, but I believe we’re one correction back to $850 away before we make a run up to $1500.

=================================

My Note: If demand is still increasing then fundamentally upward pressure remains intact. We have probably seen most of the cash starved stock investors, hedge funds, and etc. have already sold their positions to raise cash to offset their losses. Yes, I agree we will see a retest of the $850 level but not until we have made new all time highs in the Gold Markets. Then at that point we will retrace and then I think the next rally will be to $1500 – $2000 oz. level. This is without any major flare-ups in the Middle East or a U.S. debt default. One other potential trouble spot is a small war between China and India over the disputed border areas, especially with India being distracted by growing tensions with Pakistan. If any of those scenarios happen, then Gold can and will easily go to well over $2000-$3000. You heard it here first folks!-jschulmansr

Catch the New Bull! – Buy Gold Online – Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

===================================

Gold’s Performance Relative to Dollar, Yen and Euro – Seeking Alpha

By: Richard Shaw of OVM Group

As gold receives headlines, let’s look at it relative to the three key global currencies – Dollar, Yen and Euro.

Gold is sometimes viewed more as a commodity for jewelry and electronic applications, and at other times more as a quasi-currency. It has an ancient history for both roles. As of late, gold has been taking on more of the alternative currency role.

Paper currencies pay interest, but physical gold does not. As the interest rate on paper currency approaches zero, the short-term opportunity cost of holding gold versus paper currencies becomes minimal (noting, however, that there are storage and security or management costs with gold).

Reasonable proxies for gold and currencies are: gold (GLD), Dollar (UUP), Yen (FXY) and Euro (FXE).

The 3-year weekly chart below uses “price channels” to identify the highest highs and the lowest lows for the twenty prior periods. It also presents a Fibonacci study that essentially marks the levels for an approximate 1/3, 1/2 and 2/3 retracement of the most recent peak-to-bottom price range.

click images to enlarge

3-Year Chart with Fibonacci Study

Theory would say that having retraced 2/3 of the prior peak-to-bottom, the current move is more likely to persevere than not.

One approach to identifying resistance and support levels is to find prior highs and prior lows. Price channels are one way to have a computer generate visual queues to resistance and support levels automatically. Just be sure the historical period for the price channels is what you want. Note also that prior consolidation areas tend to create resistance or support levels. This daily study uses price channels over 20 trailing periods as does the 3-year weekly chart above.

1-Year Chart with Resistance Levels and Trend Lines

Having pierced two resistance levels and flirting with a third shows great strength. The higher bottoms and higher tops is a favorable indication.

Gold is near twenty-year highs, having pierced several key resistance levels since its slide in Q4 2008. Some predict new highs ahead.

Here is a twenty-year monthly chart showing how gold performed on a percentage basis relative to the Dollar, Yen and Euro.

20 years

Gold may reach new twenty-year highs. A trend is a trend, until it is not a trend. On the other hand, every rubber band can only stretch so far.

Investor sense of success in the multi-national recovery programs may divert investor money flows to other asset categories, possibly slowing or capping the advance of gold. Alternatively, investor sense of failure by recovery programs would likely direct more money flows to gold, possibly extending its advance.

10 years

5 Years

1 Year

4 Months


Sometimes it is more informative to look at discrete periods of time, such as successive individual calendar years or groups of years, rather than cumulative periods of time. That is because of the persistent impact by past periods on cumulative returns, whereas discrete periods start fresh without the quantitative effect of the past.

The following charts show 3-year monthly performance for eight successive discrete periods beginning with 1999. Gold has been the superior performer in seven of the eight periods. The question remains, when has it gone high enough. So much may depend on the conduct of governments in the near-term.


3 Years Beginning 1999

3 Years Beginning 2000

3 Years Beginning 2001

3 Years Beginning 2002


3 Years Beginning 2003

3 Years Beginning 2004

3 Years Beginning 2005

3 Years Beginning 2006

Disclosure: The author holds a small allocation in gold via the ETF, symbol GLD, with a 10% persistent trailing stop.

================================

My Note: Can’t forget Silver!

Long-Term Trend in Investment Demand for Silver – Seeking Alpha

By: Michael Zielinski of Gold and Silver Blog

In a previous post, I reviewed the amount of silver bullion sold by the United States Mint during 2008. With this post, I will take a longer term look at silver demand, which highlights the absolute explosion in demand which has occurred in recent years.

The supporting data for the charts included with this post comes from a new section of Gold and Silver Blog which collects the US Mint Silver Bullion Sales data since the inception of the program in 1986. You can visit the page to find the monthly sales figures for any date from 1986 to present. The section also calculates the approximate silver bullion value of each period’s sales based on the average monthly price of silver.

Silver Bullion Sales in Ounces

Here’s a chart summarizing the total ounces of silver bullion sold by the US Mint each year since 1986. (Click on the chart for a larger version.)

During 2008, the US Mint sold 19,583,500 ounces of silver through its bullion program. As explored previously, this marks an all time high for the program. It represents an increase of more than 98% from the prior year, and an increase of 92% from the previous all time high reached in 2002.

One important thing to note when considering the magnitude of the increase for 2008 is that the number of ounces sold could have been much greater. The US Mint suspended silver bullion sales during February before resuming sales on a rationed basis. When the rationing first began, one dealer claimed that he could have sold 500,000 ounces of silver per week, but was only allocated 100,000 ounces.

2008 Silver Bullion Sales in Dollars

Here’s a second chart which illustrates the explosion in demand for silver in even more dramatic fashion. The chart shows the approximate dollar value of silver bullion sold by the US Mint each year. As mentioned, this was calculated based on monthly silver bullion sales and the average monthly price of silver. (Click on the chart for a larger version.)

Silver Bullion Sales Value Chart

During 2008, The US Mint recorded silver bullion sales of approximately $286,451,715. This marks an all time high and an increase of 114% from the prior year, which was also the prior all time high.

The magnitude of the increase is more pronounced when compared to silver bullion sales from earlier years of the program. Throughout the majority of the 1990’s, the US Mint was selling less than $30 million worth of silver each year. The year for the lowest value of silver bullion sold was 1996 with $17,434,050. During 2008, the US Mint recorded monthly sales exceeding this level for ten out of twelve months.

Silver Bullion Sales and the Price of Silver

But what about the price of silver amidst this explosion in demand?

Here’s a third chart which plots the value of US Mint silver bullion sales from the last chart, together with the average annual price of silver for each year. (Click on the chart for a larger version.)

Silver bullion sales increased from a low of $17,434,050 to last year’s high of $286,451,715 representing an increase of 1,543%. The average annual price of silver increased from a low of $3.95 per ounce to last year’s high of $14.99 representing an increase of 203%. While this is a respectable gain, it pales in comparison to the increase in demand.

Everyone has been waiting for the disconnect between the demand for silver and the price of silver to resolve itself. Will it finally happen in 2009?

Disclosure: Long physical silver.

===================================

My Note: Me too! Long Physical Silver Too!-jschulmansr

Catch the New Bull! – Buy Gold Online – Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

===================================

Now from Peter Grandich:

I spend almost no time on conspiracy theories. However, a couple events today made me feel that 1 + 1 = 3 today.

We start the day with horrific economic news. Retails sales fall sharply and the weekly unemployment number comes in higher than any forecasts. The stock market falls over 100 points in the first hour and once again is testing key support around 7900 (I’ve mention this area as key several times recently). Just when it appears we’re going to break support, Tout-TV “reports” the government may be suspending the “mark to market” rule and there will be a big announcement Monday from the Treasury. The “Don’t Worry, Be Happy” crowd did their thing and Tout-TV filled the air with “Happy” people praising this expectation and how well the market is handling bad news today.

So how did 1 + 1 = 3 today? It was publicly announced that the “Working Group on Financial Markets“, better known as the Plunge Protection Team (PPT) met for the first time today under the new administration. After seeing the horrific economic news and believing tomorrow’s unemployment numbers could be real bad, one could envision a sharp sell off today that could have been followed be another one tomorrow. That could have left the stock market teetering going into Monday’s “big” announcement. Hmmm….

Despite poor economic news, the treasury market continued to weaken. As any one asked how all the governments around the world are going to fund all the debt being created for their bail-outs and stimulus packages? Hmmm…

There are two things you can’t keep down these days, a good man and gold. If we can clear $940 on a closing basis, I think we’re off to the races. Gold rises on up days in the U.S. Dollar and falls on days the dollar is down. Hmmm…

Oil – For three straight weeks we’ve had bad supply numbers for oil but it still manages to keep its head above $40. This has to be frustrating for the bears. Next Wednesday’s inventory number should be big as if we continue to build more than expected, oil may not hold. But if we see a drawdown, we could see a rally of $5 to $10 in rather short order.

U.S. Dollar – Sideways despite rising U.S. interest rates. I love the Canadian dollar (its people but not the Vancouver Canucks).

Northern Dynasty Minerals has run up sharply but is very overbought short term. Some profit-taking and consolidation would be healthy.

======================================

Bipolar Gold – Nichols onGold.com

By: Jeffrey Nichols of NicholsonGold.com

With the price of gold lurching first one way then the other, it looks like the market has been suffering from bipolar disorder.  I expect this split-personality behavior, characterized by extreme price volatility, to continue for some time to come with big swings up and down — but, importantly, around a rising trend with support levels moving up step-wise over time.

goldbars11In short, gold is heading much higher, but not without more struggle and occasional disappointment for those looking for a speedy ascent.  Further out — over the next year or two — I have no doubt that gold will move to new historic highs well above the $1030 level touched a year ago March.

The principal engine of gold’s ultimate ascent is the continuing rapid pace of monetary expansion – in part necessitated by a trillion-dollar stimulus program in the United States — and the acceleration in U.S. price inflation will surely follow sometime in the next year or two.

There are at least three other less certain but entirely possible developments any one of which could touch off a real panic in the gold market and carry the metal’s price to levels most would consider unimaginable:

  • First, another large-scale financial catastrophe in which one or more financial institutions seemingly suddenly need hundreds of billions of dollars more in government bail-out funds.
  • Second, a growing reluctance on the part of foreign central banks and other major investing institutions to continue underwriting the U.S. federal budget deficit without a significant rise in nominal U.S. interest rates.
  • Third, a run on the U.S. dollar, though it is hard to imagine where dollar holders would run since other currency markets (and certainly the gold and other precious metals markets) are not large or deep enough to absorb a major shift in currency preferences and when other major currencies are also losing creditability as reliable stores of value.

History Lesson

It is instructive to examine the forces that held gold back during the past year for clues to the metal’s future path.

Much of gold’s weakness during the past year and its inability to sustain periodic price advances was due to the indiscriminate selling of commodities-related investments by hedge funds, other institutional players and some wealthy families in order to raise cash, increase liquidity, cover big losses in equity and other asset markets.

Often these institutional sellers were not holding individual commodities but baskets or indexes that included gold – so gold got dumped along with everything else.  In other words, gold was sold not because it was singled out as an unworthy holding but because it was a component in the indexed baskets of commodities held by many hedge funds and institutional traders.

In addition, the decline in inflation and inflation expectations due to the fall in oil and other commodities prices and the increasingly gloomy economic outlook dampened demand for gold among some who look to the metal as an inflation hedge.

Despite all of this, one must still acknowledge the yellow metal’s staying power and relative performance as a store of value during a tumultuous period for the world economy and the sizable loss of value in other asset classes.

Indeed, gold has done rather well compared to the $30 trillion loss in world equity market capitalization, the unfathomable loss in real estate values, and the $1.2 trillion of losses and write-downs on worthless assets held by banks worldwide (IMF estimates).  Measured in U.S. dollars, gold is now up a few percent from the end of 2007 – but it is at all-time highs against nearly all of the major currencies.

Bipolar Investment Demand

By late 2008, the wave of commodity disinvestment had come to an end.  Simply put, the commodity holdings of hedge funds and other large-scale players had been largely depleted — and, to the extent that these were actual physical positions, the gold has moved to stronger hands.

Recent data from commodity futures exchanges confirm that the liquidation of long gold futures positions has not only ended but has been replaced with some fresh buying.  In the week ending January 27th the net long position increased by 49 metric tons to reach a total of 564 metric tons (18.1 million ounces).  This compares with a net long position of 516 tons (16.6 million ounces) at the end of last year and a recent low point of 213 tons (6.85 million ounces) in mid-November.

An even more encouraging indicator of gold’s future price is the continuing strength of investor interest among retail investors and conservative institutional investors wishing to hold physical metal.  Importantly, these buyers are not traders looking for quick gains but many are simply scared individuals, families, and prudent institutional investors seeking to protect their wealth, their savings, and their retirement nest eggs (for themselves or their clients).

One need only look at the holdings of exchange-traded funds (or ETFs) such as the SPDR Gold Shares ETF traded on the New York Stock Exchange.  Holdings of gold bullion on behalf of SPDR Gold Shares investors reached an all-time high of 859.5 tons (27.6 million ounces) on February 4th.  This compares with 780.23 tons (25 million ounces) at the end of last year and 630 tons (20.3 million ounces) in early 2008.

Without doubt, the introduction of SPDR Gold Shares just over four years ago (along with a number of smaller exchange-traded gold funds in other global markets) has been an important structural change in the gold market facilitating the participation of individual investors as well as institutions, some of which have prohibitions from direct purchase and ownership of physical metal.  Importantly, ETF gold investors have become a force in the market with total ETF holdings now exceeding the COMEX net long position.

Great Expectations

I remain bullish on gold because — even as the global economic recession deepens — governments will find the only way out of this mess is to print more money.

It’s not just the U.S. monetary authorities pumping up the money supply, though that would be enough to boost the U.S. dollar price of gold.  Their counterparts in every major economy – including the United Kingdom and the Euro zone, China, Russia, Japan and on and on – are doing likewise.

We have never in the history of money seen such an expansion in its supply without, after a period of time, a rapid deterioration in its value.  More than any other factor influencing the gold market, it is the inevitable devaluation of money and the corresponding rise in price inflation that will propel gold skyward in the next few years.

As sure as day follows night, reflationary monetary policies — however necessary — have long-term implications for global inflation.  Typically, monetary creation affects price inflation with a lag of six months to a couple of years or more . . . so it may be some time before inflation is recognized as a serious problem.  But gold prices have shorter lags and, in fact, have already begun moving up long before rising inflation becomes apparent or worrisome.

As I have said before, with the right confluence of economic and geopolitical developments we could see gold break through $1500, then $2000, and possibly still higher round numbers in the next few years.

Not Without Risk

Despite expectations of much higher gold prices this year and beyond, it would be wise to remember that gold remains volatile and vulnerable.  We are in an unprecedented environment with daily evidence of a deteriorating U.S. and global economy, where policy makers are employing powerful, yet untested, tools to repair a broken economy, and politicians cannot be trusted to do all the right things.  In this environment, we could still get a quick sell-off that would bring us back to support levels well below recent prices.

That said, there are some specific factors that could trigger a sizable correction in gold prices in the next few months:

First and foremost, a temporarily stronger U.S. dollar vis-à-vis the euro:  The European Central Bank is a few steps behind the Federal Reserve in lowering short-term interbank lending rates.  As the ECB catches up by lowering interest rates in two or three steps over the next few months, the dollar will likely pop up briefly each time – and, each time, a stronger dollar could precipitate a sell-off in gold as it did in January and several times last year.

Second, weakness in Indian gold demand:  India, the world’s largest gold-consuming country with imports last year of 720 metric tons (23.1 million ounces), has seen a sharp decline in gold imports.  The Bombay Bullion Association reports that gold imports plunged more than 90 percent to roughly 1.8 tons in January from 24 tons a year earlier.  Imports are down largely in response to the record-high rupee-denominated price of gold.   High prices are discouraging demand and eliciting large-scale sales of old jewelry from profit takers, sales that are refined locally into bars and re-enter the market displacing imported metal.

Sources in India say the recent data exaggerates the situation and expect at least a partial recovery as gold buyers adjust to the high and rising price for the yellow metal.  They also say that holiday and wedding-related demand, which is an important component of total consumption should pick up shortly.  In addition, the new government program of offering small gold coins at rural post offices could be a spur to gold buying.

But if Indian buying does not pick up soon, there could be more metal available in world markets to satisfy the rise in U.S. and European investment demand and correspondingly less upward pressure on the price of gold.

Coming Soon to a Blog Near You

In subsequent posts, I will take a look more closely at some of the other variables that could influence gold – for better or worse — in the months ahead: Central bank and IMF gold policies and prospects, the economic and political situations in China, Russia, and Saudi Arabia – and, of course, we’ll continue to comment on the unfolding economic crisis and policy response in the United States.

=============================================

GLD Working While S&P Is Floundering  – OTC Journal

Earlier this week I published two buy recommendations- GLD at $88.47 (the ETF for Gold, which is the easiest way to own it), and EZA- the ETF of the Dow like stocks of South Africa.

My view- GLD is probably headed to $100 in pretty short order, which equates to $1,000 per ounce in gold. EZA should mirror the movement in Gold as South Africa industry is very mining focused, and has the longest established and some of the most prolific producers. And, as importantly, EZA pays a cash dividend of 6%, which significantly enhances your total return opportunity.

The S&P and DOW are both stuck in trading ranges since coming off the November lows. There’s lot of talk about the DOW being skewed. 9 of the 30 DOW stocks are trading below $10 per share which has never happened – courtesy of the financials. Remove the financials from the DOW and the S&P 500, and you have a much healthier picture. Tech is trading up along with Small Cap Value. There is more underlying strength than the major indexes are indicating.

I want to take another look at my published ideas from earlier this week. Here’s a longer term look at GLD, the ETF for Gold. Gold made the $1,000 level last March, and then fell all the way be to $700 as the recession gained strength.

Since making it’s bottom in November along with all the equities, Gold has behaved like a champion. It’s made a serious of higher lows and higher highs for the last 3 months. More importantly, Gold is butting up against the downtrend line from the top made last March. A solid break above $92 would suggest a major breakout, and we’re very close right now.

So, let’s turn to my arbitrage idea if you like Gold. EZA- the South Africa ETF. South Africa is one of the largest and longest established mining centers in the world. Nearly 50% of the holdings in the ETF are basic materials companies. The average PE ratio in the portfolio is 8.79.

EZA is not as close to a breakout relative to GLD, which suggests a bit of a lag factor in the idea. I recommended this South Africa fund made in December at $34. Yesterday, it closed at $34.36, which isn’t bad when one considers both the DOW and S&P 500 took 10% hits in the month of January. Factored into the total return on EZA is the 6% dividend. This idea is starting to work, but hasn’t really broken out yet.

It probably needs to eclipse the $36.50 to really get into breakout mode. As Gold appreciates, I’m hypothesizing EZA will follow it up. Owning EZA gets you both the dividend and the appreciation.

If you like these ideas, but don’t want to pledge the kind of capital it takes to own a $34 stock or a $90 stock, you might want to consider the options. They are much riskier, but offer a lot of leverage for a little money.

For GLD- the April $90 calls are trading at $6.25- it’s a big time premium, but if GLD finds its way to $100 you’re likely to enjoy a 50% to 100% return. The calls trade under the symbol GLD.DL. If you’re more sophisticated and have a lot of capital, you should consider shorting the puts. It’s a bit trickier and takes a lot of money.

For EZA- The April 35 Calls are trading at about $2.25. That’s a pretty reasonable premium. A $2250 investment gets you 10 calls, and you control 1,000 shares. This call trades under the symbol EZA.DG. With EZA, shorting the puts might be a good strategy as well. If you’ve never done it and don’t understand it, now is not the time to educate on this strategy.

Own either or both- in my view money is flowing to Gold. The dollar is losing steam, and the US is going to have to print a lot of money to spend our way out of this recession, which is favorable for gold. Here’s two ways to make money on that trend.

Home Page : www.otcjournal.com
Email Questions or Comments To: editor@otcjournal.com

======================================

Analysts Pile On The Gold Bull – Gold and Silver Blog

By: Michael Zielinski of Gold and Silver Blog

Gold’s recent move above $900 has analysts scrambling to increase their price targets.

The last time I looked at gold price targets from analysts was in early December, when a similar flurry of activity took place. Morgan Stanley got the ball rolling by saying that gold could reach $1,000 in three years, Merrill Lynch followed with a price of $1,500 at an unspecified date, and Citigroup topped them all by mentioning $2,000.

This time around started in the same way with Morgan Stanley making a timid call for $1,075 gold in three years. From their report: “A globally synchronous and aggressive fiscal and monetary stimulus may be needed to re-inflate the global economy, and we think this continues to present significant upside to gold prices.” For their rhetoric, their target price is ridiculous, unless you consider “significant upside” to be an average 6% gain over three years.

Merrill Lynch chimed in next with their Chief Investment Officer reiterating their prediction of $1,500 gold, but this time with a time frame of 12 to 15 months. Quote from the CIO: “With confidence in currencies shaken to the core, the yellow metal is increasingly assuming the role of “the most trusted currency. We have never seen such a rush to buy gold. It’s bringing in security and it’s still affordable.”

A few days following, both UBS and Goldman Sachs updated their previously underwater gold price targets. UBS raised their 2009 price target from $700 to $1,000. Goldman Sachs raised its forecast of $700 to $1,000 within a three month time frame.

As expressed before, I do not think we have reached the point where these periodic analyst pile ons can be used as a contrary indicator for gold. Analysts are still showing restraint, and for the most part raising their targets simply to keep up with the rising price of gold.

======================================

Catch the New Bull! – Buy Gold Online – Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

That’s All for Now- Good Investing! – jschulmansr

Nothing in today’s post should be considered as an offer to buy or sell or as a recommendation for  any securities or other investments; it is presented for informational purposes only. As a good investor, consult your Investment Advisor, Do Your Due Diligence, Read All Prospectus/s and related information carefully before you make any investments. –  jschulmansr


Share this:

  • Share on Reddit (Opens in new window) Reddit
  • Share on Facebook (Opens in new window) Facebook
  • Share on LinkedIn (Opens in new window) LinkedIn
  • More
  • Share on X (Opens in new window) X
  • Share on Pinterest (Opens in new window) Pinterest
  • Share on Tumblr (Opens in new window) Tumblr
  • Print (Opens in new window) Print
  • Email a link to a friend (Opens in new window) Email
Like Loading...

Can You Sense It? The Calm Before The Storm

03 Tuesday Feb 2009

Posted by jschulmansr in 10 year Treasuries, 20 yr Treasuries, Bailout News, banking crisis, banks, bear market, capitalism, China, Comex, Credit Default, Currencies, Currency and Currencies, deflation, depression, dollar denominated, dollar denominated investments, economic, Economic Recovery, economic trends, economy, Fed Fund Rate, Federal Deficit, federal reserve, Finance, financial, Forex, Fundamental Analysis, futures, futures markets, gold, Gold Bullion, Gold Investments, gold miners, hard assets, How To Invest, How To Make Money, hyper-inflation, India, inflation, Investing, investments, Junior Gold Miners, Latest News, Make Money Investing, market crash, Markets, mining companies, mining stocks, oil, palladium, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, protection, recession, run on banks, Saudi Arabia, Short Bonds, silver, silver miners, small caps, spot, spot price, stagflation, Stimulus, Stocks, TARP, The Fed, Today, U.S. Dollar, Uncategorized

≈ 2 Comments

Tags

agricultural commodities, alternate energy, Austrian school, Bailout News, banking crisis, banks, bear market, Bollinger Bands, bull market, capitalism, central banks, China, Comex, commodities, communism, Copper, Currencies, currency, deflation, Dennis Gartman, depression, diamonds, dollar denominated, dollar denominated investments, economic, economic trends, economy, Federal Deficit, financial, Forex, futures, futures markets, gold, gold miners, hard assets, heating oil, India, inflation, investments, Keith Fitz-Gerald, Marc Faber, Mark Hulbert, market crash, Markets, mining companies, Moving Averages, natural gas, oil, palladium, Peter Brimelow, Peter Schiff, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, protection, rare earth metals, recession, risk, run on banks, safety, Saudi Arabia, Sean Rakhimov, silver, silver miners, socialism, sovereign, spot, spot price, stagflation, Technical Analysis, timber, U.S. Dollar, volatility, warrants, Water

Can you sense it? There seems to be an eerie calm in all of the markets. Could this be the calm before the coming financial storm round 2? Since Gold is considered a safe haven investment in times of financial uncertainty, it would seem to tell us something is about to break wide open. As I enter this post Gold is up $5 oz to $912.50. We saw some retracement yesterday but support levels at $900 oz held. It appears that prices are taking a breather. This comes after an approximate $95 dollar an oz rise in just the past 14 days! As I mentioned in my post from a few days ago It’s Official Gold is in a new Bull Market. 

Quick sample of some recent headlines:

  • The Associated Press writes, “Gold Prices Soar as Investors Flee Wall Street.”

  • The Bullion Vault claims, “Gold Prices Poised to Move Higher.”

  • Forbes observes, “Gold Prices Resume Long-Term Uptrend

  • So What’s next? Read on…-Good Investing! -jschulmansr 

    ==================================

    Catch the New Bull! – Buy Gold Online – Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

    ======================================

    Gold Prices Could Hit $1500, fears Merrill Lynch CIO- Business 24/7

    By: Shashank Shekhar of Business 24/7


    Gold prices may hit $1,500 (Dh5,509) an ounce in the next 12 to 15 months, Gary Dugan, the Chief Investment Officer (CIO) of Merrill Lynch, said yesterday.

    Dugan termed his apprehensions of gold striking such a high as a “fear” that may come true. He reasoned that such a price would mean the other commodities and streams of investments have been shunned by investors.

    With confidence in currencies shaken to the core, the yellow metal is increasingly assuming the role of “the most trusted currency”, Dugan said. “We have never seen such a rush to buy gold. It’s bringing in security and it’s still affordable.”

    Merrill Lynch commodity price forecast authored by Dugan showed that gold prices can rise from the currently prevailing $913/oz to $1,100/oz in the first quarter of 2009 and to $1,150/oz in the second quarter. “While demand for gold has been rising production has been declining. South Africa, which accounts for the major share of global gold production, is facing political issues and has energy problems,” Dugan said.

    With reports of declining returns from other investment options, “cash” – keeping money safe in banks and investing in government bonds – is the option in front of investors, Dugan said.

    “Fear” and eventual decline of the greenback are the two factors that will drive gold prices, he said. While commodity markets could also bounce back in the first half of the year, a rebound is likely to be short-lived in the absence of strong US consumer demand.

    Precious metals, led by gold, could enjoy a more sustained rally with gold benefiting from a weakening of the dollar in the second half of the year, Dugan said.

    Dugan said the greenback, which has been strengthening for the past few months, will decline in value by the middle of this year. “That’s when people will begin to realise that President Obama’s policies are not having the desired impact,” he said.

    Investors could also look to private equity, which produced strong returns during the downturns in 1991 and 2001, on an opportunistic basis. Some hedge fund strategies may be worth following but hedge funds should be treated with caution, Dugan said.

    Returns from private equity should remain in single digits in 2009 and a return of beyond 10 per cent should be treated as “fair value”, he said. “Investors should remain cautious. They need to be prepared to take profits. We think any such rally would run out of steam by the second half of the year.”

    Low risk assets could offer private investors the best prospects of attractive returns in 2009 as the world’s leading industrialised nations face recession, Dugan said. With governments around the world striving to tackle the economic crisis, private investors could find value in a cautious approach towards asset allocation. Options include high-grade corporate bonds and high-quality, high-yielding equities in defensive industries.

    “Investors will look to long-term US government bonds as an important barometer of the progress of global recovery,” said Dugan. “Sharply rising bond yields will show that the governments have overspent.”

    While earnings downgrades are likely to dominate the first quarter of 2009, a rally in global equity markets could be on the cards for the first half of the year with consumer and cyclical stocks among the potential beneficiaries, Dugan said.

    Broad equities indices could also offer trading opportunities to private investors. “Equities could outperform as an asset class in 2009 unless there is a serious deflation risk. Our view is that deflation will be avoided,” he added.

    Selective investment in high-grade corporate bonds could also provide attractive returns, Dugan said.

    ==================================

    Catch the New Bull! – Buy Gold Online – Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

    ==================================

    Is a New Cyclical Bull Market on It’s Way? – Seeking Alpha

    By: Simit Patel of Informed Trades.com

     Puru Saxena of Money Matters recently wrote an article entitled ‘Birth of a New Cyclical Bull?‘ in which he offers arguments for why we may see 2009 be a bullish year for equities. His basic points:

     Inflationary actions by the Fed and a declining TED Spread have proven effective in fighting falling asset prices and reducing risk

    • Treasury bonds need to have higher yields or money will go into equities
    • Equities have “overshot” to the downside, thus resulting in excessively low valuations

    I agree with Saxena’s basic premise that the Fed’s actions will be successful in creating inflation in the aggregate; it is only a matter of which asset class will reap the benefits of that inflation, and who will pay for it. The chart below compares various asset classes against one another for the month of January.

    click to enlarge

    A key question we may wish to begin asking and examining is just how much inflation the Fed has really created for us, something that will become more apparent as lending resumes and money that is “on the sidelines” returns to the game. I’m of the viewpoint that the global economy is currently improperly structured, and needs a complete restructuring, one that will likely require abandonment of the US dollar as world reserve currency, a corresponding decline in US consumption, and a significant restructuring of the FIRE (finance, insurance, real estate) economy in the United States.

    From that perspective, an equities rally will be unsustainable, unless there is currency debasement to the extent that all markets rise nominally. If that is the case, though, the inflation will result in significant dollar devaluation.

    Trading Implications: The fall in Treasuries was the story for January, and will be of importance so long as it continues. If money comes out of Treasuries and into equities and commodities, it increases the likelihood of seeing consumer price inflation. As I’ve stated before, though, I expect commodities to outperform equities once money comes out of Treasuries and dollar devaluation resumes. And as all currencies around the world are having trouble, gold will rise as fiat currencies continue to struggle.

    Disclosure: Long gold.

    ================================

     Catch the New Bull! – Buy Gold Online – Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

    ===============================

    U.S. Debt Default, Dollar Collapse Altogether Likely – Seeking Alpha

    By: James West of Midas Letter

    The prospect of the United States defaulting on its debt is not just likely. It’s inevitable, and imminent.


    The regulatory black holes into which sanity and reason disappear on a daily basis are soon to collapse under the mass of their sheer size. The circle jerk going on among G7 governments has to end – the steady advance of gold, even in the face of a managed price, exposes the real value of the U.S. dollar, as opposed to its apparent value expressed in the dollar index.

    Is 2009 the year that the United States formally defaults? And with that, will the dollar collapse be rolled back ten for one or more?

    There are a lot of reasons to support that theory. To Wall Street economists, such an event is heresy and therefore unthinkable. Yet Wall Street is the very La-la-land that bred the idea of a perpetually indebted nation in the first place.

    Number one among the indicators favoring this scenario is what is happening in the U.S. Treasuries auction market.

    Last Thursday, an $30 billion auction in five-year notes failed to stir the interest of traditional primary dealers. The auction itself was saved by an anonymous “indirect” bid.

    Buyers are discouraged by the prospect of what is expected to amount to $2 trillion total issuance for the full year of 2009. The further out the maturities on notes, the more bearish the sentiment towards them. The only way to entice buyers is through the increase in yields.

    But with yields at 1.82 per cent, five-year notes were met with a demand for 1.98 times the amount offered – the lowest bid-to-cover ratio since September. A sell-off in treasuries began in earnest upon the conclusion of that auction.

    The U.S. Federal Reserve suggested last week that it was going to step up its treasury-buying activity, and the mainstream media interprets this as a form of market support. What it actually is evidence of growing anxiety and desperation on the part of the Fed as the realization dawns that demand for treasuries is progressively evaporating.

    The increased demand for gold as an investment witnessed throughout the last two weeks that has pushed gold to a 4 month high is further evidence that investors across the board are gravitating more towards gold and away from U.S. debt.

    So what is the catalyzing event that will precipitate outright capitulation?

    I think the spin-controlled version of events will make the collapse of the derivatives market the red herring that facilitates the aw-shucks-we-have-no-choice shoe-gazing moment possible, and that’s exactly the parachute the government needs to retain a veneer of credibility – at least in its own delusional mirror.

    The announcement that the CFTC was about to become the target of a regulatory overhaul supports this theory. Consistent with his unfortunate proclivity to hiring foxes to guard chickens, Barack Obama’s choice for CFTC commissioner Gary Gensler was the undersecretary of the U.S. Treasury when the Commodity Futures Modernization Act of 2000 was passed, and is one of its architects. This was the piece of legislation that was put forth to appease the opposition to “dark market” trading in certain OTC derivatives first noisily derided by CFTC commissioner Brooksley Born in 1998.

    Ignoring Born’s admonishments with this act, it exempted credit default swaps (CDO’s) from regulation, resulting in the somewhere between 58 and 300 trillion dollars in value presently under threat if the positions were to be unwound. Because of their unregulated status, counterparties in the largest transactions can simply “roll forward” contracts, instead of the losing party in the transaction covering their loss with a transfer of money. It is this massive “nominal” value that could be the Achilles heel of what’s left of the U.S. banking system, and by extension, the U.S. dollar.

    I don’t arrive at this conclusion because I like making catastrophic outlandish predictions. Its merely the result of following certain logical paths to their most likely outcome based on what has happened in the past.

    In discussions on this topic with editors of top tier financial publications, such speculation is dismissed out of hand, and the argument to refute the likelihood of such outcomes is never brought forward.

    Gold exchange traded funds (ETFs) are now the largest holders of physical gold, and as a proxy for investors who don’t want to be encumbered with taking delivery of the physical, provide a simple way to participate in the gold market.

    United States citizens should bear in mind, however, that should the banking system be brought down completely by the collapse of the futures market, proxies for gold such as ETF’s and bullion funds could theoretically be targeted by a government desperate for possession of value. The risk from security in holding physical bullion is matched by the risk of confiscation by government in these volatile times. Don’t forget, the government confiscated and outlawed private ownership of gold in 1933 in support of an ill-conceived gold standard, which to some extent, was that era’s spin to halt the flight of gold (and real value) from U.S. soil.

    Don’t think for a minute such drastic events are outside the realm of possibility. If somebody had told you in 1998 that a bunch of angry crazy pseudo-Muslims were going to fly jetliners into the World Trade Center, what would you have said?

    ======================================

    My note: Very Scarey, 10-1 Trade In on Dollars? Gold Confiscated? This is one of the reasons why I use Bullion Vault, check them out for the details…jschulmansr

    Catch the New Bull! – Buy Gold Online – Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

    Good Investing! – Jschulmansr

    =======================================


    Nothing in today’s post should be considered as an offer to buy or sell or as a recommendation for  any securities or other investments, it is presented for informational purposes only. As a good investor, consult your Investment Advisor, Do Your Due Diligence, Read All Prospectus/s and related information carefully before you make any investments. –  jschulmansr

    Share this:

    • Share on Reddit (Opens in new window) Reddit
    • Share on Facebook (Opens in new window) Facebook
    • Share on LinkedIn (Opens in new window) LinkedIn
    • More
    • Share on X (Opens in new window) X
    • Share on Pinterest (Opens in new window) Pinterest
    • Share on Tumblr (Opens in new window) Tumblr
    • Print (Opens in new window) Print
    • Email a link to a friend (Opens in new window) Email
    Like Loading...

    It’s Official- The New Gold Rally Has Begun!

    30 Friday Jan 2009

    Posted by jschulmansr in Austrian school, Bailout News, banking crisis, banks, bear market, capitalism, central banks, China, Comex, Copper, Currencies, currency, Currency and Currencies, deflation, dollar denominated, dollar denominated investments, economic, Economic Recovery, economic trends, economy, Federal Deficit, Finance, financial, Forex, futures, futures markets, gold, Gold Bullion, Gold Investments, gold miners, How To Invest, How To Make Money, India, inflation, Investing, investments, Junior Gold Miners, Latest News, Make Money Investing, market crash, Markets, mining companies, mining stocks, palladium, physical gold, platinum, platinum miners, precious metals, price manipulation, prices, producers, production, Prophecy, resistance, Siliver, silver, silver miners, spot, spot price, stagflation, Stocks, TARP, Today, U.S. Dollar

    ≈ Comments Off on It’s Official- The New Gold Rally Has Begun!

    Tags

    agricultural commodities, alternate energy, Austrian school, Bailout News, banking crisis, banks, bear market, Bollinger Bands, bull market, capitalism, central banks, China, Comex, commodities, communism, Copper, Currencies, currency, deflation, Dennis Gartman, depression, diamonds, dollar denominated, dollar denominated investments, economic, economic trends, economy, Federal Deficit, financial, Forex, futures, futures markets, gold, gold miners, hard assets, heating oil, India, inflation, investments, Keith Fitz-Gerald, Marc Faber, Mark Hulbert, market crash, Markets, mining companies, Moving Averages, natural gas, oil, palladium, Peter Brimelow, Peter Schiff, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, protection, rare earth metals, recession, risk, run on banks, safety, Saudi Arabia, Sean Rakhimov, silver, silver miners, socialism, sovereign, spot, spot price, stagflation, Technical Analysis, timber, U.S. Dollar, volatility, warrants, Water

    As it write this Gold is up $22.50 oz to $929.00! It absolutely smashed thru the $920 resistance! If we hold here $950 -$975 is the next level.  Barrick Gold CEO Munk says China to be a big buyer of gold as confidence is lost in the U.S. Dollar. The treasuries bubble is starting to burst and money is pouring into gold!- Good Investing! – jschulmansr

    ====================================

    Catch the New Bull! – Buy Gold Online – Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

    =========================================

    Source: MineWeb.Com

     WORLD ECONOMIC FORUM

    Munk forecasts currency, economy fears will send gold to new record highs

    Whether it’s the currency effect or a reaction to a feeling of uncertainty, Barrick Gold Chairman Peter Munk says gold is more likely to go up than down.

    Author: Barbara Lewis
    Posted:  Friday , 30 Jan 2009

    DAVOS, Switzerland (Reuters) – 

    Gold is likely to hit new record highs, spurred by serious concern about the U.S. currency and doubt about the state of the world economy, the chairman of Barrick Gold Corp. said on Thursday.

    There was even a possibility, although not a probability, central banks, including China’s, might start to switch from dollar holdings to gold, which could cause the metal’s price to treble or more.

    From a gold producers’ perspective, one negative is that the cost of bringing on production has remained high, even as other raw materials, including base metals and energy, have slumped.

    “Gold is at record levels in every currency except dollars. Even within dollar terms it is within a few percentage points of an all-time high at a time when all the other major commodities are falling,” Peter Munk told Reuters at the World Economic Forum meeting in Davos.

    “Whether it’s the currency effect or a reaction to a feeling of uncertainty, gold in my opinion is more likely to go up than down,” the chairman and founder of the world’s largest gold mining company said.

    Spot gold was at $902.80/904.80 at 1817 GMT. It hit a record high of $1,030.80 an ounce in March last year.

    Munk stressed he was merely weighing the odds.

    “It would be stupid to assume commodities prices can only go one way,” he said, adding physical demand for gold jewellery was not high during the economic downturn.

    Gold has been one of the best-performing assets of late, rising in value by nearly 17 percent since late October.

    Investors have bought heavily into physical bullion in the form of coins and bars and physically-backed assets such as exchange-traded funds as a safe store of value at a time of increased volatility in other asset prices.

    Munk said downward pressure on the dollar, partly because of massive U.S. spending to stimulate the economy, would increase gold’s attractions as an investment further.

    Gold usually moves in the opposite direction to the dollar, as it is often bought as a hedge against weakness in the U.S. currency.

    “My personal feeling is that with the rescue packages calling for trillions, not billions… the value of the (U.S.) currency has to go down,” said Munk.

    DUMB TO HEDGE

    His company did not hedge its output for now — meaning it does not use derivatives to insure against a fall in price — and relied instead on the price climbing. In the past its successful hedging allowed it to make the acquisitions that helped to make it the world’s biggest gold miner.

    “It would be dumb to hedge,” Munk said of the current climate.

    His bullishness was underscored by the possibility central banks, including that of major dollar asset-holder China, might start buying gold.

    “If they decide to diversify, we assume into gold, then we start to talk about a trebling or quadrupling of the gold price. It could be followed by Russia or Kuwait.

    “I don’t think it’s likely, but it’s more likely. I would not have said it two years ago …I’m not a gold bug …but it’s more likely than it was two years ago.”

    A strong price climate has meant ongoing investment in bringing on new gold, Munk said.

    “In every other mining area, people are cancelling mines.”

    But declines in other commodities have yet to have a major impact on cost.

    “Marginally yes, but substantially no. For some reason cash costs are tending to continue to increase,” he said, when asked whether investment costs were falling.

    “Energy costs have gone down. It does help, but labour costs are consistently increasing.”

    The one way to reduce production costs is to invest in efficient new mines, Munk said, citing two major new projects in Nevada and the Dominican Republic and a smaller one in Tanzania.

    (Reporting by Barbara Lewis, additional reporting by Jan Harvey in London; editing by Anthony Barker)

    © Thomson Reuters 2009 All rights reserved

    =============================

    Catch the New Bull! – Buy Gold Online – Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

    =============================

    Hedge Fund to Measure Returns in Gold Rather Than Currency – Seeking Alpha

    By: Todd Sullivan of Value Plays

    This is a pretty stunning move. What is even more alarming is the reasoning given.
    From the FT:

    A hedge fund has begun offering investors the chance to have their investment denominated in gold, as worries grow over governments debasing their currencies by printing money.

    Osmium Capital Management, a $178m hedge fund manager based in Bermuda, is launching a new share class allowing investors to hold shares measured as troy ounces of the fund, rather than U.S. dollars, sterling or euros.

    The move follows a surge in investor demand for small gold (GLD) bars and coins held by individuals and gold-backed exchange-traded funds that are holding a record amount of bullion.

    Chris Kuchanny, Osmium chief executive and a former London ABN Amro trader, said he was putting almost all his personal wealth into the new share class: “Investors have voiced concerns that they’re overly exposed to the major fiat [paper] currencies in an environment where the fundamentals of those currencies are clearly deteriorating with governments assuming more debt and having lower revenue and more expenditure.

    This shows a stunning lack of confidence in currencies. It also says that the fund is anticipating inflation to rear its ugly head in a scary way. When it does, the value of the currencies will plummet and gold will rise.

    What is to watch now is whether or not other funds begin to follow. If this becomes a movement rather than an individual act, the crash in currencies could be expedited in a nasty way. Stay tuned…

    Disclosure: No position in gold… yet.

    ====================================

    Catch the New Bull! – Buy Gold Online – Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

    ====================================

    My Disclosure: Long Gold , Gold Etf’s, Gold Miners/Producers, Long Silver, Silver Miners/Producers, Platinum and Paladium Miners/Producers- jschulmansr

    More to follow later today…

    Nothing in today’s post should be considered as an offer to buy or sell any securities or other investments, it is presented for informational purposes only. As a good investor, consult your Investment Advisor, Do Your Due Diligence, Read All Prospectus/s and related information carefully before you make any investments. –  jschulmansr

    Share this:

    • Share on Reddit (Opens in new window) Reddit
    • Share on Facebook (Opens in new window) Facebook
    • Share on LinkedIn (Opens in new window) LinkedIn
    • More
    • Share on X (Opens in new window) X
    • Share on Pinterest (Opens in new window) Pinterest
    • Share on Tumblr (Opens in new window) Tumblr
    • Print (Opens in new window) Print
    • Email a link to a friend (Opens in new window) Email
    Like Loading...

    Are You Ready For This? – It’s Back and Ready To Rally!

    29 Thursday Jan 2009

    Posted by jschulmansr in Bailout News, banking crisis, banks, bear market, bull market, capitalism, central banks, China, Comex, commodities, Copper, Currencies, currency, Currency and Currencies, deflation, dollar denominated, dollar denominated investments, economic, Economic Recovery, economic trends, economy, Federal Deficit, Finance, financial, Forex, Fundamental Analysis, futures, futures markets, gold, Gold Bullion, Gold Investments, gold miners, How To Invest, How To Make Money, India, inflation, Investing, investments, Jim Rogers, Jim Sinclair, Latest News, Make Money Investing, Marc Faber, Mark Hulbert, market crash, Markets, mining companies, mining stocks, palladium, Peter Brimelow, physical gold, platinum, platinum miners, precious, precious metals, price, price manipulation, prices, producers, production, protection, run on banks, safety, Saudi Arabia, security, silver, silver miners, spot, spot price, stagflation, Stimulus, Stocks, TARP, Technical Analysis, Today, U.S. Dollar

    ≈ Comments Off on Are You Ready For This? – It’s Back and Ready To Rally!

    Tags

    agricultural commodities, alternate energy, Austrian school, Bailout News, banking crisis, banks, bear market, Bollinger Bands, bull market, capitalism, central banks, China, Comex, commodities, communism, Copper, Currencies, currency, deflation, Dennis Gartman, depression, diamonds, dollar denominated, dollar denominated investments, economic, economic trends, economy, Federal Deficit, financial, Forex, futures, futures markets, gold, gold miners, hard assets, heating oil, India, inflation, investments, Keith Fitz-Gerald, Marc Faber, Mark Hulbert, market crash, Markets, mining companies, Moving Averages, natural gas, oil, palladium, Peter Brimelow, Peter Schiff, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, protection, rare earth metals, recession, risk, run on banks, safety, Saudi Arabia, Sean Rakhimov, silver, silver miners, socialism, sovereign, spot, spot price, stagflation, Technical Analysis, timber, U.S. Dollar, volatility, warrants, Water

    Are You Ready For This! You are asking yourself “am I ready for what?””What’s ready to Rally?” Gold my friend is the answer! As I write Gold is consolidating right around the $900 level. If you had listened to me you would be sitting on profits of $50- $100 oz. already! Well don’t worry Gold still has plenty of room to move as you will see in today’s post. – Good Investing! – jschulmansr

    ======================================

    Catch the New Bull! – Buy Gold Online – Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

    =====================================

    Gold Price Could Double – World Gold Council

    Source: World Gold Council

    The value of gold could soar due to increased demand following the global financial crisis, it has been suggested.

    According to Citigroup, the price of gold could double by the summer, the Daily Mail reports.

    “We continue to remain unequivocally bullish on the medium to long-term view on gold and still believe that we can ultimately see levels in excess of $2,000 (?1,398),” the firm told the paper.

    Such levels would mean the price of gold would more than double its current value.

    The paper notes that since September, the value of the precious metal has already risen by $122.

    Citigroup added that price rises will either come via inflation following liquidity injections by governments around the world, or by continuing investment from those who view gold as a safe haven.

    In related news, a recent poll conducted by Bloomberg showed that 28 of 31 traders, investors and analysts questioned said now is a good time to purchase gold.
    =================================

    Catch the New Bull! – Buy Gold Online – Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

    =================================

    $850B Stimulus Plan Signals Gold Take-Off – Seking Alpha

    By: Peter Cooper of Arabian Money.net

    Last night the US passed its much anticipated $850 billion Obama stimulus package, representing another huge monetary expansion. Countries all around the world have been at it, and the volume of money in circulation is increasing at a record level.

    Meantime, gold prices have been perky and past $900 earlier this week. Now gold has fallen back a little. The gold chart has completed an almost perfect inverse head-and-shoulders pattern which should mark the reversal of the falling trend that started at $1,050 an ounce last March.

    Gold technicals

    Aside from the technicals of the gold chart, let us also get back to fundamentals: the supply of gold and silver is pretty much fixed. Money supply is undergoing huge and unprecedented expansion.

    At present, governments are printing money like fury and little is happening to their economies because banks, companies and individuals are hoarding cash. But eventually pulling on this string will work, and money will flood into the economy in an uncontrollable way.

    It is at this point that gold prices will go ballistic. That should not be more than nine months to a year away based on past precedent.

    However, before that golden age occurs there will be increasing speculation about the future of the gold (and silver) price. More and more investors will read articles like this one and be impressed by the argument – which is far sounder than trying to come up with a new bull market for equities, bonds or real estate.

    Bond crash

    Sometime soon the bond markets of the world are also going to weaken much further, and that will give precious metals another reason to rise in value as an alternative safe haven class.

    For investors in precious metals then it is just a matter of holding on and taking advantage of price dips to stock up with bullion and shares, although it is surely arguable that the best buying opportunities are behind us now as the price trend is about to head back up.

    Trying to time the market exactly or using borrowed money is not a clever approach in volatile markets, but a diversified precious metals portfolio is going to be a winner over the next two years.

    ===============================

    Catch the New Bull! – Buy Gold Online – Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

    ==============================

    Gold $2200: What’s in a number? – Seeking Alpha

    By: Adrian Ash of Bullion Vault

    Gold must hit $2,200 an ounce to match its real peak of Jan. 1980. Or so everyone thinks…

    WHAT’S IN A NUMBER…? Ignoring the day-to-day noise, more than a handful of gold dealers and analysts reckon gold will hit $2,200 an ounce before this bull market is done.

    Why? Because that’s the peak of 1980 revisited and re-priced in today’s US dollars.

    Which sounds simple enough. Too simple by half.

    First, betwixt spreadsheet and napkin, there’s often a slip. Several targets you’ll find out here on the net put the old 1980 top nearer $2,000 in today’s money. Another Gold Coin dealer puts the figure way up at $2,400 an ounce.

    Maybe they got the jump on this month’s Consumer Price data. Maybe $200 to $400 an ounce just won’t matter when the next big gold top arrives. But maybe, we guess here at BullionVault, an extra 20% gain (or 20% of missed profits) will always feel crucial when you’re looking to buy, sell or hold. Perhaps that’s the problem.

    Either way, having crunched (and re-crunched) the numbers just now, even we can’t help but knock out a target…

    To match its inflation-adjusted peak of $850 an ounce – as recorded by the London PM Gold Fix of 21st Jan. 1980 – the price of gold should now stand nearer $2,615.

    Second, therefore, the lag between current Gold Prices and that old nominal high scarcely looks a good reason to start piling into gold today. “Ask the investor who rushed out to Buy Gold precisely 29 years ago, at $845 an ounce, about gold as an inflation hedge,” as Jon Nadler – senior analyst at Kitco Inc. of Montreal, the Canadian dealers and smelters – said on the 29th anniversary of gold’s infamous peak last week.

    “They could sell it for about $845 today…[but] they would need to sell it for something near $2,200 just to break even, when adjusted for inflation.”

    This lag, of course, can be turned any-which-way you like. For several big-name Gold Investment gurus, including Jim Rogers and Marc Faber, it mean gold has got plenty of room left to soar, compared at least with the last time investors began swapping paper for metal in a bid to defend their savings and wealth.

    But for the much bigger anti-gold-buggery camp – that consensual mob of mainstream analysts, op-ed columnists, news-wire hacks and financial advisors – gold’s inflation-adjusted “big top” just as easily stands as a great reason not to Buy Gold. Ever.

    “An investor in gold [buying at the end of 1980] experienced a reduction in purchasing power of 2.4% per annum,” notes Larry Swedroe, a financial services director at BAM Services in Missouri, writing at IndexUniverse.com and recommending Treasury inflation-protected TIPs instead.

    “[That was] a cumulative loss of purchasing power of about 55%…Even worse, that does not consider the costs of investing in gold…[and] while gold has provided a slightly positive real return over the very long term, the price movement is far too volatile for gold to act as an effective hedge against inflation.”

    Volatility in Gold can’t be denied. Indeed, it’s the only thing we ever promise to users of BullionVault. (They can judge our security, cost-efficiency and convenience for themselves.) Traditionally twice as volatile as the US stock market, the price of gold has become five times as wild since the financial crisis kicked off. But price volatility has also leapt everywhere else, not least in the S&P 500 index – now 8 times wilder from the start of 2008. The Euro/Dollar exchange rate is more than four times as volatile as it was back in Aug. ’07, when the banking meltdown began. Even Treasury bonds have gone crazy, making daily moves in their yield more vicious still than even the Gold Price or forex!

    So putting sleepless nights to one side (you may need to ask your pharmacist), the key point at issue remains “long term” inflation.

    This chart shows the value of Gold Bullion – measured in terms of purchasing power, as dictated by the official US consumer price index – since the data series begins, back in 1913. (Hat-tip to Fred at the St.Louis Fed; the current CPI calculations and headline rate might bear little resemblance to personal experience of retail inflation, but for long-run data where else can we go?)

    Starting at 100, our little index of gold’s real long-term value has then averaged 97.8 over the following 96 years…pretty much right where it began. As you can see, however, that long-term stability includes wild swings and spikes. And whether gold is tied to official government currency (as it was pre-1971) or allowed to float freely on the world’s bullion market, volatility looks the only sure thing.

    The starting-point, 1913, just happens to be when the Federal Reserve was first founded. It was given the easy-as-pie challenge of furnishing the United States with an “elastic currency”.

    Okay, so it ain’t quite made of rubber just yet. But the Dollar’s own value in gold – by which it used to be backed, pre-1971 – just keeps brickling and bouncing around like it’s being used to play squash.

    What the chart above offers, however, is a picture of gold’s real long-run value outside of Dollar-price fluctuations.

    “With the right confluence of economic and geopolitical developments we should see gold break through $1,500 and then $2,000 and then possibly still higher round numbers in the next few years,” said Jeffrey Nichols, M.D. of American Precious Metals Advisors, at the 3rd Annual China Gold & Precious Metals Summit in Shanghai last month – “particularly if we get the type of buying frenzy or mania that often occurs late in the price cycles of financial and commodity markets.”

    “This is hardly an audacious forecast when looked at relative to the upward march in consumer prices over the past 28 years. After all, the previous high of $875 an ounce in January 1980, when adjusted for inflation since then, is today equivalent to more than $2,200.”

    Audacious or not, as Nichols points out, the thing to watch for would be a “buying frenzy” – a true “mania” amongst people now Ready to Buy Gold that sent not only its price but also its purchasing power shooting very much higher.

    Because for gold to reach $2,200 an ounce in today’s money (if not $2,615…) would mean something truly remarkable in terms of its real long-run value.

    • Inflation-adjusted, that peak gold price of 21 Jan. 1980 saw the metal worth more than 5 times its purchasing power of 1913;
    • In March 2008, just as Bear Stearns collapsed and gold touched a new all-time peak of $1,032 in the spot market, the metal stood at its best level – in terms of US consumer purchasing power – since December 1982;
    • Touching $2,200 an ounce (without sharply higher inflation undermining that peak), gold would be worth almost 6 times as much as it was before the Federal Reserve was established in real terms of domestic US purchasing power.

    “I own some gold,” said Jim Rogers, for instance, in an interview recently, “and if gold goes down I’ll buy some more…and if gold goes up I’ll buy some more.

    “Gold during the course of the bull market, which has several more years to go, will go much higher.”

    But “much higher” in nominal Dollar terms is not the same as “much higher” in terms of real purchasing power, however. More to the point, that previous peak of $850 an ounce – as recorded at the London PM Gold Fix on 21 Jan. 1980 – lasted hardly two hours.

    Defending yourself with gold is one thing, in short. Assuming gold is the perfect inflation hedge is quite another. And taking peak profits in gold – as with any investable asset – is surely impossible for everyone but the single seller to mark that very top price.

    That doesn’t diminish gold’s real long-term value to private investors however, as we’ll see in Part II – to follow.

    Catch the New Bull! – Buy Gold Online – Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

    ==============================

    Is Gold Really Pausing? – MarketWatch

    By: Peter Brimelow of MarketWatch.com

     Will Mark Hulbert’s recent column, pointing out that the Hulbert Gold Newsletter Sentiment Index (HGNSI) was over-extended, signal an important top? Or just a ripple? See Hulbert’s Jan. 27 column.

    Either way, there will be a group of angry readers. Of the 220 comments about the column, as I write, the furious bulls outnumber the fanatical bears about 3 to 1.
    But both sides are pretty riled up. This is only money, people!
    Early Monday in New York, gold cleared $915. But Wednesday evening, it was down $30-plus from its high. And the US$ 5×3 point and figure chart kindly supplied by Australia’s The Privateer service has turned down. See chart.
    There is a possibility that the action around the weekend was a false breakout.
    If it turns out to be a bull trap, GoldMoney’s James Turk will turn out to have been wise in his latest Freemarket Gold & Money Report. Turk accepts the radical thesis that the price of gold is manipulated by an alliance of private and public sector actors.
    He writes: “Gold must still contend with the gold cartel and its ongoing efforts to cap the gold price. It may try to ‘circle the wagons’ above $900, which would seem a logical point for them to make another stand now that $850 has been exceeded. If the gold cartel is successful in stopping gold for any length of time, new longs may get discouraged by the lack of progress and take profits. That selling, along with new shorts by the gold cartel, could begin a cycle of selling that gains momentum and drives gold back to its last level of support, which is $850.” See GoldMoney Web site.
    Will gold stumble? In favor of the bears, oddly enough, is the section of Bill Murphy’s radical goldbug LeMetropoleCafe Web site that follows India. The Indians are definitely out of the world gold market, it appears. On downswings, their support is usually crucial. See LeMetropoleCafe Web site.
    But the radical gold bugs think strange things are happening. Murphy’s site noted Tuesday that the extraordinary premiums being paid in the West for gold items did not go away on this month’s rise. And the Comex gyrations, closely examined, continue to suggest the presence of large, determined buyers.
    For perspective on Mark Hulbert’s HGNSI, look at MarketVane’s Bullish Consensus for gold. This surveys futures traders. It peaked at 74% on Monday, and came in tonight at 72%.
    Sometimes gold peaks do occur with this reading in the 70s. That happened at the turn of the year, and again last September.
    But the normal behavior, especially before a big sell-off, is for the upper 80s at least to be reached. Last February/March, as gold attempted $1,000, the Bullish Consensus spent no less than four weeks in the 90s. See MarketVane Web site.
    So the radical gold bugs conclude that gold may pause. But it’s not seen a major blow-off yet. End of Story
    ===============================
    Catch the New Bull! – Buy Gold Online – Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

    ===============================

    Gold headed south for the short term?- MarketWatch

    By: Mark Hulbert of MarketWatch.com

    ANNANDALE, Va. (MarketWatch) — Gold certainly deserved a rest Wednesday.
    After all, it had mounted an impressive rally over the previous two weeks, gaining some $100 per ounce. So we can definitely excuse gold bullion  for forfeiting $9 in Wednesday trading.
    The more crucial question, however, is whether the decline was merely the pause that refreshes, or the beginning of a more serious drop.
    Unfortunately for those hoping gold’s recent rally to continue, the conclusion of contrarian analysis is that the metal’s short-term trend is more likely to be down.
    Consider the latest readings of the Hulbert Gold Newsletter Sentiment Index (HGNSI), which reflects the average recommended gold-market exposure among a subset of short-term gold-timing newsletters tracked by the Hulbert Financial Digest. As of Tuesday night, the HGNSI stood at 60.9%.
    This is identical to where the HGNSI stood at the end of December, when I last devoted a column to gold sentiment. ( Read my Dec. 29 column.)
    Over the two weeks following that column, of course, bullion dropped by around $70 an ounce.
    Contrarian concern about gold’s short-term trend isn’t just based on this one data point, however. I have more than 25 years of daily data for the HGNSI, and rigorous econometric tests show that the inverse correlation between HGNSI levels and the gold market’s subsequent short-term direction is statistically significant at the 95% confidence level.
    This is why the HGNSI’s current level is so ominous.
    To put it in context, consider that this sentiment gauge’s average reading over the last five years has been 32.6%, only slightly more than half where it stands now. Over the last five years, furthermore, the HGNSI has been higher than where it is now just 13% of the time.
    This does not mean gold can’t go higher from here. But it does suggest that the odds are against it doing so.
    Lest I incur undeserved gold-bug wrath by writing that, let me hasten to add that this bearish conclusion applies to just the next several weeks. Sentiment affects the short-term trend of the market, not the long term.
    So my conclusion is entirely consistent with gold being in a major, long-term bull market.
    But even if it is, the implication of my contrarian analysis is that gold is not ready, at this very moment, to commence on that march upward. End of Story
    Mark Hulbert is the founder of Hulbert Financial Digest in Annandale, Va. He has been tracking the advice of more than 160 financial newsletters since 1980.
    =============================
    My Note- While feeling that Gold price make take a breather here consolidate and maybe even drop a little, both Mark Hulbert and Peter Brimlow agree; Gold is in a long term Bull Market! Any dips in price should be taken as an opportunity to buy more gold!…

    Catch the New Bull! – Buy Gold Online – Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

    That’s all for now, hit the subscribe button to keep up with all the latest Gold, Market News and more…Enjoy! – jschulmansr
    Nothing in today’s post should be considered as an offer to buy or sell any securities or other investments, it is presented for informational purposes only. As a good investor, consult your Investment Advisor, Do Your Due Diligence, Read All Prospectus/s and related information carefully before you make any investments. –  jschulmansr

    Share this:

    • Share on Reddit (Opens in new window) Reddit
    • Share on Facebook (Opens in new window) Facebook
    • Share on LinkedIn (Opens in new window) LinkedIn
    • More
    • Share on X (Opens in new window) X
    • Share on Pinterest (Opens in new window) Pinterest
    • Share on Tumblr (Opens in new window) Tumblr
    • Print (Opens in new window) Print
    • Email a link to a friend (Opens in new window) Email
    Like Loading...

    Is this the Move? Gold is Breaking Out!

    26 Monday Jan 2009

    Posted by jschulmansr in agricultural commodities, banking crisis, banks, bear market, bible, Bollinger Bands, bull market, capitalism, central banks, China, Comex, commodities, Copper, Currencies, currency, Currency and Currencies, deflation, Dennis Gartman, depression, dollar denominated, dollar denominated investments, economic, Economic Recovery, economic trends, economy, Federal Deficit, Finance, financial, Forex, Fundamental Analysis, futures, futures markets, gold, gold miners, hard assets, How To Invest, How To Make Money, id theft, India, inflation, Investing, investments, Latest News, Make Money Investing, market crash, Markets, mining companies, mining stocks, natural gas, oil, palladium, physical gold, platinum, platinum miners, precious, precious metals, price, price manipulation, prices, producers, production, silver, silver miners, small caps, spot, spot price, stagflation, Stimilus, Stimulus, Stocks, TARP, Technical Analysis, timber, Today, U.S. Dollar, Uncategorized, uranium, volatility

    ≈ Comments Off on Is this the Move? Gold is Breaking Out!

    Tags

    agricultural commodities, alternate energy, Austrian school, Bailout News, banking crisis, banks, bear market, Bollinger Bands, bull market, capitalism, central banks, China, Comex, commodities, communism, Copper, Currencies, currency, deflation, Dennis Gartman, depression, diamonds, dollar denominated, dollar denominated investments, economic, economic trends, economy, Federal Deficit, financial, Forex, futures, futures markets, gold, gold miners, hard assets, heating oil, India, inflation, investments, Keith Fitz-Gerald, Marc Faber, market crash, Markets, mining companies, Moving Averages, natural gas, oil, palladium, Peter Schiff, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, protection, rare earth metals, recession, risk, run on banks, safety, Saudi Arabia, Sean Rakhimov, silver, silver miners, socialism, sovereign, spot, spot price, stagflation, Technical Analysis, timber, U.S. Dollar, volatility, warrants, Water

    As I write Gold currently is up another $9.30 oz today! Even more importantly it is well above the psychologically important price level of $900 oz. A new high will confirm the breakout and BANG! we’re off to the races. Todays past has some good articles detailing why could could be breaking out here. Enjoy and Good Investing!- jschulmansr

    ============================================

    Here is a safe way for even a small investor to get in on the Gold Rush! You can buy quantities as little as 1 gram to 1000’s of oz. I personally use Bullion Vault for my physical metal purchases.

    Catch the New Bull! – Buy Gold Online – Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

    ============================================

    Could There Be a Real Breakout In Gold?— Seeking Alpha

    By: Trader Mark of Fund My Mutual Fund

    After a series of head fakes much of the past half year, the most watched move in the market might finally be “real” this time. With all the world’s printing presses going on overdrive, and currencies being mocked – gold “should” have been rocketing. Many theories persist on why it hasn’t, but really it does not matter. The price action is all that matters and this type of movement will get the technicians very interested.

    Things to like
    1) a series of higher lows
    2) the trendline of lower highs has been penetrated

    Things to see for confirmation
    1) any pullback is bought
    2) price prints over October 2008’s highs, signaling the end of “lower highs”

    When last we looked about 6 weeks ago [Dec 11: Dollar v Gold – Can we Trust this Change?] , it was just another headfake – this formation on the chart does look more promising.

    These are 2 names; one in gold and one in silver we’ve had our eyes on.

    Or just play it simple and go double long gold


    ==================================================

    Happy Days For Gold? —Seeking Alpha

    By: Jeff Pierce of Zen Trader

    Gold was in the spotlight on Friday in a big way, nearly moving $39. Is this a hat tip to the big move that many goldbugs have been anticipating? Is all the money printing that the Federal Reserve finally catching up with the US Dollar? Should you have bought gold on Friday because it’s a straight line up from here? Let me preface my answers by saying that I’m a short term trader that will sometimes allow a trade to turn into a longer term trade but that doesn’t happen very often. I’m currently flat precious metals but will be looking for a good risk/reward, but for anybody reading this know that this analysis is from a momentum based perspective.

    So the answers to the previous questions I believe are yes, yes, and no.

    gld

    I’m a big fan of gold for a number of reasons (fundamental, technical, historical) but I know from experience that it trades much different from a momentum point of view. It tends to sell off once it goes outside it’s upper bollinger band as seen by the arrows above. Just when it looks like gold is going to bust out and move to blue skies it seems to run out of buyers and reverses. As you can see GLD and many individual gold miners moved outside this indicator on Friday and I expect a small pullback before it begins a new wave up.

    Judging by the negative divergence on the RSI you can easily see that momentum is waning. As the stock has been making higher highs, the RSI has not been confirming the move. We could possibly move up to the 92 level before profit taking hits, but I just don’t see a good entry at this point if you’re not already invested in these stocks. It would be more prudent to wait for a slight low volume pullback before entering. The only problem with this way of thinking is there could possibly be many with this outlook and that could actually propel gold to higher levels, but I’m willing to risk that because if it does move up even more, then that will confirm the strength and I’ll buy even more on the eventual dip.

    If you are long from lower levels I would consider taking some profits off the table now to prevent yourself from giving up any of your gains.

    “I made all my money selling to soon.” ~ JP Morgan

    slv

    I like silver’s chart a tad better from a technical aspect as the base that it’s been building since last September seems a little more stable. The RSI trendline has been steadily moving higher as the price has been trending higher which is very bullish. I think we’re a tad overbought here and will be looking to get long stocks such as PAAS, SLW, and SSRI when we pullback or move sideways for a week or two.

    =================================================

    Now- Some Commentary by Dennis Gartman

    Dennis Gartman on Gold, Oil, Government and the Economy- Seeking Alpha

    Source: The Gold Report

    With a real roller-coaster year behind us, how would you characterize your macro overview of major economic trends for 2009?

    Dennis Gartman: It’s abundantly clear that we have been in recession; we’re in a recession; and we’re likely to remain in a recession through the greatest portion of 2009. The monetary authorities around the world have done all the things they’re supposed to do, which is during a period of economic weakness throw liquidity in the system as abundantly, as swiftly, as manifestly as possible and expect the liquidity eventually to wend its way through the economy and strengthen economic circumstances. That may be sometime late in 2009. In the meantime, we’ll see continued bad economic data and continued increases in unemployment. It’s going to seem like things are really, really, really bad.

    But let’s remember that things are always their worst at the bottom. By definition, recessions begin at the peak of economic activity when all economic data looks its best. So while things will start to look very bad through the rest of 2009, I bet that by late this year and early 2010 we will start to see economic strength coming at us because of the liquidity injections going on everywhere.

    TGR: What will be the first signs that we’ve reached the bottom in terms of the recession and are starting to turn around?

    DG: The signs of a turnaround will be that everybody believes that there are no signs of a turnaround. We’ll see Newsweek writing a series of cover stories talking about the end of Western civilization. The Financial Times of London headlines will read, “The Recession Seems Endless” and “Depression Is Upon Us.” Every day’s Wall Street Journal articles will be just manifestly bleak in nature. That’s what the signs will be.

    And then all of a sudden, things shall begin to turn around. But the signs are always their worst at the bottom. That’s how things function.

    TGR: So the popular press is in essence on a delay mode.

    DG: Oh, it always is.

    TGR: By three months, by six months, by a year?

    DG: It’s probably a little less slow to react than it used to be, but let’s say three months.

    TGR: So you like the fact that the monetary authorities have put liquidity into the system?

    DG: Absolutely.

    TGR: And it sounds as if you think it just takes time to work through the system.

    DG: Always has; always will. That’s how these things go about. You have recessions because you had an economic advance where, in Greenspan’s terms, “irrational exuberance took over.” You have to dash that irrational exuberance and make it into irrational depression. Irrational, manifestly bleak, black philosophies have to make their way to the public. That’s just how these things happen; it’s happened time and time again.

    The recession that I recall the most clearly is that of ’72-’74. We have to remember that unemployment was high up in double digits. We saw plenty of articles in the press about the new depression. If you go back and read articles from July through September of 1974, you will be convinced that we will never have an economic rebound in our lives again. Well, clearly, that’s just not the case.

    TGR: What about the bearish people who say we’ve never seen worldwide conditions like this and that we’re in the “new era”?

    DG: We probably haven’t seen the world going into recession at one time such as we are now. But I think that’s simply indicative of the fact that today’s communications are so much better. People in the United States or Canada or Europe really never would have known much about a recession in India 20 years ago, because the news media would not have covered it. Nothing told you about economic circumstances abroad. Now, with the Internet, information comes at you absolutely one-on-one.

    All correlations have gone to one in this present environment. When stocks go down in the United States, they go down in India. When they go down in India, they go down in Vietnam. When they go down in Vietnam, they go down in Australia. That wasn’t the case 20 years ago; you didn’t have the small world united through communications that we have now. And now the correlations of emerging markets and large markets have all come together.

    TGR: If that’s true, and worldwide financial markets are all tied together, could any given country “emerge” as a growth country while the rest remain in recession?

    DG: Oh, it’s possible, but I don’t think we’ll call them “emerging markets” anymore. You’ll just find that one country pursued better economic policies, probably by cutting taxes or increasing government spending or doing away with some onerous legal circumstance that might have previously inhibited economic activity. The Chinese are doing any number of good things at this point, and that country may just have been more enlightened and it may come out of the recession faster than the others do. But now they won’t do it on their own, and anybody who does do it will be watched and understood much more swiftly than in the past. For example, did you ever know what was going on in Iceland 10 years ago? Of course not; but now you do.

    TGR: Right. The only emerging markets we heard about were China and India. No one ever discussed South America.

    DG: And now they’ve emerged. But now we understand. We hear news from Venezuela every day. Now we hear news from Sri Lanka every day if we want it; we can get it very easily. We couldn’t do that 10 years ago; 20 years ago clearly we couldn’t. That’s been the big change. Information travels so much more rapidly. That’s why all the correlations have gone to one. We are now one large economic machine that maybe one of the component parts does a little bit better, but it won’t shock anybody, and there won’t be anything “emerging.”

    TGR: Back to the bear people. You referenced the ’72-’74 economy, but this time, many are pointing to the debt situation that the U.S. and probably a bunch of the world economies are in and the fact that we’re committing to billions—and in the U.S., trillions—of dollars more. Won’t that influx of new money have some kind of significant bear impact going forward?

    DG: No, it will have a bullish impact. Unless all the rules of economics have been rescinded, money pushed into a system will push economic activity higher.

    TGR: But it will also push inflation higher.

    DG: Oh, that’s very likely to happen. The question is whether it will be inflation of 1%, 2%, 5%, or will it be a Zimbabwean-like inflation? The latter isn’t going to happen, and 1% isn’t likely going to happen. But 2% to 5% inflation? Yes, that’s likely to happen several years down the line.

    TGR: Gold bugs are saying, “Buy gold now.” What would be your advice under these circumstances?

    DG: I happen to be modestly bullish on the gold market, but not because of inflationary concerns. It’s more that I think gold has quietly moved up the ladder of reservable assets, a reservable asset being one that central banks are willing to keep on their balance sheets, all things being equal. Dollars are still the world’s dominant reservable asset. The Euro is next and gold is probably the third.

    The Fed has thrown off a lot of other assets and taken on securities, debt instruments, mortgages and the like, but I think they’re doing exactly the right thing. Some central banks with a lot of U.S. government securities on the balance sheet may decide that going forward, they may buy more gold rather than more U.S. government securities if they’re running an imbalance of trade surplus. For instance, if I’m the Bank of China and I hold a minuscule sum of gold, maybe I should own a slightly larger minuscule sum.

    TGR: That’s really diversifying your monetary assets.

    DG: I think that’s all that will drive the gold prices quietly higher. I am not a gold bug; I don’t think the world’s coming to an end. I think the history of man is to progress. And yes, we have relatively large amounts of debt, but you can go back to the recession of 1974; you can go back to 1980-81; you can go back to the recession of 1907, and you will see the same arguments—that the world is too debt-laden. And the same arguments, the same language, the same verbiage was always written in exactly the same circumstances. Guess what? We moved on. This time might be different, but I’ll bet that it won’t be.

    TGR: What would your recommendation for investors to do in gold? If they want to do any type of holding assets in monetary value, should they be looking at holding physical gold or buying ETFs or buying into the equity?

    DG: For the past several years, I’ve told people that if they’re going to make the implied bet on gold, bet on gold. The gold bugs tell you that you have to own bullion. I say, no, you should really own the GLD, the ETF. It trades tick-for-tick with gold. If some truly untoward chaotic circumstance ran through the world’s banking system I guess maybe GLD and bullion would diverge at some point, but we’d have other problems long before that would occur. So if you’re going to make the implied bet on gold, bet on gold. Do the GLD.

    TGR: But not physical gold?

    DG: I do own some physical gold. But do I own a lot of it? No. And quite honestly, I hope I lose money on the physical gold I have. It’s an insurance policy. Nothing more than that.

    TGR:: Are you looking at physical gold as the insurance policy or any investment in gold as an insurance policy?

    DG: There’s the old saying, “Those aren’t eatin’ sardines; them is trading sardines.” Some gold I consider to be tradable, and that’s ETF-type stuff, and I have a small amount in the lockbox in the form of gold coins. That’s my insurance policy.

    TGR: That would be what the typical investment broker might advise, 5% to 10% in gold.

    DG: That’s it. Exactly, that’s it. Don’t get overwhelmed by it.

    TGR: How about mining stocks?

    DG: If you’re going to bet on gold, there’s nothing worse than being bullish on gold and owning some mine—especially in some junior fly-by-night—and walking in one morning and finding out that the mine you thought you had got flooded or all of your workers were unionized and walked off or management was somewhat derelict. You may have been right on the direction of gold, but your stock went down. So I’ve told people to stay away from the juniors; that’s a terrible bet on gold. If you’re going to bet on gold, bet on gold.

    Maybe you’ll want to start punting on Barrick Gold Corporation (NYSE: ABX) or Newmont Mining Corp. (NYSE: NEM) or the real large names, rather than the juniors. There’s just too much risk in the juniors. Yes, everybody says, “I bought this junior at a nickel and now it’s at 15 cents.” Well, jolly for you, but you probably bought 15 others at a nickel, and they’re all bankrupt. If you’re going to bet on gold, bet on gold.

    TGR: So you’re saying with that advice that if you want to bet on gold equity, bet on blue-chip gold equity stocks that have just been hammered down through the market.

    DG: That’s correct, Agnico-Eagle Mines (TSX: AEM), ASA Ltd. (NYSE: ASA), the Newmonts, the Barricks, that sort of thing.

    TGR: If we take that logic and look across the broad array of sectors, would you also recommend looking at other blue chips that have just been battered? Or do you think that some sectors will recover faster than others? Such as the financial sector, the energy sector, the housing sector, the precious metals sector?

    DG: I’m really quite bullish on infrastructure—the movers and the makers of the things that if you drop them on your foot, it will hurt. I think I want to own steel and copper and railroads and tractors because I think we’re going to be building roads and bridges. That’s probably one of the things that probably will bring us out of the economic morass. Along those lines, I wouldn’t mind owning a little bit of gold at the same time.

    TGR: Unlike gold that you can buy and own, if you look at steel and copper, are there specific companies and equities that are appealing to you?

    DG: Again, as in gold, if I am going to buy gold equities, I’m going to buy the biggest names. If I’m going to buy steel, I’m going to buy the biggest names. U.S. Steel comes to mind. That’s the easiest; that’s the best; that’s where liquidity lives. It has been bashed down from the highs made last July; it’s down—what?—75% from its high. Recently it stopped going down and is in fact starting to go up now on bad news. So if you’re going to buy steel, buy the most obvious ones—U.S. Steel or buy Newcorp.

    TGR: You talked about the energy market being weak in one of your recent newsletters. Do you see this weakness continuing or do you see a turnaround happening in ’09?

    DG: The one thing that we can rest assured in the rest of the world is that OPEC chiefs cheat on each other—they always have and they always will. So when OPEC says that it’s cut production, that’s a lovely thing. No, they haven’t, and they don’t. Because the problem OPEC has is they’ve all raised their standards of living and the expectations of their people, and they all have cash flow requirements. You have to sell three times as much $50 crude oils as you sold $150 crude oil to meet the demands of your populace that you have increased. So the lovely thing from a North American perspective is that Chavez finds himself in a very uncomfortable position and needs to produce a lot more crude oil to keep his public happy. It’s rather comical, isn’t it, that Chavez was giving crude oil away to the Kennedy family to be distributed to people in the Northeastern United States until two weeks ago when he had to stop. He had to stop because he needs the crude oil on his own to sell, not to give away, to meet cash flow demands.

    Iran is in exactly the same position. Isn’t it lovely to see that Putin, who was really feeling his military oats six months ago with $150 oil, has to pick fights with Ukraine and smaller countries now with crude at $45 a barrel? Where is crude going to go? I wouldn’t be surprised if we make new lows.

    TGR: Will there be new lows for ’09? Are you buying into this whole peak oil argument that production eventually will be unable to meet demand?

    DG: Do I believe that we’re going to run out of crude oil in the next 100 years? Not on your life. Sometime in the next 10,000 years we probably will run out of crude oil. In that instance, I am a peak oil believer. It’s not going to happen soon though. I remember they told me when I was in undergraduate school back in the late ’60s that we would be out of crude oil by 1984.

    TGR: Do you mean out of oil? Or at a point where demand exceeds production?

    DG: We would be out! Gone, done! There would be no more. Isn’t it interesting? We’ve pumped crude oil for 28 more years. This is an interesting statistic: We have either seven or eight times more proven reserves now than we had in 1969. And I think we have used a bit of crude oil between now and 1969.

    TGR: Just a wee bit.

    DG: A wee bit, and yet we have seven or eight times more proven reserves. Every year we have more proven reserves. So, yes, I’m a peak oil believer. Sometime in the next 10,000 years we will run out of crude.

    TGR: With Obama now in office and talking about getting off our reliance on foreign oil, what’s your view of the future on all the alternative energies that are being so pushed by many people in the U.S. government?

    DG: I think it’s wonderful job-creation programs, none of which will prove to be of much merit at all. All of the Birkenstock-wearing greens will feel very good about having their rooftops covered by solar panels, but is that going to resolve any energy problems we have? No. No. Nuclear power will do that. Maybe using the oceans will do that, but wind power, probably not. Solar power, probably not. It makes everybody feel good, but are we going to power our cars in the next 40 years with solar power? I doubt it. Do I expect some sort of material technological breakthrough in the next 100 years that will change what we use as energy? Oh, absolutely. Do I have any idea what it will be? Of course not.

    TGR: If the price of oil if it remains low, is there a role for nuclear in the next 50 years?

    DG: Oh, absolutely.

    TGR: What will drive that?

    DG: It’s absurd that we don’t use nuclear energy. Even the French derive 80% of their electricity from nuclear energy, cleanly, efficiently, without any problems whatsoever. Why we don’t do the same in the United States other than the left and the eco-radicals keeping us from doing it is really quite beyond me.

    TGR: So, given that we still have eco-radicals and a big push toward alternative energies, do you see anything happening in the U.S. in nuclear in the near future?

    DG: Yes, actually. It’s interesting. There are a lot of new nuclear facilities on the drawing boards, and they’re probably going to be approved. If there’s going to be one surprise by the Obama Administration, it will be that you don’t get nuclear energy advances under a right-wing government; you always get them under a left-wing government. Obama will be smart enough to understand that that’s the only way—that’s the best and cleanest methodology to use. And the left won’t argue with a fellow leftist pushing for nuclear energy. Only Nixon could go to China; only Obama can push nuclear energy.

    TGR: And you think that he will?

    DG: Oh, yeah, he’s smart enough to understand that.

    TGR: Going back to your investment strategy, which big blue chip players in oil and nuclear would you point out as good investments?

    DG: In oil, I’d want to take a look at companies such as ConocoPhillips (NYSE: COP), which dropped 70% from its highs. How can you go wrong with the Conocos and the Marathons and the large oil companies whose price-to-earnings multiples are down to at single digits and their dividend streams are 5%, 6%, and 7%? Why would you not want to own those? That’s the best investment.

    And at the same time, the volatility indices on the stock market are so high that, gee, you can buy Conoco, get the dividend, and sell out of the money calls at very high premiums and ramp your dividend yield up. It’s like a gift; it’s like manna.

    TGR: Well, what about in terms of the nuclear sector and uranium?

    DG: I really don’t understand uranium. I don’t know where to go, and I don’t how to buy it yet. So I’ll just say there’s a future for it, but I don’t know what to do with it.

    TGR: What other sectors should be looking at for 2009?

    DG: Banks, banks.

    TGR: They’re making a comeback. Do you think there will be more consolidations?

    DG: There will be more consolidations; there has to be. But look at the yield curve—what a year to be a bank! The overnight Fed funds rate, the rate banks are going to pay depositors for their demand deposits or checking accounts is zero. And you’re going to be able to lend that out to hungry borrowers at 7%, 8%, 9%, 10% and 12%. The next three years will be the greatest three years banks have ever seen. Banks will just make money hand over bloody fist in the next three years.

    TGR: Are you talking about the big boys?

    DG: No, I’m talking about the regionals. The big boys have problems in toxic assets. I am not even sure there is a Peoples Bank & Trust in Rocky Mount, North Carolina, but a bank like that—or the First National Bank of Keokuk, Iowa or the First National, or the Peoples Bank & Trust of Park City, Utah—those are the banks that are going to make lots of money.

    TGR: Do you see an explosion in regional banks? Will move of them come into the marketplace?

    DG: I think we’ve probably got all we need. It’s just that they’re very cheap.

    TGR: What will the role of the international banks be?

    DG: Mopping up the disasters that they’ve created for themselves for the past decade, trying to survive, being envious of the decent regional banks that are going to be earning enormous yields on this positively sloped yield curve and wishing they were they.

    TGR: Do you see a role long term for international banks?

    DG: Oh, sure, of course. How could there not be? It’s a smaller world; it’s an international world; it’s a global world. International banks will be back in full force a decade from now. They’ve got some wound-licking to do, and they’ll do it.

    TGR: In addition to regional banks as being a great play to look at for ’09, ’10, any other interesting plays to bring up?

    DG: You want to own food and grains again.

    TGR: Are you talking about grains or food producers like Nabisco?

    DG: No, I think you want to own grains. If you’re going to make a speculation, I think you want to own on the grain markets again.

    TGR: Grain for human consumption or grain for livestock consumption?

    DG: Yes and yes.

    TGR: Are you looking at buying that on the commodities market?

    DG: You can actually buy that on ETFs now. The wonderful world of ETFs is just extraordinary. You can actually buy a grain ETF now. DBA (DB Agriculture Fund) is one; JJG (iPath Grains) is another. Those are basically long positions in the grain market. Wonderful things to use.

    TGR: You like ETFs; but the naysayers will say that ETFs could be encumbered and there’s actually no guarantee that they hold any assets.

    DG: That’s true; that’s correct.

    TGR: But you’re comfortable that people should go into an ETF for grains?

    DG: I didn’t say that. What I said is if you wish to trade in grain, there are ETFs that will do that. Do I know for sure that they will all perform perfectly and that if the world were to come to a chaotic banking circumstance that there wouldn’t be problems? I don’t know that. Does that bother me? No. It doesn’t bother me even slightly.

    Should you worry about [not trading] an ETF just because there might be some problem under an untoward economic environment? No, it’s illogical. And shame on those people who say those sorts of things or who tell you not to use them because they ETF may not function properly if there is some total breakdown in the banking system. Well, if that happens, we have other problems.

    TGR: And what’s your projection for the overall investment market? We’ve been hearing speculation that it will rise through April, bottom out even deeper than it is today, and then a slow climb in 2010.

    DG: Gee, I have no idea. I just think that stock prices will be higher six months from now than they are now, much higher 12 months than they will be six months from now, and higher still in 24 months than they will be 12 months from now. But where will they be in April? Golly, I don’t know. I think the worst is far behind us and better circumstances lie ahead. And that’s the first time in a loooonnnng while that I’ve said that.

    TGR: Yeah, now if the media will just catch up with you, we can enjoy watching it again.

    DG: It won’t. Watch the news; it will just get bleaker and bleaker as the year goes on. And watch the unemployment rate; it’s going to be a lot higher.

    TGR: Other than Barack Obama saying we’re going to start building infrastructure, do you anticipate any dramatic changes in the U.S.? Right now we’re a services country, and we need to move back to being a manufacturing country.

    DG: We’ll never move back to being a manufacturing country. Won’t happen. Here’s an interesting bit of data. Do you know what year that we had the absolute high number—not just as a percentage of population—but the absolute high number of manufacturing jobs was in the United States?

    TGR: Somewhere around the World War II era.

    DG: Very good, 1943. We have lost manufacturing jobs since 1943. I think that’s a fairly well-established trend.

    TGR: Is there a future for the services sector, though? That’s the key.

    DG: It will be larger. And so what? It’s like saying we need more farmers. No. We need fewer farmers. We have one-hundredth as many farmers as we had at the turn of the 20th century. We now 500 times more grain? Seems to me every time we lose a small farmer, we get better. So, we need fewer farmers. And we need fewer manufacturing jobs.

    TGR: But doesn’t that put the onus on the United States as the economic world leader? Considering the fact that, as you mentioned, information now is instantly available everywhere, just in terms of worldwide confidence; it seems like every time we hiccup, the planet hears it?

    DG: There is probably some truth to that fact. But it is probably not us that will lead; it’s probably Australia or New Zealand or the Baltic States or some smaller country that actually changes policies and frees up markets and cuts taxes, and all of a sudden their economy starts to turn around. Then people elsewhere will say, “Oh, look! That’s the right thing to do. Let’s us go do that.”

    TGR: Really? Economic recovery worldwide will not come from the United States?

    DG: Well, if we don’t recover, the rest of the world won’t, but we won’t be the first. What I am saying is that some smaller country will do the right things faster than we do.

    TGR: Isn’t what Australia does irrelevant to what the U.S. needs to do?

    DG: No, it’s dramatically relevant. If Australia starts to do things properly—if Australia were to suddenly come out and slash taxes and go to a flat tax and cut paperwork by 50% and it’s economy starts to turn higher, wouldn’t that be a good incentive for us to do the same thing?

    TGR: But that implies that every country should use the same economic strategy; that we’re all basically at the same state in our economic development. That what will work for Zimbabwe or China will work for the U.S.

    DG: I think anywhere in the world that you have smaller government, lesser taxes—every time you do that, that economy, no matter where it is, does better. It does better. And anywhere you put higher taxes and more government, that economy usually does worse. It does; it just does.

    TGR: You’re looking at it from a macro point of view.

    DG: I’m looking at it just from an economic point of view, whether macro or micro. Look at Ireland, for example. Why was Ireland for many years the “Celtic Tiger” of Europe? Their tax regime was lower than the rest of Continental Europe. The Germans and the French, who are statists, who are collectivists, instead of emulating the Irish, kept trying to drag Ireland down to their level. Now, that was stupid, wasn’t it? That didn’t work.

    My favorite example is New Zealand back in the 1980s. Every year from the 1970s through the 1980s, New Zealand ran a budget deficit and a trade deficit. Every year the IMF said, “You must raise your taxes and cut the value of your currency to try to balance your budget and run a trade surplus.” So New Zealand would do that, and every year the deficit got worse and their trade imbalance grew larger. They did this for five or six years and it got worse every time they did it—every time they followed the IMF tactic of raising taxes and cutting the value of the currency.

    Finally New Zealand Treasury Secretary Graham Scott (Secretary from 1986–93) told the IMF, “Don’t ever come back here. Everything you’ve told us to do has proven to be utterly worthless. We’re going the other way. We’re slashing taxes.” From I think a 75% marginal tax rate, over the course of five years, they cut it to like 18%. And every year they took in more money—more money—every time they cut taxes they took in more money. And when they strengthened their currency, their exports picked up; as their currency got stronger, they exported more stuff. Isn’t it fascinating?

    TGR: That’s the paradox.

    DG: It got to be so interesting—it wasn’t Gordon Campbell—I’m trying to remember; I just went blank for his name. But he passed the baton on to a woman by the name of Ruth Richardson, who was a little more leftwing than her predecessor—the tax rate was down to a flat 18%. They asked her if she was going to cut it again, and she said, “You know, I don’t think I can cut it any more; I can’t spend the revenue I am taking in now.” It’s a classic line. So, what does she do? They actually started raising the tax rates again, and what happened? Tax revenues fell.

    But New Zealand had taught a lot of people that cutting taxes and strengthening your currency is the best thing you can do. And as they were cutting taxes, they kept cutting prohibitions and regulations; they kept chopping them back. They were the real precursors of the Free Market Movement that developed in the early ’90s and the early ’00s.

    TGR: Let’s hope the United States learns from that. Obama announced his tax cuts; we’ll see what comes of that.

    DG: He said entitlements are even on the table. Can you imagine a Republican ever making that statement? They would boo him. But here’s a leftist who puts it on the table. He can say that.

    Irreverent, outspoken, entertaining, sardonic and—in his own words, a “glib S-O-B,” Dennis Gartman has been producing The Gartman Letter for more than 20 years. His daily commentary on global capital markets as well as short- and long-term perspectives on political, economic and technical circumstances goes to leading banks, brokerage firms, hedge funds, mutual funds, energy companies and grain traders around the world.

    A 1972 graduate of the University of Akron (Ohio), he undertook graduate studies at North Carolina State University in Raleigh (where he remains involved as a member of the Investment Committee.

    Before devoting himself full-time to The Gartman Letter, Dennis analyzed cotton supply and demand in the U.S. textile industry as an economist for Cotton, Inc.; traded foreign exchange and money market instruments at North Carolina National Bank, went to Chicago to serve as A.G. Becker & Company’s Chief Financial Futures Analyst and then become an independent member of the Chicago Board of Trade, dealing in treasury bonds and notes and GNMA futures contracts; and moved to Virginia to run Virginia National Bank’s futures brokerage operation.

    In addition to publishing The Gartman Letter, Dennis delivers speeches to audiences around the world (including central banks, finance ministries, and trade groups), teaches classes on derivatives for the Federal Reserve Bank’s School for Bank Examiners, and makes frequent guest appearances on CNBC, ROB-TV and Bloomberg television.

    ==============================================

    Finally for the Technical Analysis Junkies (like me!) here is an awesome article!

    ===============================================

    Market Leaders Hesitate on Stimulus Plan— Seeking Alpha

    By: Chris Ciovacco of Ciovacco Capital Management

    Proposed Economic Stimulus Plan May Not Stimulate Much

    The new administration is proposing an $825 billion “stimulus” plan. Most of the package is geared toward helping existing or expanded programs such as unemployment assistance, law enforcement, food stamps, etc. Much of this spending will “save” existing jobs or keep existing programs already in place. This may help prevent things from getting worse, but it will offer little in the way of providing new stimulation for the economy. Another large portion of the stimulus plan is in the form of tax cuts. While depreciation incentives may spur some new business spending, credits to individuals may offer little incentive to spend given the state of their balance sheets and concerns about employment. After all the hype about infrastructure spending, only about 25% of the package is geared toward this area.

    Tug of War Between Liquidity and Economic Weakness

    The chart below was created on the website of the Federal Reserve Bank of St. Louis. It shows the eye-popping expansion of the money supply as financial institutions have swapped securities and other “assets” for cash via borrowing from the Federal Reserve. Borrowing prior to this crisis is barely visible on the graph. Recent borrowing is an extreme example of the term “spike” on a graph. Despite the never before seen tapping of the Fed, financial assets show little evidence of reflation taking place.

    Borrowing From FEDU.S. Stocks: Downtrend Remains In Place

    If you compare the long S&P 500 ETF (SPY) to the short S&P 500 ETF (SH), it is clear the short side of the market is in better shape. There is little in the way of fundamentals, except hope of government bailouts, to expect any change to these trends.

    S&P 500 ETF - SPY - LongRecent weakness in the S&P 500 Index leaves open the possibility that we will revisit the November 2008 lows around 740 (intraday). If those lows do not hold, a move back toward 600 becomes quite possible. On Friday (1/23/09) the S&P 500 closed at 832. A drop back to 740 is a loss of 11%. A move back to 600 would be a drop of 28%. These figures along with the current downtrend highlight the importance of principal protection and hedging strategies. SH, the short S&P 500 ETF, can be used to protect long positions or to play the short side of the market.

    2009 Investing Deflation Inflation Outlook StrategyGold & Gold Stocks Still Face Hurdles

    Friday’s big moves in gold (GLD) and gold mining stocks (GDX) have some calling a new uptrend. While recent moves have been impressive some hurdles remain.

    Gold At Important LevelsGold stocks (GDX) look a little stronger than gold, but any entry in the market should be modest in size. If $38.88 can be exceeded, our confidence would increase and possibly our exposure.

    2009 Investing Deflation Inflation Outlook StrategyRun In Treasuries Is Long In The Tooth

    Investments with the highest probability of success are those with positive fundamentals and positive technicals. Conversely, the least attractive investments have poor fundamentals and poor technicals. With the U.S. government issuing new bonds at an alarming rate, a continued deterioration in the technicals could signal the end of the Treasury bubble.

    2009 Investing Deflation Inflation Outlook StrategyTBT offers a way to possibly profit from the negative forces aligning against U.S. Treasury bonds.

    2009 Investing Deflation Inflation Outlook StrategyStrength In Bonds Shows Little Fear of Price Inflation

    The government’s policies are attempting to stem the tide of falling asset prices. They hope to reinflate economic activity along with asset prices. The charts here show:

    •  
      • A weak stock market (see SPY above), and
      • An improvement in many fixed income investments (below: LQD, AGG, BMT, PHK, and AWF).

    Weak stocks and stronger bonds tell us the government’s reflation efforts are thus far not working. If concerns about deflation remain more prevalent than concerns about inflation, fixed income assets may offer us an apportunity. With money markets, CDs, and Treasuries paying next to nothing, we may be able to find improved yields in the following:

    •  
      • LQD – Investment Grade Corporate Bonds
      • AGG – Investment Grade Bonds – Diversified
      • BMT – Insured Municipal Bonds
      • PHK – High Yield Bonds
      • AWF – Emerging Market Government Bonds

    With the economy in a weakened and fragile state, we need to tread carefully in these markets. Some key levels which may improve the odds of success are shown in the charts below. Erring on the side of not taking positions is still prudent. The markets remain in a “prove it to me” mode where we would like to see the markets move through key levels before putting capital at risk.

    2009 Investing Deflation Inflation Outlook Strategy 2009 Investing Deflation Inflation Outlook Strategy 2009 Investing Deflation Inflation Outlook Strategy 2009 Investing Deflation Inflation Outlook Strategy 2009 Investing Deflation Inflation Outlook StrategyU.S. Dollar Remains Firm

    From a technical perspective, the dollar continues to look strong. Its strength supports the continuation of concerns about deflation, rather than inflation.

    2009 Investing Deflation Inflation Outlook StrategyDisclosure: Ciovacco Capital Management (CCM) and their clients hold positions in SH, GLD, and PHK. CCM may take long positions in GDX, TBT, LQD, AGG, BMT, and AWF.

    =============================================

    Catch the New Bull! – Buy Gold Online – Safely, quickly, and at low prices, guaranteed! Bullion Vault.com

    =============================================

    Nothing in today’s post should be considered as an offer to buy or sell any securities or other investments, it is presented for informational purposes only. As a good investor, consult you Investment Advisor,  Do Your Due Diligence, Read All Prospectus/s and related information before you make any investments. – jschulmansr

    Share this:

    • Share on Reddit (Opens in new window) Reddit
    • Share on Facebook (Opens in new window) Facebook
    • Share on LinkedIn (Opens in new window) LinkedIn
    • More
    • Share on X (Opens in new window) X
    • Share on Pinterest (Opens in new window) Pinterest
    • Share on Tumblr (Opens in new window) Tumblr
    • Print (Opens in new window) Print
    • Email a link to a friend (Opens in new window) Email
    Like Loading...

    Latest Obama Eligibility News and More…

    25 Sunday Jan 2009

    Posted by jschulmansr in 2008 Election, Achievement, Barack Obama, bible, communism, Electoral College, id theft, John McCain, Presidential Election, socialism, Today, u.s. constitution, U.S. Dollar, Uncategorized

    ≈ 2 Comments

    Tags

    2008 Election, Barack Dunham, Barack Hussein Obama, Barack Obama, Barry Dunham, Barry Soetoro, capitalism, Chicago Tribune, Columbia University, Currency and Currencies, D.c. press club, Electoral College, Electors, Finance, fraud, Free Speech, gold, Harvard Law School, hawaii, id theft, Indonesia, Indonesian Citizenship, Investing, investments, Joe Biden, John McCain, Latest News, legal documents, Markets, name change, natural born citizen, Oath of Allegiance of the President of the United State, Occidental College, Phillip Berg, Politics, poser, Presidential Election, Sarah Palin, socialism, Stocks, Today, treason, u.s. constitution, U.S. Dollar, Uncategorized, voter fraud, we the people foundation

    Well here we are, Obama’s 1st act was to flub his oath of office, there are still cases on Obama eligibility filtering up. One thing we should be aware of, when has it become legal for a person to consult with the judges who are going to hear and potentially try his case? Once again total dis-regard and disdain for the Constitution. Yes, I know it was a “courtesy” trip, however, timed conveniently before the judges are set to see if the latest eligibility case has merit? And was there a secret session? Watch the 1st Video First! ***Eye Opening-***jschulmansr

    ==================================================

    Where Is Your Birth Certificate? Mr Open President?

    ==================================================

    Religious Leader On Obama’s Birth Certificate

    Dr. James David Manning, PhD (ATLAH Church) is angered by Barack Obama’s failure to present his Birth Certificate.


    ================================================

    Why The Oath Was Retaken

    By: Joseph Farah World Net Daily

    When Supreme Court Chief Justice John Roberts and President-elect Barack Obama flubbed the oath of office on inauguration day, WND was pilloried for prominently noting the problem.

    “Oh, come on,” wrote one emailer. “This is just being nitpicky. Your antipathy for Obama is showing in your willingness to jump on him for everything.”

    Yet, one day later, Roberts and Obama agreed to repeat the oath of office – this time in a more private setting and following the specific requirements of the U.S. Constitution.

    Maybe paying strict attention to the Constitution isn’t nitpicky after all?

    Article II, Section 1 of the Constitution stipulates the exact 35 words of a proper oath of office: “I do solemnly swear (or affirm) that I will faithfully execute the Office of President of the United States, and will to the best of my Ability, preserve, protect and defend the Constitution of the United States.”

    Since some of those words were transposed and left out of the original oath on the day of inauguration, Roberts feared the matter could become a point of contention. Twice before in American history presidents Chester A. Arthur and Calvin Coolidge needed to repeat their oaths because of similar mistakes.

    I’m glad someone still takes at least part of the Constitution seriously. Unfortunately, another part of Article II, Section 1 was completely trampled upon during the 2008 election process and right up through the swearing in ceremony. That is the issue of whether Obama is indeed, as the Constitution requires, a “natural born citizen.” Perhaps he is, perhaps he isn’t. Perhaps we’ll never know, because no controlling legal authority has ever required proof and publicly affirmed its validity.

    Again, when such issues were raised, many have suggested it’s simply nitpicking.

    But the Constitution either means precisely what it says or it doesn’t. If we’re going to fudge on such simple, straightforward matters as eligibility requirements for the president and oaths of office, where does the fudging end?

    And, conversely, if it is so critically important to recite the specific and exact 35 words of the oath of office as delineated in the Constitution, why was it not important to establish Obama’s eligibility beyond any shadow of a doubt?

    Should this matter now be dropped?

    Or should it be relentlessly pursued?

    What would happen now if it were determined that Obama was not, in fact, constitutionally eligible to become president? It’s certainly not a simple matter like restating the oath.

    On the other hand, because of the enormous potential for raising a constitutional crisis, should the American people just sweep the matter under the rug

    ?

    These are the tough questions we have been left with by Obama and all those in authority who allowed this question of eligibility to fester for so long.

    Once again, they provide us with some practical arguments for taking the Constitution seriously and literally in all matters. The Constitution is the bedrock of our system

    of governance. It is the tie that binds our nation together. It is the foundation for the rule of law in America.

    There is nothing frivolous about its requirements.

    There is nothing nitpicky about adhering to them.

    So, I’ll ask the pointed question one more time: “Where’s the birth certificate?”

    Where’s the proof Barack Obama was born in the U.S. or that he fulfills the “natural-born American” clause in the Constitution? If you still want to see it, join more than 200,000 others and sign the petition demanding proof of eligibility now!

    Maybe we need a national movement of people asking the same question in venue after venue – anywhere and everywhere the new president appears. Maybe we need rallies on the National Mall where ordinary Americans bring copies of their birth certificates and display them proudly with accompanying signs that say: “I’ll show you mine if you show me yours.”

    Do we need a national uprising of the American people simply to get the Constitution observed and taken seriously and literally?

    It seems like a lot to ask.

    Yet, on the other hand, is there a more important national cause?

    ===============================================

    Okay this part of the constitution is important but proving eligibility to be the President under the constitution is not? I am confused!

    ===============================================

    President’s meeting with Judges questioned

    Lawyer challenging eligibility raises issue of secret conference

    Source: World Net Daily

    A lawyer working on a case before the U.S. Supreme Court that challenges the eligibility of President Obama is raising concerns over a meeting between the defendant in the case and the judges who are expected to review it.

    The case is one of many brought before U.S. courts that allege Obama doesn’t meet the “natural born” requirement of the U.S. Constitution for the president. It’s one of about half a dozen that have reached the U.S. Supreme Court, which already has declined to grant hearings to several cases.

    Orly Taitz, whose case is scheduled to be heard tomorrow in a conference among justices – a private meeting at which they review cases and decide whether they should hold a hearing – confirmed on her website today that a supplemental brief in her arguments had been distributed.

    But the website also reported she “had to explain … many of us citizens are also concerned about the eight out of nine justices meeting privately with Mr. Obama (while the cases are pending).”

    The blog continued, “No reporters were allowed. No attorneys were invited on behalf of the plaintiffs. This causes many of us citizens to question the rules of judicial ethics and causes us to question the impartiality on behalf of the justices.”

    The report said “quite a number of people” have raised their questions with their U.S. representatives over the issues.

    According to a CBS report, Obama visited the Supreme Court before his inauguration at the invitation of Chief Justice John Roberts. The report described it as a protocol visit.

    According to a separate published report, Obama and then-Vice President-elect Joe Biden met in a court conference room with Roberts and seven other justices for about 45 minutes.

    The report said the only absent justice was Samuel Alito.

    Where’s the proof Barack Obama was born in the U.S. or that he fulfills the “natural-born American” clause in the Constitution? If you still want to see it, join more than 215,000 others and sign the petition demanding proof of eligibility now!

    The supplemental documents in the Taitz case cite an executive order concerning qualifications issued by President Bush Jan. 16.

    “This action is seeking the mandate for the U.S. State Department, the FBI and the Director of the Personnel Department to seek the documents for verifying Obama’s legitimacy as president and also his citizenship of the United States,” the blog reported.

    The Supreme Court document reveals that the Taitz case is scheduled for conference tomorrow, and her supplemental briefs have been distributed to the justices.

    Taitz said her arguments rest on precedents from both the California Supreme Court, which years ago removed a candidate for president from the ballot because he was only 34, and the U.S. Supreme Court’s affirmation of the ruling. The Constitution requires a president to be 35. Her case raises the issue of Obama’s birthplace and citizenship status, which also are specified in the Constitution.

    The lawsuits allege in various ways that Obama does not meet the “natural born citizen” clause of the U.S. Constitution, Article 2, Section 1, which reads, “No Person except a natural born Citizen, or a Citizen of the United States, at the time of the Adoption of this Constitution, shall be eligible to the Office of President.”

    Some allege his birth took place in Kenya, and his mother was a minor at the time of his birth – too young to confer American citizenship. They argue Obama’s father, Barack Obama Sr., was a Kenyan citizen subject to the jurisdiction of the United Kingdom at the time and would have handed down British citizenship.

    There also are questions raised about Obama’s move to Indonesia when he was a child and his attendance at school there when only Indonesian citizens were allowed and his travel to Pakistan in the ’80s when such travel was forbidden to American citizens.

    One case, handled by Gary Kreep of the United States Justice Foundation, is seeking Obama’s school records from Occidental College, which could reveal if Obama attended class on aid intended for foreign students.

    Another lawyer working on similar allegations, Philip J. Berg, has written to Congress seeking an investigation, while Taitz’s filings have been before the U.S. Supreme Court.

    Berg, whose information is on his ObamaCrimes.com website, said the issue isn’t going to disappear.

    Others agreed.

    “Should Senator Obama be discovered, after he takes office, to be ineligible for the Office of President of the United States of America and, thereby, his election declared void,” argues a California case brought on behalf of Ambassador Alan Keyes, also a presidential candidate. “Americans will suffer irreparable harm in that (a) usurper will be sitting as the President of the United States, and none of the treaties, laws, or executive orders signed by him will be valid or legal.”

    WND twice has organized opportunities for readers to send FedEx letters to the Supreme Court, asking for consideration of the issue on its merits.

    The most recent campaign generated 12,096 messages, following the earlier effort that resulted in 60,128 letters.

    Obama has claimed in his autobiography and elsewhere that he was born in Hawaii in 1961 to parents Barack Hussein Obama Sr., a Kenyan national, and Stanley Ann Dunham, a minor. But details about which hospital handled the birth and other details provided on the complete birth certificate have been withheld by Obama despite lawsuits and public demands for release.

    Meanwhile, a separate report has emerged in the Buffalo, N.Y., News about a woman who said she recalled being told about Obama’s birth in Hawaii. Barbara Nelson reported she was having a dinner with Dr. Rodney T. West, an obstetrician, when he discussed the birth of a baby boy to Stanley Ann Dunham, Obama’s mother.

    She said she later taught Obama as a high school student in Hawaii.

    WND senior reporter Jerome Corsi went to both Kenya and Hawaii prior to the election to investigate issues surrounding Obama’s birth. But his research and discoveries only raised more questions.

    The biggest question was why, if a Hawaii birth certificate exists as his campaign has stated, Obama hasn’t simply ordered it made available to settle the rumors.

    The governor’s office in Hawaii said there is a valid certificate but rejected requests for access and left ambiguous its origin: Does the certificate on file with the Department of Health indicate a Hawaii birth or was it generated after the Obama family registered a Kenyan birth in Hawaii?

    =================================================

    Share this:

    • Share on Reddit (Opens in new window) Reddit
    • Share on Facebook (Opens in new window) Facebook
    • Share on LinkedIn (Opens in new window) LinkedIn
    • More
    • Share on X (Opens in new window) X
    • Share on Pinterest (Opens in new window) Pinterest
    • Share on Tumblr (Opens in new window) Tumblr
    • Print (Opens in new window) Print
    • Email a link to a friend (Opens in new window) Email
    Like Loading...

    Are You Invested In Gold Miners?

    23 Friday Jan 2009

    Posted by jschulmansr in bull market, Comex, commodities, Copper, Currency and Currencies, economic trends, economy, Fundamental Analysis, futures, futures markets, gold, gold miners, hard assets, How To Invest, How To Make Money, inflation, Investing, investments, Latest News, Make Money Investing, Markets, mining companies, mining stocks, palladium, physical gold, platinum, platinum miners, precious, precious metals, price, price manipulation, prices, producers, production, rare earth metals, silver, silver miners, small caps, spot, spot price, stagflation, Stocks, Technical Analysis, Today, U.S. Dollar

    ≈ Comments Off on Are You Invested In Gold Miners?

    Tags

    agricultural commodities, alternate energy, Austrian school, Bailout News, banking crisis, banks, bear market, Bollinger Bands, bull market, capitalism, central banks, China, Comex, commodities, communism, Copper, Currencies, currency, deflation, depression, diamonds, dollar denominated, dollar denominated investments, economic, economic trends, economy, Federal Deficit, financial, Forex, futures, futures markets, gold, gold miners, hard assets, heating oil, India, inflation, investments, Keith Fitz-Gerald, Marc Faber, market crash, Markets, mining companies, Moving Averages, natural gas, oil, palladium, Peter Schiff, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, protection, rare earth metals, recession, risk, run on banks, safety, Saudi Arabia, Sean Rakhimov, silver, silver miners, socialism, sovereign, spot, spot price, stagflation, Technical Analysis, timber, U.S. Dollar, volatility, warrants, Water

    Good Morning, As I am writing this post Gold is up another $17 to $876/ oz. It would appear barring sudden dollar strength, we have succesfully broken the upper resistance level of $860 to $870; if we hold here $900+ will be the next level. Are You Invested In Gold Miners? If so, today’s post is a must read. – Good Investing!- Remember to Dare Something Worthy Today Too! – jschulmansr

    ETF vs. Mutual Fund: Two Ways to Invest in Gold Miners – Seeking Alpha

    By: Don Dion of Fidelity Independent Advisor

    Whether saddled to mutual funds like Fidelity Select Gold (FSAGX) or ETFs like Van Eck’s Gold Miners Index (GDX), gold investors have experienced a wild ride over the last year. While the recent volatility in gold prices is certainly enough to give investors pause, a good argument exists for the presence of a gold ETF or mutual fund in a well-diversified portfolio. Both FSAGX and GDX help investors mitigate the pitfalls of falling currencies and economic slowdowns. Since gold is a physical asset, it tends to maintain its value over time, giving wary investors an added measure of security as time-tested institutions vanish in the face of economic crisis.

    FSAGX and GDX both invest assets in companies that are primarily engaged in the exploration, mining, processing and dealing of gold. As of FSAGX’s semiannual report in November 2008, the fund held seven out of ten of the same top ten holdings. While GDX tracks the NYSE Arca Gold Miners Index, comprising 32 small, medium and large companies incorporated in any gold index, FSAGX is managed by Joe Wickwire and is composed of 69 holdings. The similarities between the two funds are striking, but some investors prefer having a human, rather than an index, at the helm. The larger number of holdings in FSAGX also means a smaller concentration of assets in top holdings, reducing the exposure that investors have to any one portfolio component.

    The top component for both FSAGX and GDX is Barrick Gold Corp. (ABX), constituting 13.77% of GDX’s portfolio as of January 13 and 9.5% of FSAGX’s portfolio as of late November 2008. The Toronto-based exploration company holds interests in a variety of gold resources in South America, Africa and Australia. At the end of 2007, ABX had 124.6 million ounces of proven and probable gold reserves, 1.03 billion ounces of contained silver within gold reserves, and 6.2 billion pounds of copper.

    Goldcorp (GG), the second-largest holding for both GDX and FSAGX, saw shares battered with a series of downgrades and target price reductions in early January, after releasing lower guidance for 2009. Some analysts, however, have dismissed the tarnish to Goldcorp’s shares as an overstatement of the reality of an industry-wide slowdown. In GG’s latest report, the adjusted forecast calls for 50% growth in production through 2013—only 5% lower than analysts’ estimates. In 2008, GG produced a hefty 2.3 million ounces of gold, achieving low margins on a scale larger than those of other competitors such as Yamana Gold (AUY) and Agnico-Eagle Mines (AEM).

    While the most obvious difference in deciding between an ETF and mutual fund is the fees associated with the two different investments, investors should consider several factors when choosing FSAGX or GDX. Even though the expense ratios of both funds are well below the category average—FSAGX is 0.86% while the ratio for GDX is 0.59%—many investors have gravitated to the ETF fund in recent years for the additional edge.

    Investors who own FSAGX will have to hold shares of the fund for longer than 30 days in order to avoid a 0.75% redemption fee—a nerve-racking setback for nervous investors who prefer the option of getting in and out of investments quickly. As opposed to the once-a-day pricing method of mutual funds, ETFs like GDX trade continuously throughout the trading day, but this flexibility also brings an increased measure of volatility. ETFs tend to be more affected by changing news events than mutual funds are, causing surges and dips in price avoided by comparatively steadier mutual funds.

    The differences between GDX and FSAGX are more apparent when comparing fund performance in recent months. GDX dropped more than 63% from July 14, 2008, to October 28, 2008, but it has since recovered 35%. FSAGX, however, fell only 60% from July 14 to October 28 and has recovered 36% in the period since. While their price movement is relatively similar, investors fearing intraday volatility may feel more comfortable with FSAGX than GDX, especially given its longer track record.

    While putting assets into gold could prove to be a profitable move for many investors, it is important for prospective GDX and FSAGX buyers to keep the role of this commodity in perspective. With the ultimate success of gold investments weighing heavily on continuing inflation concerns, placing a bet on gold—or any narrow sector—could whipsaw investors as the inflation battle takes shape under the new administration. For those investors seeking the added security that gold could add to their portfolios in 2009, both GDX and FSAGX, with their solid track records and investor interest, are good places to start.

    ==============================================

    My Note: Mutual Funds (and there are many in addition to the above), are a good way to get a nice spread (basket) of different Gold Miners. In addition, I personally like to have holdings in Individual Companies too! I have 2 different Mutual Funds, in addition to holdings in many of the above mentioned companies. I also like a lot of the mid tier and junior Gold Miners too. I generally try to invest in companies that have production (or about to produce), with a lot of cash on hand (due to financing difficulties for comapnies). The whole sector has been beaten down in prices and if you look carefully, you can find many companies right now that are selling at or for less than actual book value. Personally, I am loading up! As always, do your due diligence and read all the prospectuses; and/or consult your investment advisor.

    ==================================================

    Kinross Raises More Capital; Gold Miners Look Strong – Seeking Alpha

    By: Marc Courtenay of Check The Markets.com

    Kinross Gold (NYSE:KGC), one of the world’s best performing gold stocks, announced a public equity offering of 20.9 million common shares at $17.25 per share, with gross proceeds of about $360.5 million, to enhance the company’s capital position following the funding of recent acquisitions.

    In 2008, the gold and silver miner bought Aurelian Resources for around $809 million. Since that time, the shares of stock have had average daily volume of over 11 million shares on the NYSE and traded in a 52-week range of $6.85-$27.40.

    The Canada-based company has also granted the group of underwriters, led by UBS Securities Canada Inc., an overallotment option to purchase up to an additional 3.135 million common shares at the offering price. This option is available for 30 days after the offering closes. If this option is excercised in full, it will bump up the total proceeds to about $414.6 million.

    The offering is scheduled to close on or around February 5, 2009. The company has 665 million shares outstanding.

    Kinross ranks as number one global gold pick among a number of analysts and investors. Production for the group is anticipated to grow around 30% this year to around 2.45 million ounces.

    The new money now being raised is targeted for general corporate purposes after recent acquisitions depleted around $180 million of Kinross’s existing cash. Just two months ago, Kinross shelled out $250 million on a 6 million ounce gold deposit in Chile.

    The last quarter’s earnings growth was up an impressive 64% year-over-year, the balance sheet looks better than average with a total debt-to-equity ratio of just .017 and total cash of over $720 million.

    The Kinross acquisition may have upped the tone for other gold miners. Harmony Gold (NYSE:HMY), the world’s fifth biggest gold miner by ounces produced, on December 22 announced the raising of R979 million before costs, by placing 10.5 million shares at an average price of R93.20 each between November 25 and December 19 2008.

    The fresh capital is earmarked mainly to further pay down Harmony’s debt, which is targeted, on a net basis, to be around zero by mid-2009.

    Among other capital raisings, during November, Agnico-Eagle Mines (NYSE:AEM), a leading Tier II gold digger, raised $252 million in a seemingly effortless offering.

    Overall, when it comes to healthy, proactive and well-managed gold mining companies, the offerings are “in response to strong investor demand.”

    Although right now I have both a long and a short position with KGC, I won’t be buying any more until the price per share corrects at least 20% below present levels. But I’m impressed with both the fundamentals of Kinross and the way the investment community views them so favorably.

    KGC, along with Goldcorp (NYSE:GG), Barrick Gold (NYSE:ABX), Yamana Gold (NYSE:AUY) and IAM Gold (NYSE:IAG) are shares I want to be accumulating for the year ahead.

    The market volatility should help us to buy at lower prices, but the whiff of future inflation and the popularity of gold as a monetary alternative may keep share prices from falling as low as I would like. Patience though, is usually rewarded.

    Disclosure: Author holds both a long and short position in KGC

    ==================================================

    Next – Do we have a potential Takeover or Meger Forming? – Read this next article… 

    Flush Kinross Likely Looking for a Deal with Yamana-Credit Suisse- Seeking Alpha

    Source: Financial Post Trading Desk

    If Kinross Gold Corp. (KGC) had $705-million in cash at the end of the third quarter, why did it decide to raise another $360-million in a bought deal offering of 20.9 million common shares at $17.25 each?

    The company said it will use the money to bolster its capital position and for general corporate purposes, but investors are surely wondering if any acquisitions are in the making.

    An over-allotment option of 3.14 million shares would bring total proceeds from the offering to $415-million. Credit Suisse analyst Anita Soni also noted that Kinross is expected to have another $541-million in operating cash flow in 2009 (based on $700 per ounce gold), while it has $700-million in obligations this year (including capex of $460M).

    “Kinross is well funded with its current cash and cash flow position and does not require additional funds for its current pipeline of growth,” she told clients, adding that the company is strengthening its coffers to capitalize on acquisition opportunities to shore up its growth profile.

    Ms. Soni said “tack on” acquisitions like the Lobo Marte gold project deal with Teck Cominco Ltd. (TCK) for about $250-million, plus a royalty, in November, are possible. However, she also said a larger transaction in the senior or mid-tier space could surface, with Yamana Gold Inc. (AUY) and Teck’s Pogo mine as likely candidates.

    Ms. Soni said:

    Yamana has a good project pipeline but it does not have the near-term capital to fund that growth. An acquisition of Yamana would deliver a project pipeline and growth from 2009-2011 even using our conservative forecasts for Yamana. It is also likely that Kinross would be able to realize additional ounces beyond what we forecast for Yamana given Kinross’s ability to fund growth.

    Yamana’s current multiple based on metal and share prices is around 1.2x, while Kinross is at 1.5x.

    The analyst added that Agnico-Eagle Mines Ltd. (AEM) is too expensive, while Goldcorp Inc. (GG) and Barrick Gold Corp. (ABX) are too big in terms of market capitalization.

    ==================================================

    That’s it for today, Gold now up $19 at $878/oz! – Good Investing- jschulmansr

    Dare Something Worthy Today!

    Share this:

    • Share on Reddit (Opens in new window) Reddit
    • Share on Facebook (Opens in new window) Facebook
    • Share on LinkedIn (Opens in new window) LinkedIn
    • More
    • Share on X (Opens in new window) X
    • Share on Pinterest (Opens in new window) Pinterest
    • Share on Tumblr (Opens in new window) Tumblr
    • Print (Opens in new window) Print
    • Email a link to a friend (Opens in new window) Email
    Like Loading...

    Are We Getting Ripped Off? Latest Bailout and Gold News

    21 Wednesday Jan 2009

    Posted by jschulmansr in agricultural commodities, alternate energy, Austrian school, Bailout News, banking crisis, banks, Barack Obama, bear market, bull market, capitalism, central banks, Comex, commodities, communism, Copper, Currencies, Currency and Currencies, deflation, depression, dollar denominated, dollar denominated investments, economic, economic trends, economy, Federal Deficit, Finance, financial, Forex, Fundamental Analysis, futures, futures markets, gold, gold miners, How To Invest, How To Make Money, inflation, Investing, investments, Latest News, Make Money Investing, Markets, mining companies, mining stocks, Moving Averages, oil, palladium, physical gold, platinum, platinum miners, Politics, precious, precious metals, price, price manipulation, prices, producers, production, rare earth metals, recession, Religion, silver, silver miners, spot price, stagflation, Stocks, Technical Analysis, Today, U.S. Dollar, volatility, warrants

    ≈ 3 Comments

    Tags

    agricultural commodities, alternate energy, Austrian school, Bailout News, banking crisis, banks, bear market, Bollinger Bands, bull market, capitalism, central banks, China, Comex, commodities, communism, Copper, Currencies, currency, deflation, depression, diamonds, dollar denominated, dollar denominated investments, economic, economic trends, economy, Federal Deficit, financial, Forex, futures, futures markets, gold, gold miners, hard assets, heating oil, India, inflation, investments, Keith Fitz-Gerald, Marc Faber, market crash, Markets, mining companies, Moving Averages, natural gas, oil, palladium, Peter Schiff, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, protection, rare earth metals, recession, risk, run on banks, safety, Saudi Arabia, Sean Rakhimov, silver, silver miners, socialism, sovereign, spot, spot price, stagflation, Technical Analysis, timber, U.S. Dollar, volatility, warrants, Water

    Are We Getting Ripped Off? Read Today’s Post dealing with the Bailout, Gold Price Manipulation and more. I’m back, we have a new President, what does this mean for your investments… Read On and Good Investing! – jschulmansr

    Preventing The Greates Heist In History- Seeking Alpha

    By: Whitney Tilson of Value Investing

    There’s currently an idea to fix the financial system that’s getting quite a bit of traction: an RTC-type program whereby the government would buy $1 trillion of troubled assets from struggling U.S. banks, with the goal of restoring them to health so they can begin lending again, leading to an economic recovery.


    The problem with this idea (let’s call it “New RTC”) is that either the government will pay market prices for the toxic assets – in which case, it will simply accelerate the collapse of our financial system – or pay above-market prices, in which case taxpayers will likely suffer big losses.


    De-Leveraging Is Not Deflation-Seeking Alpha

    By: Paco Ahigren of Ahigren Multiverse

    “Inflation, as this term was always used everywhere and especially in this country, means increasing the quantity of money and bank notes in circulation and the quantity of bank deposits subject to check. But people today use the term `inflation’ to refer to the phenomenon that is an inevitable consequence of inflation, that is the tendency of all prices and wage rates to rise. The result of this deplorable confusion is that there is no term left to signify the cause of this rise in prices and wages.”

    — Ludwig von Mises

    It’s true that just about every asset class is coming down in price right now. This, however, is not deflation — as I have said so many times recently, much to many readers’ unqualified chagrin. To the contrary, these declines are the products of de-leveraging — not deflation — and the distinction is nearly incalculably important, although the subtlety seems to elude even the most astute these days.

    If the previous premise is true (which it is), any removal of money from the economy would eventually result in an increase in the value of our currency, relative to everything else. And that, in turn, would eventually translate into lower prices in dollars. But that’s clearly not what is happening. No, the Fed is printing money, sending the amount in the economy higher than ever seen in U.S. history. That’s not deflationary. That’s inflationary.

    Just so you’ll know, here’s the definition of inflation I’m using. And before you pooh-pooh it with too much eagerness, remember that one of its authors, F.A. Hayek, won the Nobel Prize in economics in 1974.

    Look, the thing we should be worried about is relative value, not “inflation,” per se. It’s not about the growth of M0, or M1, or M2 (or even M3, if you keep up with shadowstats.com), so much as it is about what the money supply is doing relative to everything else that is happening. I know assets are falling in price — believe me, I get no shortage of reminders every single day. But the amount of money in the system — not just M0 — is increasing at a tremendous rate. I won’t argue that the relative value of things like real estate and equities are going to continue to drop — maybe even dramatically, and for a long time — in terms of demand (or lack thereof). No, what I’m most concerned about is that demand will stay extremely low, and yet prices will rise anyway because of the increase in the amount of money in the system.

    But it’s not just money; it’s also Treasuries. The Fed has specifically stated that its objective is to stimulate “inflation” (by its definition). It wants prices to rise, and it’s going to do everything it can to find success. But the amount of money in the system is unprecedented. When the Treasury bubble starts to collapse, yields are going to explode. Yes, the Fed will probably print more money to buy down the long-end of the curve, but how long will that work? Some people say years, but how? Do you really think the Chinese and the Japanese are going to keep funding that sort of behavior? Or even more importantly, do you think they’re just going to sit on their current holdings? Probably not, and if they start dumping Treasuries, yields are going much higher.

    It’s not a matter of if this is going to happen. Yields can’t stay where they are for any sustained amount of time, and once they start rising, so will prices. But will demand for, say, houses have increased? No. Cars? No. Boats? Televisions? No. Why? The American consumer is tapped out.

    Credit card companies are tightening limits prodigiously. Teaser rates are all but gone. Home equity has dried up. The consumer has driven two-thirds of our economy for at least the last few decades, and now the consumer is dead. There’s another aspect to this that I won’t go too deep into: the American consumer protects his or her credit score for one reason — to obtain future credit. But the consumer also knows that loans have dried up — not just today, but for the very distant future as well. You know these consumers have to be thinking about defaulting; if they can’t get loans anyway, why would they not default on thousands of dollars in unsecured credit card debt? I plan on writing more about this in future articles, but suffice it to say, I think credit card companies are going to give us the next blow to our collective stomach, and it’s going to hurt.

    So here we have a situation in which demand is gone, and yet prices and rates are rising — because of inflation (printing money) and the Treasury collapse. And that’s the point: it’s not going to come from just one source. It’s not just going to be inflation (printing money). It’s not just going to be the collapse in Treasuries. It’s not just going to be the nearly unfathomable costs of the stimulus packages that are coming online in the next two years. It’s going to be the confluence of all of it. And if I’m right about the continued deterioration in credit markets, things will be even worse.

    You think it’s not different this time? Add it all up, in real dollars — the staggering amount of debt, the parabolic rise of currency in the system, the annihilation of real-estate investment, and the demise of the consumer. $8.5 trillion committed to bailouts and stimulus packages. Oh, yes it is different this time. It’s very different.

    Credit cards didn’t even exist in 1930, and the dollar was backed by gold. Credit cards barely existed in 1973. Nixon had just taken us off the gold standard, and look what happened? Volcker was immensely lucky to have stopped hyperinflation, and look at the extreme measures he had to employ to do it.

    Of course, every time I bring all of this up — which is a lot lately — somebody starts talking about the velocity of money. And pretty soon after that, somebody starts talking about the multiplier effect.

    Yes, the U.S. employs a fractional reserve system, and while that system certainly lends to rising prices and yields, the amplifier effect is not inflation. Like the printing of money, the fractional reserve system is only one ingredient in the poison that lends to the ultimate catastrophe inspired by central banks: rising prices and increased costs of borrowing.

    And then there’s velocity…

    While I am eternally grateful to my critics for forcing me to defend the theories I hold dear, I sometimes fatigue of the incessant snapping at my heels by people who want me to know that the velocity of money has slowed down. I know the velocity of money has slowed. It doesn’t matter. It’s not going to stay this low for long, and when it starts speeding up, it’s not going to be a “good thing.” Treasuries are going to break, rates and prices are going to rise, and all that money pressing against the dam is going to find a crack. Why? It has to. People will flee from dollars that are losing value. They will extract all the dollars sloshing around the system, and they will buy commodities and durables in order to preserve the value of their wealth.

    Remember, just because the dollar is losing value does not mean that the concomitant subsequent rise in certain asset classes necessarily means that demand for all assets has increased dramatically — as it did during previous eras of easy money. Demand for assets economy-wide can continue to wane even as people spend dollars as fast as they can get them in the midst of rising prices. And this is a very important distinction: prices can rise because of demand, but prices can also rise because of excessive increases in the amount of money in the system. If prices are rising without a simultaneous increase in demand, well, I can’t think of a more dangerous economic environment to be in.

    You don’t believe it can happen? You think there’s a huge demand for houses, cars, and boats in Zimbabwe? Prices there are rising exponentially, but there is very little demand for assets — other than staples, of course. What do you think their velocity of money is?

    The other day I wrote that Treasuries and the dollar are not “safer” than gold, and for my efforts I was heckled by several readers. Ultimately, however, flight-to-quality will seek the true risk-free rate of return, and this is yet another factor that will contribute to the imminent ferocity of the move that’s coming. Once Treasuries unwind, people and institutions will scramble to find a place to put the money they had once placed in the “safety” of U.S. government debt. And unless you know of a medium whose historical consistency and safety surpasses gold’s, that will be the place investors find haven.

    Just for future reference: when I say the dollar’s going to fail (which it is), and you’re hovering over your keyboard, poised like some bird-of-prey, ready to strike me with all the ire of God-upon-Sodom, will you try to remember that I acknowledge velocity is, at least for the time-being, near zero. Will you also try to remember that I don’t believe the massive increase in currency alone will not be responsible for imminent rising rates and prices? In fact, I think Treasuries are going to play a greater role in the beginning.

    Also, I agree with many of you that my timing may be a bit premature, and I exited my TBT after the last run-up. Unfortunately, today the stock market and Treasuries are getting crushed as gold rallies. I wouldn’t want to declare myself “right” based just on the behavior of these markets in recent days. That would be stupid. And yet I sit here and watch TBT move higher, wondering if getting out was even more stupid.

    To add to my trepidation, some sort of manager in the South Korean finance ministry came out over the weekend and announced that the time has come to sell U.S. Treasuries. How do you think that made my stomach feel? Of course, Bernanke keeps promising to do battle with the long end of the curve, so maybe he’ll make good on his threat and I can find a point to get back in comfortably.

    Of course, if I miss the move because I listened to some of you cynics. Well, at least I still own gold.

    Disclosures: Paco is no longer short U.S. Treasuries (although he hopes to be again soon). He is long physical gold, and the Proshares Ultra long gold ETF (ticker: UGL).

    Copyright 2009, Paco Ahlgren. All Rights Reserved.

    ================================================

    On Gold Price and Market Manipulation 

    Questions Begging Answers- GoldSeek.Com

    By: Rob Kirby of Kirby Analytics

    To say that markets have been behaving “strangely” recently is an understatement.  In recent weeks and months we’ve been witness to historic lows in sovereign interest rates in-the-face-of record amounts of debt being issued by governments?  We’ve seen the price of gold behave counter intuitively by “not rising” in-the-face-of unprecedented systemic global economic malaise?  Last, but not least, we’ve witnessed a “complete flip-flop” in the traditional pricing of Brent Crude Oil [IPE-London] versus West Texas Intermediate [NYMEX-N.Y.]?  


    So we have the price of gold, the price of crude oil and interest rates – three items vital to the integrity of the U.S. Dollar – ALL trading in total disregard for their underlying fundamentals?


    The following is a thought provoking analysis with commentary:


    The Situation In Gold


    First and foremost it is imperative that everyone realize and understand that Gold “is” Money.  We know that gold is money because every Central Bank in the world carries gold on their balance sheets as ‘an official reserve asset’.


    With that in mind, folks would do well to read one of James Turk’s latest articles titled, The Fed’s blueprint for market intervention .  In this article, Turk offers commentary on a recently unearthed 1961 document from the archives of the late, long-time former Chairman of the Federal Reserve, William McChesney Martin Jr. which details in the Fed’s own pen; their plans to intervene surreptitiously in the currency and gold markets to support the dollar and to conceal, obscure, and falsify U.S. government records so that the intervention would not be discovered.  In Turk’s words,


    “In short, [the newly unearthed document] lays out what the Treasury and Federal Reserve needed to do in order to begin intervening in the foreign exchange markets, but there is even more. This document plainly shows what happens when government operates behind closed doors. It also makes clear the motivations of the operators of dollar policy long described by the Gold Anti-Trust Action Committee and its supporters — namely, that the government would pursue intervention rather than a policy of free markets unfettered by government activity. The run to redeem dollars for gold had put the government at a crossroads, forcing it to make a decision about the future course of dollar policy. This paper describes what the government would need to do by choosing the interventionist alternative.

    This document provides primary, original source supporting evidence that GATA has been right all along.” 


    In Feb. 2007 here’s what the Royal Bank of Canada’s Chairman, Tony Fell had to say, confirming unequivocally that gold is money,


    “At Royal Bank of Canada, we trade gold bullion off our foreign exchange desks rather than our commodity desks,” says Anthony S. Fell, chairman of RBC Capital Markets, “because that’s what it is – a global currency, the only one that is freely tradable and unencumbered by vast quantities of sovereign debt and prior obligations.
    “It is also the one investment and long-term store of value that cannot be adversely impacted by corrupt corporate management or incompetent politicians,” he adds – “each of which is in ample supply on a global basis.”


    In short, says Fell, “don’t measure the Dollar against the Euro, or the Euro against the Yen, but measure all paper currencies against gold, because that’s the ultimate test.”


    Fell’s admission coupled with the recently unearthed account of the Fed’s game plan shows that gold “is” and always has been feared as competition for the U.S. Dollar and a game plan has long been in place to thwart it.  This explains why economic data has been falsified and the price of gold has been surrepticiously managed and interfered with by the United States Treasury and the Federal Reserve.


    The mounting evidence is this regard is so compelling that from this point forward any ‘economist’ attempting to explain our current situation without prefacing their explanation with an EXPLICIT ACKNOWLEDGEMENT that our capital markets are not free and are in fact RIGGED by officialdom – their analysis is not worth the time to read it.  In this regard, perhaps never have more prescient words been uttered than GATA’s Chris Powell in Washington in April, 2008 – when he opined, There are no markets anymore, just interventions.


    The recent decoupling in price of gold as measured by the spread between the futures price and the cost to obtain physical ounces is a stark reminder that smart money is beginning to repudiate fiat money by seeking tangible ownership of goods perceived to posses value instead of derivative ‘promises’ to deliver the same.


    The Oil Picture


    Back in June, 2007, Market Watch reported,


    Normally, Brent crude costs $1-$2 less than WTI crude, according to James Williams, an economist at WTRG Economics. At its peak, the price spread between the two topped $5, according to his data.


    The article went on to explain,


    WTI usually trades at a premium to Brent “because of the slightly higher quality, and the extra journey” oil tankers have to take to get the oil to the U.S., according to Amanda Lee, a strategist at Deutsche Bank. So “WTI minus dated Brent should be roughly equal to the freight rate,” she said. Indeed, “crude-oil prices usually depend on two things: quality and location,” said Williams. “The greater the distance from the major exporters, the greater the price.”


    But here’s what’s happened recently in the global crude oil market:


    Brent Crude trading at a 7 Dollar premium to West Texas Intermediate is like the SUN rising in the west and setting in the east – and no-one asking any questions why?


    Thanks to the unearthing of the Fed’s Playbook Document, referenced above, along with cumulative knowledge of the existence of the President’s Working Group On Financial Markets [aka the Plunge Protection Team]; we know that interference in strategic markets with national security implications is now practiced commonly by the Government and the Fed working together.  No other explanation for this distortion is plausible other than NYMEX regulators like the Commodities Futures Trading Corp. [CFTC – Plunge Protection Team members] are more brazen and actively complicit in market rigging of strategic commodities than their London counterparts. This manipulation is all being done in desperation; to preserve U.S. Dollar hegemony by perpetuating the illusion that inflation is being held at bay.  Ample anecdotal evidence exists in a host of articles – particularly relating to derelict CFTC oversight of COMEX gold and silver futures – archived at kirbyanalytics.com to support this position.


    Spiking VLCC Rates Reflect “The Movement to Tangibles”


    The “unusual” premium for Brent Crude is even more perplexing given that crude oil shipping rates [unlike their dry goods shipping counterparts, as depicted by the Baltic Dry Index] for VLCCs [very large crude carriers] have, as recently as Dec. 2008, been enjoying robust and improving charter rates,


    Last week the spot rate for Suezmax tankers was in the low $40k per day range. Yesterday, I check the rates and they have popped to over $90k this week! VLCC (very large crude carriers, i.e. supertankers) rates have not jumped as much but appear to be following the trend. So what is the deal here? Oil prices are falling and so is the apparent global demand for oil. Are not oil tankers just sitting around idle like the dry bulk carriers?
    The answer is somewhat counter intuitive. The spike in spot tanker rates is actually the result of the low oil prices. Many tankers are being leased on the spot market as storage tanks. Oil producers, for whatever reason, do not want to significantly slow their oil production, but at the same time do not want to sell it for $45 a barrel. So they are leasing tankers to store oil in the hope or belief that oil prices will recover shortly. Two names in news articles that I have read doing this are Royal Dutch Shell and Iran. The majority of the planet’s oil production is owned by national oil companies that have policy and employment as well as financial reasons to keep the oil flowing. So at least in the short term, the current low oil prices are a boon for tanker owners.


    Oil tanker companies, like their dry cargo brethren, can sign their ships to either long term, multi-year leases or charter them on the spot market where they are leased for a single voyage at the current spot rate.


    The fact that “smart money” is now paying elevated prices to lease very large crude carriers [to store physical crude for later sale] is further evidence that faith in fiat money is waning simply because – you can do the same “trade” on paper – utilizing futures – without the bother and nuisance of leasing ships and handling the physical.  Ask yourself why smart money has recently become engaged in buying ‘relatively illiquid’ physical crude oil, in a world allegedly awash in the stuff, for resale at a later date – instead of playing futures, accepting promises and holding cash?


    Smart money is in the process of losing confidence in cash.


    Interest Rates


    It is vital that everyone understand that the function of interest rates in a system of usury is to solemnly act as the efficient arbiter of capital – rising to restrict money / credit growth when the economy overheats and falling to create the opposite when the economy cools.


    Interest rates no longer serve this function.


    As deceitfully disastrous as the surreptitious interventions in the crude oil and gold markets has been – they pale in comparison to the travesty which has been perpetrated through the premeditated hobbling of usury. 


    The roots of this most wicked experiment are traceable to the appointment of Alan Greenspan as Chairman of the Federal Reserve and then to academia – Harvard – where Robert Barsky and Lawrence Summers co-authored an academic research paper in the 1980s titled, Gibson’s Paradox and the Gold Standard.  The “elevator speech” of what the paper examined was the co-relation between bond prices, inflation and the price of gold and, by extension, theorized that interest rates could be driven down [or kept low] – without sacrificing the currency – in the face of and despite profligate monetary policy so long as gold prices declined or did not rise.


    After a stint as Chief Economist at the World Bank, Mr. Summers brought this “theory” to Washington mid-way through the first Clinton Administration [late1993] as Under Secretary of Treasury to Robert Rubin where he began laying the groundwork – with co-conspirators Greenspan, Rubin and Clinton – for the implementation of his “theoretical research”:


    Gold price suppression began in earnest concurrently with changes in how the Office of the Comptroller of the Currency [OCC] begins records the mushrooming growth of derivatives [mostly interest rate swaps which – absent end user demand – only create artificial demand for government bonds]:


    The Federal Reserve acting in cahoots with the U.S. Treasury utilizing the futures pits in N.Y. [COMEX] and the obscenity that has become J.P. Morgan’s Derivatives Book – the Fed / Treasury combo seized control of both the gold price and interest rates.  The mechanics of how interest rate swaps were utilized to suppress interest rates is chronicled and explained in detail at Kirbyanalytics.com in a paper titled, The Elephant in the Room.


    Subscribers are reading about the logical implications, and what comes next, as a result of the market manipulations outlined above as well as actionable suggestions to help insulate your investment portfolio from the inevitable fallout.

    ====================================================

    Gata’s Tenth Anniversary: Gold Manipulation Evidence Mounts-Gold Seek.Com

    By: Bill Murphy of LeMetropole Cafe 

    “Faced with the choice between changing one’s mind and proving that there is no need to do so, almost everyone gets busy on the proof.” … John Kenneth Galbraith

    “An error does not become truth by reason of multiplied propagation, nor does truth become error because nobody sees it.” … Mahatma Gandhi


    GO 


    GATA!


    This week marks GATA’s tenth anniversary of our efforts to expose the manipulation of the gold market. In another few weeks we will mark the tenth anniversary of my appearance on CNBC (interviewed by Ron Insana) … the first and last GATA appearance on the US TV media to date … for once they heard what GATA had to say, we have been blackballed ever since. It also marks a shameful period for the US financial market press, which is now clamoring for answers as to how we ever got in the financial market/banking mess we are presently facing. For that answer they ought to first look at themselves and their dismal way of kowtowing to the rich and powerful, and banning those who are willing to challenge the Orwellian grip on what Americans are allowed to hear and know.

    America is facing quite a dichotomy at the moment. We are on the Inaugural Eve of our first black President, with all the hopes and dreams he is envisioning for our country. At the same time we are enduring the most horrific financial crisis since the Great Depression.

    President-elect Obama, a superb orator, is calling for Americans to pull together to effect the CHANGE he called for in his campaign, and for all of us to contribute individually to make that change happen. He has wisely warned of the tough times ahead while going all-out to ready policies ASAP which he believes are the correct way to remedy the growing economic problems of the day.

    He has also assembled an economic team of advisors which are acclaimed and generally very highly regarded … including Robert Rubin, Lawrence Summers, Timothy Geithner and Paul Volker. Unfortunately for the GATA camp, they are the ALL-PROS of the gold price suppression scheme. It is almost like our worst nightmare. On paper it represents anything but change as far as US gold policy is concerned, and has the potential to make our investment lives miserable for years to come. After all…

    *Robert Rubin coined the phrase “US Strong Dollar Policy,” and flaunted the phrase. Rigging the price of gold was that policy’s lynchpin. What else was there? Steve Forbes was on Fox News Saturday talking about how important he believes it is for America to MAKE the dollar strong again. He talked sheepishly about gold in vague terms and referred to Rubin.

    Robert Rubin hatched the gold price suppression scheme while running Goldman Sachs’ operations in London. This was many years ago, when interest rates were very high (say from 6 to 12% in the US). Rubin had Goldman Sachs borrowed gold from the central banks at about a 1% interest rate. Then he sold the gold into the physical market, using the proceeds to fund their basic operations. This was like FREE money, as long as the price of gold did not rise to any sustained degree for any length of time.

    He continued his innovative money ploy as CEO of Goldman Sachs in New York and then put his Strong Dollar Policy ploy on steroids as Treasury Secretary under President Clinton.*Lawrence Summers followed Rubin as Clinton’s Treasury Secretary, and who could be more qualified to continue Rubin’s gold price suppression scheme than him? After all, while at Harvard he co-authored a paper, “Gibson’s Paradox and The Gold Standard.” The bottom line of Summers’ analysis is that “gold prices in a free market should move inversely to real interest rates.” Control gold and it will help to control interest rates.

    Obama has designated Mr. Summers to be the Director of the U.S. National Economic Council.

    *Which brings us to Timothy Geithner, who is President-elect Obama’s nominee to be U. S. Treasury Secretary. Geithner was named president and chief executive officer of the Federal Reserve Bank of New York on November 17, 2003. In that capacity, he serves as the Vice Chairman and a permanent member of the Federal Open Market Committee, the group responsible for formulating the nation’s monetary policy.

    Mr. Geithner joined the Department of Treasury in 1988 and worked in three administrations for five Secretaries of the Treasury in a variety of positions. He served as Under Secretary of the Treasury for International Affairs from 1999 to 2001 under Secretaries Robert Rubin and Lawrence Summers.

    Geithner is also happens to be a member of the Bank for International Settlements and since 2005 has been Chairman of the Committee on Payment and Settlement Systems. You might want to see what The CPSS undertakes “at their own discretion” as listed here:

    http://www.bis.org/cpss/index.htmLike outgoing Treasury Secretary Hank Paulson, Tim Geithner is a graduate of Dartmouth College. Talk about knowledge of the gold price suppression scheme!

    *And then there is the venerable Paul Volcker, who so effectively brought down runaway inflation in the US, starting in 1980. His one regret:

    “Joint intervention in gold sales to prevent a steep rise in the price of gold (in the 1970s), however, was not undertaken. That was a mistake.” … Former Federal Reserve Chairman Paul Volcker (writing in his memoirs).

    All-Pros? All-World is more like it when it comes to devotees of suppressing the price of gold. Outside of Volcker, the other three are those most responsible for making it happen in the first place.

    So what’s the point? To get us all depressed over what lies ahead? NO, just the opposite.

    On December 18th, on GATA’s behalf, I met with Bart Chilton, a CFTC commissioner who showed interest in hearing what we had to say. There were three others from the CFTC in attendance, including Elizabeth L. Ritter, Deputy General Counsel of that organization.

    From my MIDAS commentary later in that afternoon…

    Bart listened intently and took notes, as did one of the others, and asked numerous questions. Basically, I laid out our GATA presentation as I explained in the Sunday Midas. I am not going to get into all the details of what they said, as we will see what takes place in the months to come … except to say that I chuckled when saying to them if they really wanted to comprehend what the real gold price suppression scheme is all about, all they have to do is go to their new proposed Chairman … at the right time. No one knows what is going on better than he does.

    (Insert- Gary Gensler was nominated that day to be the new chairman of the CFTC. Gensler was Undersecretary of the Treasury (1999-2001) and Assistant Secretary of the Treasury (1997-1999).

    Gensler spent 18 years at Goldman Sachs, one of the ringleaders of The Gold Cartel, making partner when he was 30, becoming head of the company’s fixed income and currency operations in Tokyo by the mid-90’s.

    As the Treasury Department’s undersecretary for domestic finance in the last two years of the Clinton administration, Gensler found himself in the position of overseeing policies in the areas of U.S. financial markets, debt management, financial services, and community development. Gensler advocated the passage of the Commodity Futures Modernization Act of 2000, which exempted credit default swaps and other derivatives from regulation.

    Could The Gold Cartel have recruited a better ALL-PRO/ALL-WORLD man for their team? It is also important to keep in mind that chairman of the CFTC is one of the four members of the President’s Working Group on Financial Markets. Now why does a bureaucrat need to participate with the President and US Treasury Secretary on the markets? I thought the CFTC was supposed to regulate them, not be a part of policy.)

    I did not hold back and said the main culprit of The Gold Cartel was our own government (their own boss), who has been in league with bullion banks like JP Morgan Chase, and others, to suit their own hidden agenda….

    I was very impressed with Bart Chilton (very sharp guy) and he mentioned that my trip to D.C. would not be in vain.

    ***

    What I stressed most at the meeting was that the gold price suppression scheme would not survive another four years, over the length of Obama’s elected term … and presented lengthy documentation to prove my point … meaning The Gold Cartel would run out of enough available central bank gold to meet a growing annual supply/demand deficit over the next four years. The bottom line was that Obama could stop the gold price manipulation scheme now and allow the price of gold to trade freely, thereby letting the Bush Administration be the fall guy; or he could let his economic team persuade him to carry on the status quo, in which case the price of gold will blow sky high in the years ahead, and he would have to take the blame for the resulting ramifications … especially when the gold scandal becomes a huge public ordeal.

    What better way for Obama himself to understand the true gold situation than to ask his top economic advisors what the real deal is. If GATA is correct, and we have been on target for years, the U.S. has a BIG problem when it comes to its gold reserves (how much of it has been encumbered and is therefore GONE?) That is an essay unto itself, with many variables to be discussed, and for another time. All Obama has to do is get the five above-mentioned gentlemen in a room and get right to the nitty-gritty. They can start with the extensive package I handed to Bart Chilton, who is a member of the Obama transition team, and someone who once worked for Tom Daschle, formerly the Democratic leader in the Senate for ten years, and is now Obama’s Secretary of Health and Human Services nominee.

    What Bart Chilton does with what I gave to him is his business, but since he told me my visit would not be in vain, I assume GATA’s extensive presentation did not go into the dumpster.

    Meanwhile, in GATA’s tenth anniversary year, we are making our own call for CHANGE, and are pressing on. Obama has stated over and over again he wants THE PEOPLE to be represented and asked us to give him input. Who has more pertinent input go get to him than our camp? Therefore, we are asking everyone interested in a free gold market to make a renewed effort to further disseminate our decade’s worth of evidence of gold market manipulation into the public domain by contacting the financial market media and to others in the Obama transition team (if you have any contacts).

    I know how frustrating it has been to get the jaded financial market media to listen to, and then acknowledge, what we have to say, but that was yesterday and perhaps times have changed due to the growing financial market crisis, and yearning to understand how we got here. After all President-elect Obama is urging for “government accountability” and “transparency.”

    This call to arms has been instigated by the dramatic and sudden discovery of an important document buried in the Federal Reserve’s archives by writer and researcher Elaine Supkis. This document is posted on her blog at:

    http://emsnews2.wordpress.com/2009/01/15/1961-top-
    secret-fed-reserve-gold-exchange-report/

    The document, which is marked “Confidential,” is from the papers of William McChesney Martin, Jr., and this collection is held by the Missouri Historical Society. A scanned image of the original document is posted by the Federal Reserve Bank of St. Louis at the following link:

    http://fraser.stlouisfed.org/docs/histor ical/martin/23_06_19610405.pdf

    Most importantly, GATA consultant James Turk has brilliantly dissected this document in an essay titled, “The Federal Reserve’s Blueprint for Market Intervention,” which has been served at The Matisse Table and at www.GATA.org…

    http://www.gata.org/node/7095The title of this confidential report is:

    Confidential – – (F.R.)
    U.S. Foreign Exchange Operations: Needs and Methods


    James Turk notes:

    In short, it lays out what the Treasury and Federal Reserve needed to do in order to begin intervening in the foreign exchange markets, but there is even more. This document plainly shows what happens when government operates behind closed doors. It also makes clear the motivations of the operators of dollar policy long described by the Gold Anti-Trust Action Committee and its supporters — namely, that the government would pursue intervention rather than a policy of free markets unfettered by government activity. The run to redeem dollars for gold had put the government at a crossroads, forcing it to make a decision about the future course of dollar policy. This paper describes what the government would need to do by choosing the interventionist alternative.

    This document provides primary, original source supporting evidence that GATA has been right all along.

    I have long hoped that a “confidential” document like this one would eventually emerge. There are no doubt countless more like it, as evidenced by the Federal Reserve’s and the Treasury’s refusal to provide all the documents requested by GATA under its recent Freedom of Information Act request. Maybe those documents will eventually see the light of day too.

    ***

    James makes a key point regarding one of the assertions of this report…

    “The basic purpose of such operations would be to maintain confidence in the dollar.”


    James T notes…

    “This statement confirms one of the basic planks of much of the work by me and others that has been published by GATA over the years. The efforts to cap the gold price have one aim. It is to make the dollar look worthy of being the world’s reserve currency when in fact it is not.”

    ***

    This significant report was written some 48 years ago, yet could have been written at any time in the past 10 years during which GATA has discovered blatant manipulation of the prices of gold and silver … as well as noted ludicrous counterintuitive dollar market action, which has been most noticeable in recent days, as our hysterical financial crisis in the US intensifies.

    James Turk’s title says it all: it is a blueprint for the gold price and financial market manipulation so prevalent now. Ironically, there is a common misconception out there that the US is in the financial market mess it is in today because of too much deregulation. To some extent that is very true, as the likes of Secretary Paulson and Gary Gensler urged Congress to allow the US investment banks to increase the allowable debt/credit on their books from 12:1 to 40:1.

    Yet, just as big a problem was the secretive interference in the US financial markets which allowed credit and risk issues to go completely out of control in America … meaning too much secretive market manipulation … and in a hidden way, too much regulation. Had the gold market not been artificially suppressed and allowed to trade freely, the price would have soared these past years, interest rates would have risen dramatically, and there would have not been the reckless investment bank shenanigans that have put our financial system in such peril. Simplistically, it is generally acknowledged that if gold had been allowed to keep up with inflation for the past 28 years, the price would be over $2,000+ per ounce. The GATA camp knows why it is not there RIGHT NOW!

    Had the Plunge Protection Team (Working Group on Financial Markets) not stepped up their constant Hail Mary play activity after 9/11 to drive the DOW mysteriously higher in the last hour of trading on the New York Stock Exchange, the market probably would have broken down much earlier than it did and given the investing public more of a clue that something was wrong, instead of the misleading Stepford Wives drill that “Everything is fine.”

    What is profoundly disturbing about the discovery of this confidential document is it fits in with much grander conspiracy theories than where GATA is coming from. Since this document, based on what has happened, really is a blueprint for market manipulation since 1961, it feeds into the worst fears of those who are constantly on the case about the Bilderbergers, Council on Foreign Relations, Trilateral Commission, and so on. This document to William McChesney Martin, Jr. is EXACTLY what I have been seeing and reporting over the past decade … not that much different than those who pointed out the Madoff Ponzi scheme during the same period of time. To learn that this market deception and manipulation was conceived when I was a freshman in high school is almost beyond comprehension, especially since the Wall Street crowd hasn’t permitted a serious discussion about it ALL THIS TIME! Nor has our government allowed a true independent audit of US gold reserves since the Eisenhower Administration in 1955.

    It also feeds right into the scary notion revealed in a famed President Clinton comment that goes something like … “I didn’t realize I wouldn’t be in control here when I became President.” … meaning there were far more powerful background forces pulling the strings and on how he must operate.

    GATA doesn’t want to go there, but based on this new discovery, it certainly opens up further comments for fair game, even for some of GATA’s Board of Directors. Adrian Douglas (an oil industry consultant who is presently off to Angola) sent the following email to James Turk:

    James,
    Congratulations. This was an excellent analysis. What a stunning document! Real dynamite.

    It got me thinking as to whether the heist they have pulled is bigger than we think. The BIS as we know, and as mentioned in this memo, is the organization that allows for cooperation behind the scenes of the Central banks. We know they went private to prevent any need for public disclosure seeding the opportunity for Reg Howe’s lawsuit. We have plenty of evidence that Central Bank gold holdings have been depleted. We keep saying that the gold is “gone”. But what do we mean by “the gold is gone”? Gold is not like crude oil, expensive wine, even silver… it does not get consumed. It has not “gone”; it has changed ownership. The Central Banks leased out gold to the bullion banks. Now who did the the bullion banks sell the gold to? We know that the bullion banks can’t get the gold back. If the central banks ask for the gold back the bullion banks can declare bankruptcy or settle in cash. How convenient! The Central bank gold has gone into someone else’s hands that are unknown and the loss will eventually be written off. We know that Central Banks are owned or controlled by some of the richest families and/or entities in the world. Is it possible that these “bankers” can benefit from a fiat Ponzi scheme while it can be maintained AND still end up with the gold in which case they can benefit from a return to a gold standard and when the gold standard eventually gets abused and abandoned in the future they will play the whole fiat game over again? It would certainly require cooperation between central banks to pull off such a heist.

    It would be great to have the whole world sitting in a room and ask those who own more than 10 million ozs of gold to raise their hands!

    The crime may be more than manipulating the price of gold to “defend the US dollar” and concealing the evidence from the public. The Cartel may well have aided and abetted embezzlement of the citizens’ gold of the Western world. And who ever has it, they bought it perfectly legally from the bullion banks with fiat currency.

    This seems to make sense because Central bankers and the “elitists” (Rockefellers, Rothchilds, Morgans, Mellons, Carnegies, Vanderbilts etc etc) are not stupid. They must know gold is real money. They can study monetary history too. The fiat money game in this context is a decoy for the theft of sovereign gold.

    It is not without precedent, the great inflationist, John Law, was arrested escaping with a coach loaded with gold and silver!

    Is this a bridge too far in conspiracy theory?
    Cheers
    Adrian

    Which provoked this reply from another GATA Board member, Catherine Austin Fitts (Assistant Secretary of Housing/Federal Housing Commissioner at the United States Department of Housing and Urban Development in the first Bush Administration)…

    Adrian:
    My hypothesis since 2001 is that the NWO is shifting assets out of sovereign governments and shifting liabilities back in. The goal is to reengineer global governance into the hands of private banks and corporations in a manner that dramatically centralizes control. This is why the creation of a genetically controlled seed and food supply, etc.
    To achieve such centralization requires the centralization of the gold and silver stores. Whoever has the gold has the most powerful financial asset. So if you want a new centralized currency, you need a monopoly on gold and silver. I think part of the end game is to shift back to something involving some kind of gold standard.


    If you use fiat currency to acquire ownership and control of all the real assets on the planet, then you need a gold standard to make sure you keep them.


    So, it would not surprise me to see G8 and GATA start to move into alignment, strange as it may sound.
    Catherine


    Neither opinions are official GATA viewpoints, but they are intriguing, eye-opening and worth pondering.

    When I met with Bart Chilton I said GATA’s high command is just a bunch of proud Americans who have stumbled across a profoundly disturbing situation. I showed the four CFTC individuals in attendance GATA’s full-page color ad in the Wall Street Journal on January 31, 2008. It was titled, “Anybody Seen Our Gold?” …

    http://www.gata.org/node/wallstreetjournalSome of you are very familiar with this copy in the ad…

    “The objective of this manipulation is to conceal the mismanagement of the US dollar so that it might retain its function as the world’s reserve currency. But to suppress the price of gold is to disable the barometer of the international financial system so that all markets may be more easily manipulated. This manipulation has been a primary cause of the catastrophic excesses in the markets that now threaten the whole world.”

    … and then…

    “Surreptitious market manipulation by government is leading the world to disaster.”

    The DOW was a little below 13,000 at the time. I mean how right could we have been? Yet the US financial market press completely ignored this very visible ad. There was not even a query of what we were talking about and why we would spend $264,400 to make such a warning.

    So now we are fast forwarding virtually a year later and the US financial markets and economy ARE in chaos. If soon to be President Obama really wants CHANGE and TRUTH, we will give him critical input on one way he can effect what he says he is looking to do.

    To increase the likelihood that what GATA has discovered actually reaches him, GATA is asking all who read this, and agree with GATA, to make some small effort to get this commentary to the financial market media in the world, especially the US financial market press.

    That means contacting writers and media outlets such as the Wall Street Journal, Washington Post, Washington Times, New York Times, Forbes, Fortune, CNBC, CNN, Reuters, Bloomberg, the AP, Fox News, Newsweek, Time, etc. In addition, sending this Tenth Anniversary GATA commentary to widely-followed internet bloggers would also be helpful; perhaps stirring up so many out there who are searching for the reasons behind what has happened financially and economically in the US and why.

    In such troubling times, Obama’s coming Presidency has given optimism and hope to many. For that to occur there must be true change, the desires for which have swept him into office. President-elect had some army. And GATA has its army.

    Please take a little time and make just a small effort to help Obama help himself, even if our issue is the last one he is thinking about at the moment. Funnily enough, it ought to be one of the first, as it is one of the most prominent ones which got us into the financial market/economic nightmare we are in today. After all, it is many of the same bullion banks/investment houses our government is bailing out that were so instrumental in the gold price suppression scheme. Our mission is to let him know, via all sources possible, what the heck has happened and continues to go on.

    Bill Murphy
    Chairman
    Gold Anti-Trust Action Committee

    Copyright (c) 1999 – 2009

    Le Metropole Cafe, Inc

    ================================================

    John Doody: A Winning Situation For Gold Stocks- Seeking Alpha

    Source: The Gold Report

    By: John Doody of The Gold Stock Analyst

    Heralded as “the best of today’s best,” John Doody, author and publisher of the highly regarded Gold Stock Analyst newsletter, brings a unique perspective to gold stock analysis. In this exclusive interview with The Gold Report, Doody ponders the efficacy of the Keynesian approach, makes a case for gold equities and explains how the GSA Top 10 Stocks portfolio has outperformed every other gold investment vehicle since 1994.

    The Gold Report: John, you’ve stated in your newsletter, Gold Stock Analyst: “It’s clear the U.S. is going down a Keynesian approach to get out of this recession/depression.” I am curious on your viewpoint. Will the Keynesian approach actually work, or will they need to eventually move over to the Chicago School of Free Markets?

    John Doody: A free market approach of letting the crisis resolve itself would work, but would cause too much damage; we’d probably lose our auto industry, and it would take too much time. As Keynes said: “In the long run we’re all dead,” so the government is trying to get a faster resolution. The Treasury is pursuing his fiscal policy idea of deficit spending. They’re borrowing the money to bail out the banks. When Obama’s plan is implemented, which could be another $700 billion in stimulus, it will be funded with more borrowings.

    Bernanke and the Fed are pursuing a loose monetary policy with a now 0% interest rate. There’s actually no way we can not end up with inflation. This is much bigger than ‘The New Deal’ under Roosevelt. And I think that the market disarray over the last several months has confused investors; but when the markets settle down, it’s clear to me that it will be up for gold and gold stocks.

    TGR: Is there any economic scenario that you wouldn’t see gold going up in?

    JD: Basically, we’re pumping money into the system, but it’s just sitting there. It’s not being put to work, so there are those who think that we are going to enter a deflationary era. But I can’t see that. Some don’t like Bernanke, but I think there’s probably nobody better prepared to be in his role.

    Bernanke is a student of the Great Depression and knows the mistakes the Fed made then, such as forcing banks to upgrade the quality of loans on their balance sheets. His approach is to buy the banks’ low quality loans, enabling them to make new loans. They haven’t done much of the latter yet, which is probably a fault of the Fed not requiring the funds received for the junk to be redeployed, but they ultimately will lend more as that’s how banks make money.

    He knows in the early 1930s we went into a deflationary period of falling prices. For three or four years prices were down about 10% annually. He fully understands the risks of that, one of which is the increased burden of existing debt payments on falling incomes. The debt burden is lighter in an inflationary environment and that’s his target. Long term, he knows he can cure inflation; Volker showed us how with high interest rates in the 1980s. But there’s no sure way to cure deflation, and so Bernanke’s doing everything possible to avoid a falling price level. And I think that, because this is a service-driven economy, companies won’t lower prices to sell more goods—they will just lay off more workers, as we’re seeing now. I don’t think we’ll get the price deflation of the ’30s, and I’m sure Bernanke is going to do everything to prevent it.

    TGR: But aren’t we already in a deflationary period?

    JD: Well, we may be to an extent; you can get a better buy on a car. But, to put it in the simplest terms, has your yard guy lowered his price, or your pool guy, or even your webmaster?

    TGR: Yes, but people opt to do things themselves versus paying other people to do it.

    JD: Maybe, but if they do, it won’t show up in prices—it will show up in the unemployment statistics. So if the yard guy, pool guy or webmaster don’t lower prices and their clients become do-it-yourselfers, the effect will show up in unemployment, not inflation data.

    TGR: So if every major country in the world is increasing their monetary supply, we would expect inflation. Will there be any currency that comes out of this to be considered the new base currency, sort of like the U.S. dollar is now?

    JD: Well, that’s the $64,000 question. We don’t really know and, because there’s no totally obvious currency, that is why the dollar is doing well of late. But the dollar is in a long-term downtrend, in part because interest rates in Europe remain higher than here. Higher interest rates, as you know, act like a magnet in attracting investment money, which first has to be converted to the higher interest currency and that bids up its value versus the dollar.

    The Euro represents an economy about the size of the U.S., so there may be some safety there. You could argue for the Swiss Franc maybe, but you know the Swiss banks (Credit Suisse, for example) have had some problems, so we’re not quite sure how that’s going.

    So, to me, the only clear money that’s going to survive all this and go up, because everything else is going to go down, is gold.

    TGR: What’s your view of holding physical gold versus gold equities?

    JD: I only hold gold equities. They’re more readily tradable; when gold goes up, the equities tend to go up by a factor of two or three times. Of course, that works to the reverse, as we know. As gold went down, the equities went down more. But because you hold them in a government-guaranteed SIPC account, it provides ease of trading—you don’t have the worries of physical gold. . .insurance, storage or whatever. You may want to hold a few coins, but that would be about it in my opinion.

    TGR: On your website, your approach to investing in gold equities is to choose a portfolio of 10 companies that have the opportunity to double in an 18- to 24-month period with the current gold price.

    JD: Yes. We don’t really look forward more than 18 or 24 months; but within that timeframe, say a year from now, we could reassess and raise our targets so that, in the following 18 to 24 months, the stocks, while having gone up, could go up more still. There are lots of opportunities to stay in the same stocks as long as they continue to perform well. We’re not a trading newsletter, and as you probably know, the way we define an undervalued stock is based on two metrics.

    One is market cap per ounce. The market capitalization of a company is the number of shares times its price. You divide that by its ounces of production and its ounces of proven and probable reserves, and you see how the company’s data compares to the industry’s weighted averages.

    Second, we look at operating cash flow multiples. Take the difference between the gold price and the cash cost to produce an ounce, multiply that by the company’s production per year, and you get operating cash flow. Divide that into its market capitalization and you get its operating cash flow multiple. We look at that this much the same as one looks at earnings per share multiples in other industries.

    For reference, we last calculated the industry averages on December 29, 2008 for the 50+ gold miners we follow, which is everyone of significance. At that time, the average market cap for an ounce of production was $3,634, an ounce of proven and probable reserves was $194, and the average operating cash flow multiple on forecast 2009 production, assuming $900/oz gold, was 7.4X.

    We focus companies that are below the averages and try to figure out why. An ounce of gold is an ounce of gold, it doesn’t matter who mined it. If you’re going to buy an ounce of gold from a coin dealer, you want to get the cheapest price. Well, if you’re going to buy an ounce of gold in the stock market, you should want to get those at the cheapest price, too. It’s oversimplified, as there are other factors to be considered, but this is a primary screening tool to determine which stocks merit further study. The method works, as the GSA Top 10 Stocks portfolio has outperformed every other gold investment vehicle since we began in 1994.

    TGR: Are all the companies in your coverage producers or have 43-101’s??

    JD: Yes, all are producing or near-producing. They may be in the money-raising stage to build a mine, but they’ve got an independently determined reserve. And that part of the market has done better than the explorers because it has more data to underpin the stocks’ prices.

    TGR: And you focus in on having 10 just because, as you point out in your materials, it allows you to maximum upside at minimum risk (i.e., if one of the 10 goes down 50%, you will only lose 5% of your money). Is your portfolio always at 10 or does it ever expand more than that?

    JD: No, earlier in 2008 we were 40% cash, so it was six stocks. For a couple of months later in 2008 it was 11 stocks. But 90% of the time it’s at 10.

    TGR: What prompted you to be 40% in cash?

    JD: That was when Bear Stearns was rescued in March and gold went to $1000; we were just uncomfortable with that whole scenario. And actually we put the 40% in the gold ETF; so it wasn’t true cash.

    TGR: Okay. And as you’re looking at these undervalued companies, are you finding that there are certain qualifications? Are they typically in a certain area, certain size?

    JD: While we follow Barrick Gold Corporation (NYSE:ABX) and Newmont Mining Corp. (NYSE:NEM) and they’ve both been Top 10 in the past, neither is now. We’re currently looking further down the food chain. There’s one with over two million ounces growing to four million a year. Another has a million growing to two million. So, some are still pretty good sized. And then there are others further down that are either developing mines or are very cheap on a market cap per ounce basis.

    Earlier, one of the Top 10 was selling at its “cash in the bank” price. We’ve had a nice little rally since October and this stock has doubled, but it’s still cheap. It has 9 million ounces of reserves at three mine sites in European Community nations, and it’s not Gabriel in Romania. It has no major troubles with permitting its mines and it was selling at its cash/share. Then the chairman of the board bought 5 million more shares. It was already top 10, but I pointed this out to subscribers as great buy signal. It’s doubled since and will double again, in our opinion.

    TGR: Can you share with us some of the ones that are in your top 10?

    JD: Well, the astute investor would probably recognize Goldcorp (NYSE:GG) as the one at two million ounces growing to four million ounces. Their tremendous new mine in Mexico, Penasquito, which I have been to and written about, is going to average half a million ounces of gold and 30 million ounces of silver a year. It’s going to be the biggest producing silver mine in the world, momentarily anyway, and will produce huge quantities of lead and zinc. At current prices, it’s going to be a billion-dollar-a-year revenues mine, which is enormous. And because of by-products, and even at current prices, the 500,000 ounces of gold per year will be produced at a negative cash cost per ounce.

    TGR: Wow. Because of the credits?

    JD: Because of the by-product credits. Another one would be Yamana Gold Inc. (NYSE:AUY), which is growing from a million ounces to two million ounces. Both Yamana and Goldcorp are in politically safe areas—no Bolivia, no Ecuador, no Romania—none of the places where you have to take political risk. I think we’ve learned enough from the Crystallex International Corp. (KRY) and Gold Reserve Inc. (NYSE:GRZ) situation in Venezuela, where they’re both on portions of the same huge deposit that is probably 25 million ounces or more. It looks to me that the government is going to take it away from them. So, I would just as soon not be involved in that kind of political risk scenario. There’s enough risk in gold just from the mining aspects of it that you don’t have to take chances on the politics too, as in some nations that’s impossible to assess.

    TGR: Yes, another one that is really doing quite well is Royal Gold Inc. (Nasdaq:RGLD). Can you speak about that company?

    JD: Yes. Royal Gold has been GSA Top 10 for 18 months now. We put it on in part because of the Penasquito deposit that I mentioned earlier. Royal has a 2% royalty on that, and 2% of a billion dollars is $20 million a year. Royal is unique in that they haven’t prostituted themselves by selling shares on a continuous basis. They only have 34 million shares outstanding and they will have royalty income this year of about $100 million. Penasquito is just coming on line, so its $20 million per year won’t be fully seen until late 2010.

    Plus Royal pays a dividend. I think it could pay $1.00/share ($0.32 now). Dividend-paying gold stocks typically trade at a 1% yield. A $1.00/share dividend would make Royal a potential $100 stock. That’s my crystal ball down-the-road target.

    Royal is a great play on gold price because they don’t have the aggravation of mining. They have a portfolio of mine royalties, plus a small corporate office. Royal employs 16 people, has $150 million in the bank and over $100 million a year income, which is about $3.00 per share pre-tax. Their biggest cost is taxes.

    TGR: I see also that Franco Nevada Corp. (FNV.TO) has had quite a rise, though they have been kind of tumultuous between November and December.

    JD: Franco is also a stock we like. About half of its royalties are from oil, so that’s why it’s suffered. The original Franco Nevada, as you know, was merged into Newmont for five years, and then they came public again in December ’07. I think it’s a good way to play gold and oil, and I think everybody agrees that oil is not going to stay in the $40 range for long.

    TGR: John, can you give us a few more?

    JD: A couple of smaller ones we like are Northgate Minerals Corp. (AMEX:NXG) and Golden Star Resources Ltd. [TSX:GSC]. Northgate is a misunderstood producer. Everybody thinks it’s going out of business when the Kemess Mine closes after 2011, but it’s actually not. It has 200,000 ounces a year from two mines in Australia and has a potential new mine in Ontario where they’ve just announced a 43-101 with over three million ounces. That’s potentially another 200,000 ounces a year, so we think they’ll remain at 400,000 ounces a year from Canada and Australia, both of which are countries we like. Cheap on our market cap per ounce of production and reserves metrics, it’s trading at an operating cash flow multiple under 2.0X.

    Golden Star has several nearby mines in Ghana with production targeted at about 500,000 ounces in 2009. They’ve been ramping up to this rate for the past year and cash costs have run much higher than plan. If costs can be controlled and production goals met, it’s a takeover candidate for someone already in the country, such as Newmont or Gold Fields Ltd. (NYSE:GFI).

    One thing I think readers should bear in mind is that gold mining will be one of the few industries doing well in 2009. Their key cost is oil, which is about 25% of the cost of running a mine. Oil’s price, as we know, is down about 75% in the $147/barrel high last July. At the average $400 cash cost per ounce mine, that’s a cut of about $75/oz off their costs. That result alone is going to give them an uptick in future earnings versus what they showed for third quarter 2008.

    Something else people may not recognize is that currencies are also falling; many are down 20% to 40% versus the U.S. dollar. All the commodity nation currencies—the Canadian dollar, the Australian dollar, the South African Rand, the Brazilian Real, the Mexican Peso—they’re all down 20% to 40%. When your mining costs in those countries are translated back into U.S. dollars, they’ll be 20% to 40% lower.

    So, the miners are going to have falling cash costs and even if the gold price remains exactly where it is now profits are going to soar. This will be unique in 2009. I can’t think of any other industry in which people are going to be able to point to and say, “These guys are making a lot more money.” I think the increasing profits will get the gold mining industry recognition that it isn’t getting now. Of course I’m a bull on gold because of the macroeconomic picture. When you put falling costs of production together with a rising gold price, you’ve got a winning combination for the stocks in 2009.

    TGR: I was wondering if you could give us something on Silver Wheaton Corp. (NYSE:SLW).

    JD: Well, Silver Wheaton is another royalty company; it’s not a producer. It gets its profit royalties by paying a cash sum up front and $4/ounce on an ongoing basis. It captures the difference between the silver price and $4 an ounce; if silver is $10 and it pays $4, it makes a $6 an ounce profit; at $20 silver, its profit would be $16. Aside from no pure silver miner actually producing ounces as low as $4.00, there’s a lot of leverage to silver price. I am not a silver bull, but because I’m a gold bull I think silver will follow gold higher.

    Silver Wheaton is one of those companies that doesn’t have the issues of actually doing the mining. It has a portfolio of mines that it gets production from, and it owns 25% of the production from Goldcorp’s Penasquito mine that it buys at $4 an ounce, and will average about 8 million ounces a year. It’s just starting up now, but it will really get going in 2010. Silver Wheaton’s share of the total mineralization at Penasquito is 1 billion ounces. There’s 4 billion total ounces of silver there and it bought 25%. So, for a long time—the mine life of Penasquito is over 30 years—it’s going to be a big producing mine for Silver Wheaton.

    TGR: Isn’t there a twin sister to Silver Wheaton in the gold area?

    JD: Well, there’s Gold Wheaton Gold Corp. [TSX.V:GLW]. It’s based on the premise that some companies have a gold by-product. With their primary production in some other kind of metal, some might like to lay off the gold for a $400 an ounce on-going payment and an up-front purchase amount. Yes, some of the same guys are involved. I’m not convinced it’s going to do as well because it’s already got a lot of shares outstanding, and I just don’t like the capital structure as much. I wouldn’t bet against these guys but I’m not a believer.

    TGR: And you said you’re not a silver bull. Why is that?

    JD: We do cover about 15 silver miners, but reason number one for not being a bull is that it’s a by-product. Few mines are built to get just silver; 70% to 80% of silver comes as a by-product to copper, zinc, gold or some other metal. If you’re producing copper, you’re more interested in the copper price than you are in the silver price and you tend to just dump the silver onto the market.

    And second, it’s not a monetary commodity. It is poor man’s gold—but it doesn’t have the universal monetary acceptance that gold does. It has a growing list of industrial uses, but it’s not growing at any rate that’s going to offset the falling use in photography. So, the overall demand for silver is not growing at any great rate. It’s not going to go from 800 million ounces a year to 1.6 billion ounces a year; it may get there in 20 years or 30 years, but that’s not our investment time horizon.

    I think silver just follows gold along; but, in fact, it hasn’t been following gold along because right now silver is trading at a discount to gold. The ratio of gold to silver price, which normally runs around 50–55, is now around 80, so silver might have a little bit of a pop-up if the discount closes. But there are a lot of new silver mines coming on line and maybe that’s why the discount exists. Penasquito is one and Silver Standard Resources Inc. (Nasdaq:SSRI) has a big one starting in 2009. Coeur d’Alene Mines Corp. (NYSE:CDE) has now one ramping up and Apex Silver Mines Ltd. (AMEX:SIL) San Cristobal is now on line at 20+ million ounces per year as a zinc by-product. There’s potentially more silver coming to market than the world really needs. We do recommend Silver Wheaton, but that’s our single play.

    TGR: Can you give us any comments on Minefinders Corporation (AMEX:MFN)?

    JD: Well, you know, it’s in the uncertainty phase as to whether or not the new Delores mine in Mexico is going to work. Now built, it’s just starting up. We like the stock as we think it’s going to work. The question is: will it? Two mines in the area—Mulatos, owned by Alamos Gold Inc. [TSX:AGI], and Ocampo owned by Gammon Gold Inc. (GRS) did not start up smoothly. The market is betting against Delores starting smoothly, but this is the last of the three mines to come on line, and the first two mines—Alamos’ and Gammon’s—did get fixed and are now running okay. So, I think Minefinders has probably learned from the experience of the others, and the mine should start up all right. But, you know, the proof will be in the pudding. If you take its market cap per ounce on the forecast 185,000 ounces of production in 2009, or its almost 5 million ounces of reserves, and compare it to the industry averages we calculate, it’s potentially a double or triple from here.

    TGR: So, the start-up issues of the other two mines, were they politically related?

    JD: No, it was metal related. Processing facilities aren’t like televisions; you don’t just turn them on. It’s more like buying a new fancy computer system that needs to be twiddled and tweaked and loaded with the right programs. And you know, all geology is different, so things seldom start up properly; and, given the long teething problems at the other two mines, that’s sort of been a curse. If Minefinders can beat it and start up on plan, it’s an easy winner in 2009.

    TGR: So, John do you have a prediction on where you think gold will go in ‘09?

    JD: People talk about $2,000 or $5,000—it’s all pie in the sky, you know. Gold might get there; but the bigger question is: what’s the timeframe? Will I be around when gold is $5,000? I doubt it. Will it get there? Probably.

    But we look for undervalued situations no matter what the gold price. And in the ‘90s—you know we’ve been writing Gold Stock Analyst since 1994—in the mid-90s gold did nothing for three years, it traded between $350 and $400. With our methods of selecting undervalued stocks, we had a couple of years of the Top 10 portfolio up 60% and 70% but gold was flat. Until mid-2008 the GSA Top 10 was up almost 800% in the current gold bull market. When gold does go up, the stocks go up more; but, in general, even if gold does nothing, we can still find good buys. Royal Gold is an example of finding winners in a tough market. Made a Top 10 stock at $23 in mid-2007, it gained 60% in 2008 and has doubled over the past 18 months.

    We don’t follow the explorers, in part because there is no data to analyze beyond drill hole results, which are a long way from showing a mine can be built and operated at a profit. For us, the pure explorers are too much like lottery tickets. The producers do exploration and you can get your discovery upside from them. Bema Gold (acquired by Kinross Gold in February 2007) was a Top 10 stock with 100,000 ounces per year of production when it found Cerro Casale and it did very nicely on the back of that find. So, with the smaller producers you can get plenty of exploration upside. You don’t need to focus on the greenfield explorers because it’s just too hard to tell who’s going to win and who’s going to lose.


    John Doody brings a unique perspective to gold stock analysis. With a BA in Economics from Columbia and an MBA in Finance from Boston University, where he also did his Ph.D.-Economics course work, Doody has no formal “rock” studies beyond “Introductory Geology” at Columbia University’s School of Mines.

    An Economics Professor for almost two decades, Doody became interested in gold due to an innate distrust of politicians. In order to serve those that elected them, politicians always try to get nine slices out of an eight slice pizza. How do they do this? They debase the currency via inflationary economic policies.

    Success with his method of finding undervalued gold mining stocks led Doody to leave teaching and start the Gold Stock Analyst newsletter late in 1994. The newsletter covers only producers or near-producers that have an independent feasibility study validating their their reserves are economical to produce.

    ==============================================

    ***All Posts are  not  to be considered Investment Advice, the articles/posts are presented for Informational Purposes. Consult Your Own Investment Advisors and Carefully Research and Read the Prospectus’s before making any Investment.*** jschulmannsr

    As Always Bringing You The Must Have Information for Today’s Gold Markets and Hard Assets Investing- Dare Something Worthy Today Too!  Brought To You By:- jschulmansr


     There is another option, however, which involves debt holders taking a share of the losses. If steps are not taken to ensure that this happens, the greatest heist in history will have occurred: at least $1 trillion will be transferred from taxpayers to debt holders of failed financial institutions. This must not be allowed to happen.

     Mark-to-Market vs. Real Losses

    To understand the government’s dilemma, one must realize that the great majority of the not-yet-recognized losses in our financial system are not short-term, mark-to-market losses that will someday be reversed, but permanent losses. This is a huge misunderstanding that many people, especially those in Washington, seem to be suffering from.

     To understand why the losses are real, consider this simple example: imagine a bank that lent someone $750,000 via an Option ARM mortgage to buy a McMansion in California at the peak of the bubble less than two years ago. Virtually all homeowners with this type of loan will default, thanks to declining home prices, the structure of the loan, and the fact that 70-80% of Option ARMs were liar’s loans. If we assume the house is only worth $400,000 today, then there’s been an actual loss of $350,000. That money will never be recovered. If one considers the millions of toxic loans made during the bubble – subprime, Alt-A, Option ARM and second mortgages, home equity lines of credit, commercial real estate, leveraged loans, credit cards, etc. – it easily adds up to at least $1 trillion in additional, unrecognized very real losses.

     Imagine that New RTC buys this loan for $400,000. In this case, it might not lose money, but then the bank (or the structured finance pool) holding the loan has to immediately realize the loss of $350,000 – and it is certain that the U.S. (and world) financial system has not even come close to marking these assets to what they’re really worth, which explains why they won’t lend, even when given new money. Thus, if New RTC buys these assets at fair value, then the financial institutions suffer the losses – but this would bankrupt many of them. Yet if New RTC pays the inflated prices they’re marked at today, then it (and taxpayers) will suffer huge losses.

    Who Should Bear the Losses?

    To save our financial system, somebody’s going to have bear these losses – the only question is, who? Some fraction of this will certainly have to be taxpayer money, but all of it needn’t be if the government would stop bailing out all of the debt holders.

     Government policy has been all over the map. Among the large financial institutions that have run into trouble (in chronological order, Bear Stearns, IndyMac, Fannie & Freddie, Lehman, AIG, WaMu, Citigroup and Bank of America), in some cases the equity was somewhat protected, while in others was wiped out, and likewise with the debt. Most likely due to the chaos that ensued after Lehman filed for bankruptcy, the current policy, as reflected in the most recent cases of Citi and BofA, is to at least partially protect the shareholders and, incredibly, 100% protect all debt holders, even junior/unsecured/subordinated debt holders.

     The result is at least a $1 trillion transfer of wealth from taxpayers to debt holders. This makes no sense from a financial, fairness or moral hazard perspective. While there’s an argument that the government should protect senior debt holders to preserve confidence in the system (even though they knowingly took risk – after all, they could have bought Treasuries), the junior debt holders got paid even higher interest in exchange for knowingly taking even more risk by being subordinate in the capital structure (of course, equity and preferred equity holders are the most junior). These investors made bad decisions, buying junior positions in highly leveraged companies that made bad decisions, so why should they be protected?

     Moreover, the reckless behavior of debt investors was a major contributor to the bubble. It was low-cost debt with virtually no strings attached that allowed borrowers, especially the world’s major financial institutions, to become massively overleveraged, fueling the greatest asset bubble in history. This was not an equity bubble – unlike the internet bubble, for example, stock market valuations never got crazy – it was a debt bubble, so it would be particularly perverse and ironic if government bailouts allowed equity holders to take a beating, yet fully protected debt holders.

     Case Study: Bank of America

    Let’s look at Bank of America (BAC), which effectively went bankrupt last week (disclosure: we are short the stock). The cost to taxpayers of avoiding this outcome wasn’t the headline $20 billion, but far more – the government is going to take a bath on the $120 billion that it guaranteed – and it’s likely that this is just the beginning of the losses.

     Consider this: as of the end of 2008, BofA had $1.82 trillion in assets ($1.72 trillion excluding goodwill and intangibles), supported by a mere $86.6 billion in tangible equity – 5.0% of tangible assets or 20:1 leverage – and $48.9 billion of tangible common equity – 2.8% of tangible assets or 35:1 leverage (common equity excludes the TARP injection of capital in the form of preferred stock, which has characteristics of both debt and equity). (All data from BofA’s earnings release on 1/16/09; note that these figures include Countrywide, but not Merrill Lynch)

     At such leverage levels, it only takes tiny losses to plunge a company into insolvency. It’s impossible to know with precision what BofA’s ultimate losses will be, but among the company’s loans are many in areas of great stress including $342.8 billion of commercial loans ($6.5 billion of which is nonperforming, up from $2.2 billion a year earlier), $253.5 billion of residential mortgages ($7.0 billion of which is nonperforming, up from $2.0 billion a year earlier), $152.5 billion of home equity loans (HELOCs; about $33 billion of which were Countrywide’s), and $18.2 billion of Option ARMs (on top of the $253.5 billion of residential mortgages; all of which were from Countrywide, which reported that as of June 30, 2008, 72% were negatively amortizing and 83% had been underwritten with low or no doc).

     BofA is acknowledging a significant increase in losses, but its reserving has actually become more aggressive over the past year. From the end of 2007 to the end of 2008, nonperforming assets more than tripled from $5.9 billion to $18.2 billion, yet the allowance for credit losses didn’t even double, from $12.1 billion to $23.5 billion. As a result, the allowance for loan and lease losses as a percentage of total nonperforming loans and leases declined from 207% to 141%.

     So BofA had big problems on its own and then made two very ill-advised acquisitions, the result of which effectively wiped out the company, causing the government to come in and bail it out, at a huge cost to taxpayers. So what price is being paid? NONE! The architect of this debacle, Ken Lewis, is still in place, as is the board that approved everything he did. Ditto with Citi. These banks are just getting do-overs, with the management, boards and debt holders not being touched – the only losers are the common shareholders (to some extent) and taxpayers (to a huge extent).

     Since big losses from Merrill Lynch triggered last week’s bailout of BofA, why are all of its debt holders ($5.3 billion of junior subordinated notes, $31.2 billion of short-term debt and $206.6 billion of long-term debt) being protected 100%, while taxpayers are taking a bath eating Merrill’s losses from its reckless, greedy behavior?! This is madness.

    A Better Solution

    So what’s a better solution? I’m not arguing that BofA (or Citi or WaMu or Fannie or Freddie or AIG or Bear) should have been allowed to go bankrupt – we all saw the chaos that ensued when Lehman went bankrupt. Rather, if a company blows up (and can’t find a buyer), the following things should happen:

    1) The government seizes it and puts it into conservatorship (as Fannie, Freddie, IndyMac and AIG effectively were, to one degree or another);

    2) Equity is wiped out (again, as with Fannie, Freddie, IndyMac and AIG);

    3) However, unlike Fannie, Freddie, IndyMac and AIG (and certainly Citi and BofA), everything in the capital structure except maybe the senior debt is at risk and absorbs losses as they are realized; the government would only provide a backstop above a certain level. This is what happened in the RTC bailout;

    4) Over time, in conservatorship, while the businesses continue to operate (no mass layoffs, distressed sales, etc.), the government disposes of the companies in a variety of ways (just as the RTC did via runoff, selling the entire company or piece-by-piece, etc.), depending on the circumstances (as it’s doing with AIG and IndyMac, for example – these are good examples, except that the debt holders were protected).

    Counter-Arguments

    One counter-argument to my proposal is that we don’t want the government to nationalize banks. I don’t like it either, but the alternative – inject hundreds of billions of dollars of taxpayer money and not take control – is even less palatable. There should certainly be urgency in disposing of the companies, but also the recognition that it could take years, as with the RTC.

     Another counter-argument is Lehman: nobody wants a repeat of the chaos that ensued when the company went under and debt holders were wiped out. But the mistake here wasn’t the failure to protect the debt, but rather allowing the company to go bankrupt, which not only impacted Lehman’s equity and debt holders, but also stiffed Lehman’s countless clients and counterparties. It’s the latter that caused the true chaos. Lehman should have been seized and put into conservatorship, so that all of Lehman’s clients and counterparties could have relied on Lehman (as was done with AIG) – but debt holders would have taken losses as they were realized (which is not being done with AIG).

    A final argument for protecting the debt is the fear of contagion effects: for example, other financial institutions who own the debt might become insolvent (this was probably why Fannie and Freddie subdebt was saved). Also, debt markets might freeze up such that even currently healthy banks might not be able to access debt and collapse.

     Regarding the former, the debt is owned by a wide range of institutions all over the world: sovereign wealth funds, pension funds, endowments, insurance companies and, to be sure, other banks. Some of them would no doubt be hurt if they take losses on the debt they hold in troubled financial institutions – but that’s no reason to protect all of them 100% with taxpayer money.

     As for the latter concern that debt markets might freeze up, causing even healthy banks to collapse, it’s important to understand that right now there is no junior debt available to any financial institution with even a hint of weakness – there’s very high cost equity and government-guaranteed debt. Neither of these will be affected if legacy debt holders are forced to bear some of the cost of the failure of certain institutions.

     Conclusion

    The new Obama administration needs to understand that the greatest heist in history is underway – at least $1 trillion is being transferred from taxpayers to debt holders of failed financial institutions – and take steps to stop it before taxpayers suffer further unnecessary losses.

    =================================================
    Share this:

    • Share on Reddit (Opens in new window) Reddit
    • Share on Facebook (Opens in new window) Facebook
    • Share on LinkedIn (Opens in new window) LinkedIn
    • More
    • Share on X (Opens in new window) X
    • Share on Pinterest (Opens in new window) Pinterest
    • Share on Tumblr (Opens in new window) Tumblr
    • Print (Opens in new window) Print
    • Email a link to a friend (Opens in new window) Email
    Like Loading...

    Latest Obama News and The Ad “They” Don’t Want You To See!

    10 Saturday Jan 2009

    Posted by jschulmansr in 2008 Election, Barack Obama, communism, Conservative, Conservative Resistance, Currencies, currency, Currency and Currencies, dollar denominated, dollar denominated investments, economic, economic trends, economy, Electoral College, Finance, financial, Free Speech, Fundamental Analysis, futures, futures markets, id theft, inflation, Investing, investments, Latest News, market crash, Markets, Presidential Election, resistance, socialism, Today, u.s. constitution, U.S. Dollar, Uncategorized

    ≈ 2 Comments

    Tags

    2008 Election, Barack Dunham, Barack Hussein Obama, Barack Obama, Barry Dunham, Barry Soetoro, capitalism, Chicago Tribune, Columbia University, Currency and Currencies, D.c. press club, Electoral College, Electors, Finance, fraud, Free Speech, gold, Harvard Law School, hawaii, id theft, Indonesia, Indonesian Citizenship, Investing, investments, Joe Biden, John McCain, Latest News, legal documents, Markets, name change, natural born citizen, Oath of Allegiance of the President of the United State, Occidental College, Phillip Berg, Politics, poser, Presidential Election, Sarah Palin, socialism, Stocks, Today, treason, u.s. constitution, U.S. Dollar, Uncategorized, voter fraud, we the people foundation

    Why are the major news networks refusing to allow the Obama ad below? Yes, even Fox News has refused to sell airtime to run the ad- Why? The cases and lawsuits keep trickling their way to the Supreme Court, so his “eligibility” issues will continue even after he is inaugurated. Obama- “Please just show us the Birth Certificate as any patriotic citizen would do when asked.” Why are you hiring teams at last count (3) different legal teams to prevent your birth certificate from being produced? What is Obama hiding? Could it truly be he is not eligible to be the President of The United States? Fellow citizens is our Constitution no longer important or relevant? You decide- read below…- jschulmansr

    Eligibility Issue to Follow Obama into the Oval Office – World Net Daily

    By Bob Unruh
    © 2009 WorldNetDaily

    A legal challenge that alleges Barack Obama isn’t a “natural born” citizen and therefore constitutionally ineligible to be president of the United States will follow the Democrat into the Oval Office, with a U.S. Supreme Court conference on the dispute set after the Jan. 20 inauguration.

    The court’s website today announced that a fourth case on the issue will be reviewed by justices Jan. 23.

    The court previously heard two cases in conference – private meetings at which justices consider which cases to accept – and denied both Cort Wrotnowski and Leo Donofrio full hearings.

    The court now has a conference scheduled Friday on a case raised by attorney Philip Berg, with another conference on a matter related to the same Berg case on Jan. 16. Then today the court website revealed the case Gail Lightfoot et al v. Debra Bowen, California Secretary of State, will be heard in conference Jan. 23.

    The case initially appeared at the Supreme Court Dec. 12 but was rejected. It then was submitted to Chief Justice John Roberts, and today’s notice confirmed it was distributed for the Jan. 23 conference.

    Orly Taitz, the California attorney handling the case, said, “The timing of this decision by the chief justice of the Supreme Court, John Roberts, is absolutely remarkable. On January 7, one day before the January 8 vote by Congress and Senate whether to approve or object to the electoral vote of Barack Hussein Obama, aka Barry Soetoro, as president of the United States, Chief Justice Roberts is sending a message to them: ‘Hold on, not so fast, there is value in this case, read it.'”

    She noted the available procedure during congressional review for a member of Congress to object to the Electoral College results and demand documentation regarding Obama’s citizenship.

    Join the campaign to urge the Supreme Court to take the eligibility question seriously by FedExing the justices.

    “Each and every member of the U.S. Congress and Senate owes it to 320 million American citizens to do his due diligence and demand all necessary records,” she said.

    Members of Congress, she said, “can spend a day or two of their time defending this Constitution, reviewing necessary documents, in order to see if Barack Hussein Obama is a natural born citizen…

    “This is the message that the chief justice of the Supreme Court is sending to them. … (The) truth will come out, no matter how many millions Obama is spending to hide it,” she said.

    The plaintiffs in the case include a vice presidential candidate on the California election ballot, four electors and two others.

    She said her case was rejected by the California Supreme Court with a single-word decision, “Denied.” And she said her arguments rest on precedents from both the California Supreme Court, which years ago removed a candidate for president from the ballot because he was only 34, while the Constitution requires candidates to be 35, and the U.S. Supreme Court’s affirmation of that ruling.

    “We’ll see what happens,” she told WND. “This is not going to go away.”

    WND has reported extensively on questions raised about Obama’s eligibility, and the resulting lawsuits. The Taitz case is the fourth to earn a hearing at a Supreme Court conference.

    Twice before the justices have heard the questions, in cases brought by Wrotnowski and Donofrio, and twice before they’ve decided to ignore them.

    The result is that the questions remain unanswered and cloud the impending presidency of a man whose relatives have reported he was born in Kenya and who has decided, for whatever reason, not to release a bona fide copy of his original birth certificate in its complete form.

    The lawsuits allege Obama does not meet the “natural born citizen” clause of the U.S. Constitution, Article 2, Section 1, which reads, “No Person except a natural born Citizen, or a Citizen of the United States, at the time of the Adoption of this Constitution, shall be eligible to the Office of President.”

    Some allege his birth took place in Kenya and his mother was a minor at the time of his birth – too young to confer American citizenship. They report Obama’s father, Barack Obama Sr., was a Kenyan citizen subject to the jurisdiction of the United Kingdom at the time, and would have handed down British citizenship.

    Where’s the proof Barack Obama was born in the U.S. or that he fulfills the “natural-born American” clause in the Constitution? If you still want to see it, join more than 200,000 others and sign the petition demanding proof of eligibility now!

    There also are questions raised about Obama’s move to Indonesia when he was a child and his attendance at school there when only Indonesian citizens were allowed in that nation’s schools and his travel to Pakistan in the ’80s when such travel was forbidden to American citizens.

    On Friday the justices will consider Philip J. Berg’s Petition for Writ of Certiorari.

    “This is a historic occasion that will impact the office of the president of the United States as never before. No one has ever brought an action against a president-elect candidate challenging his eligibility to serve based on the ‘natural born’ citizen requirement provided in the United States Constitution, Article II Section 1,” said a statement on Berg’s ObamaCrimes.com website.

    Berg suggested if Obama “is allowed to be sworn in as president of the United States, there will be substantial and irrevocable harm to the stability of the United States of America and to its citizens.”

    “Because Barack Obama is not a ‘natural born’ citizen as required by the United States Constitution, then all of his actions as president would be null and void,” Berg said.

    Last month, WND reported similar concerns raised in a separate lawsuit filed in California.

    “Should Senator Obama be discovered, after he takes office, to be ineligible for the Office of President of the United States of America and, thereby, his election declared void,” argues a case brought on behalf of Ambassador Alan Keyes, also a presidential candidate. “Americans will suffer irreparable harm in that (a) usurper will be sitting as the President of the United States, and none of the treaties, laws, or executive orders signed by him will be valid or legal.”

    Because of the high stakes, WND earlier launched a letter campaign to contact Electoral College members and urge them to review the controversy.

    That followed a campaign that sent more than 60,000 letters by overnight delivery to the U.S. Supreme Court when one case contesting Obama’s eligibility for the Oval Office was pending.

    A separate petition, already signed by more than 200,000 also is ongoing asking authorities in the election to seek proof Obama was born in the U.S. or that he fulfills the “natural-born American” clause in the Constitution.

    WND senior reporter Jerome Corsi went to both Kenya and Hawaii prior to the election to investigate issues surrounding Obama’s birth. But his research and discoveries only raised more questions.

    The biggest question was why, if a Hawaii birth certificate exists as his campaign has stated, Obama hasn’t simply ordered it made available to settle the rumors.

    The governor’s office in Hawaii said there is a valid certificate but rejected requests for access and left ambiguous its origin: Does the certificate on file with the Department of Health indicate a Hawaii birth or was it generated after the Obama family registered a Kenyan birth in Hawaii?

    Join the campaign to urge the Supreme Court to take the eligibility question seriously by FedExing the justices.

    ===============================================
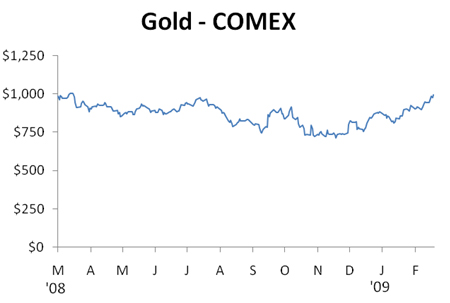
    Watch The Obama commercial they don’t want you to see- FOX, CNN, MSNBC questioning Barak’s Eligibility refuse ads

    Source: World Net Daily

    Barack Obama’s campaign officials and transition office repeatedly have rejected reporters’ requests for comment on questions raised over his lack of documentation regarding his birth and the resulting concerns over his eligibility to be president. Now a number of media organizations apparently don’t want questions raised either.

    WND columnist Janet Porter told WND she found that out when her organization, Faith2Action.org, tried to purchase airtime to publicize information about the eligibility concerns.

    She told WND that national networks that refused to sell her time for a 60-second commercial included CNBC, MSNBC, Headline News, CNN and Fox. Washington, D.C., outlets for the same organizations did the same.

    “With the date for congressional approval (of the Electoral College today), we wanted them to have access to the facts,” she told WND. “Congress is sworn to uphold the Constitution.”

    She said the donors who contributed the funding that was to be used for the ads were being contacted to find out whether they wanted to reach another direction in the media.

    The ad to be broadcast already is available on YouTube, and also is embedded here:

    “Heard rumors about Barack Obama’s citizenship? These are the facts,” the ad states.

    It cites a statement from the president-elect’s paternal grandmother that she was present at his birth in Kenya, his refusal to release his original birth certificate, his attendance at school in Indonesia “as Barry Soetoro when only Indonesia citizens were permitted to attend,” and Obama’s travel to Pakistan in 1981 “when it was illegal to enter as a U.S. citizen.”

    Join the campaign to urge the Supreme Court to take the eligibility question seriously by FedExing the justices.

    It concludes, “Our Constitution still matters.”

    “As requested, we backed up every sentence of this ad, and still it was rejected,” Porter said. “What does that say about freedom of speech when we not only cannot count on the media to cover the story, but we can’t even buy time to publicize what may be the biggest story of the century.”

    She raised several questions about the issue in her recent column.

    “What if an impostor from another country ran for the presidency and won?” she asks. “What if the media blocked any news of his birthplace and citizenship? What if the media censorship even blocked paid advertising which tried to expose it?

    “What if no one had the courage to challenge or verify it? What if he was inaugurated illegally? What if the military had to answer to a commander in chief who was illegitimate? What if every law he signed was invalid?”

    And, she wonders, “What if it all happened on our watch?”

    WND reported the U.S. Supreme Court has scheduled Friday a conference – a private meeting at which justices consider whether to take individual cases – on a lawsuit challenging Obama’s eligibility.

    Twice before the justices have heard the questions, and twice before they’ve decided to ignore them.

    The lingering questions continue to leave a cloud over the impending presidency of a man whose relatives have reported he was born in Kenya and who has decided, for whatever reason, not to release a bona fide copy of his original birth certificate in its complete form.

    Multiple lawsuits have been filed around the nation alleging Obama does not meet the “natural born citizen” clause of the U.S. Constitution, Article 2, Section 1, which reads, “No Person except a natural born Citizen, or a Citizen of the United States, at the time of the Adoption of this Constitution, shall be eligible to the Office of President.”

    Some of the legal challenges have alleged Obama was not born in Hawaii, as he insists, but in Kenya. The woman identified by Obama as his American mother, the suits contend, was too young at the time of his birth to confer American citizenship to her son under the law at the time – especially if it took place in a foreign country and the man identified as his father, Barack Obama Sr., was a Kenyan citizen.

    Where’s the proof Barack Obama was born in the U.S. or that he fulfills the “natural-born American” clause in the Constitution? If you still want to see it, join more than 200,000 others and sign the petition demanding proof of eligibility now!

    Other challenges also have focused on Obama’s citizenship through his father, a Kenyan subject to the jurisdiction of the United Kingdom at the time of his birth, thus making him a dual citizen. Such cases contend the framers of the Constitution excluded dual citizens from qualifying as natural born.

    Several details of Obama’s past have added twists to the question of his eligibility and citizenship, including his family’s move to Indonesia when he was a child, his travel to Pakistan in the ’80s when such travel was forbidden to American citizens and conflicting reports from Obama’s family about his place of birth.

    On Friday the justices will consider Philip J. Berg’s Petition for Writ of Certiorari.

    “This is a historic occasion that will impact the office of the president of the United States as never before. No one has ever brought an action against a president-elect candidate challenging his eligibility to serve based on the ‘natural born’ citizen requirement provided in the United States Constitution, Article II Section 1,” said a statement on Berg’s ObamaCrimes.com website.

    Berg suggested if Obama “is allowed to be sworn in as president of the United States, there will be substantial and irrevocable harm to the stability of the United States of America and to its citizens.”

    “Because Barack Obama is not a ‘natural born’ citizen as required by the United States Constitution, then all of his actions as president would be null and void,” Berg said.

    Last month, WND reported similar concerns raised in a lawsuit filed in California.

    “Should Senator Obama be discovered, after he takes office, to be ineligible for the Office of President of the United States of America and, thereby, his election declared void,” argues a case brought on behalf of Ambassador Alan Keyes, also a presidential candidate. “Americans will suffer irreparable harm in that (a) usurper will be sitting as the President of the United States, and none of the treaties, laws, or executive orders signed by him will be valid or legal.”

    Berg, who has another case on the issue pending on behalf of a retired military officer, earlier stated, “I am determined, on behalf of the 320 million citizens in the United States, to see that ‘our U.S. Constitution’ is followed. Specifically, in the case of Soetoro a/k/a Obama, does he meet the constitutional qualifications for president?

    “I am appalled that the mainstream media continue to ignore this issue as we are headed to a ‘constitutional crisis.’ There is nothing more important than our U.S. Constitution and it must be enforced,” he said.

    The Supreme Court also has another hearing on an issue raised by Berg for Jan. 16, and the Supreme Court just confirmed today yet another conference is scheduled Jan. 23 on a separate case, this one handled by California attorney Orly Taitz, challenging Obama’s eligibility.

    Because of the high stakes, WND earlier launched a letter campaign to contact Electoral College members and urge them to review the controversy.

    That followed a campaign that sent more than 60,000 letters by overnight delivery to the U.S. Supreme Court when one case contesting Obama’s eligibility for the Oval Office was pending.

    A separate petition, already signed by more than 200,000 also is ongoing asking authorities in the election to seek proof Obama was born in the U.S. or that he fulfills the “natural-born American” clause in the Constitution.

    WND senior reporter Jerome Corsi went to both Kenya and Hawaii prior to the election to investigate issues surrounding Obama’s birth. But his research and discoveries only raised more questions.

    The biggest question was why, if a Hawaii birth certificate exists as his campaign has stated, Obama hasn’t simply ordered it made available to settle the rumors

    The governor’s office in Hawaii said there is a valid certificate but rejected requests for access and left ambiguous its origin: Does the certificate on file with the Department of Health indicate a Hawaii birth or was it generated after the Obama family registered a Kenyan birth in Hawaii?

    ====================================================

    Join The Resistance

    This group is not intended to encourage animosity or malice toward President Obama or to bolster personal, ad hominem attacks so often used in political discourse.

    On the contrary, it is imperative that conservatives maintain a love for country and respect for our institutions as we defend this nation against the threats posed by the Obama Administration. Our disagreements with President Obama must be based on ideology and public policy, not personal attacks. From this firm foundation, we can mount a patriotic, resilient, conservative resistances to Obama’s agenda.

    Specifically we resist:
    • Wealth distribution and higher taxes
    • Government takeover of more and more of our lives
    • Open borders, amnesty and undermining of our uniquely American culture
    • Taxpayer-funded abortions and a radical anti-life agenda
    • The weakening of our military and retreat in the War on Terror
    • Socialized health care
    • The end of marriage and the exaltation of LGBT rights
    • International taxation and submitting our nation to the ideals of “global citizenship”
    • The Courts stacked with leftist judges who betray our Constitution
    • Weakening of the 2nd Amendment through unconstitutional gun laws that take away our firearms and our ability to defend our family, property, and ourselves

    Sign The Petition and Find Out More


    Share this:

    • Share on Reddit (Opens in new window) Reddit
    • Share on Facebook (Opens in new window) Facebook
    • Share on LinkedIn (Opens in new window) LinkedIn
    • More
    • Share on X (Opens in new window) X
    • Share on Pinterest (Opens in new window) Pinterest
    • Share on Tumblr (Opens in new window) Tumblr
    • Print (Opens in new window) Print
    • Email a link to a friend (Opens in new window) Email
    Like Loading...

    Has World War III Started?

    09 Friday Jan 2009

    Posted by jschulmansr in agricultural commodities, alternate energy, Austrian school, banking crisis, banks, Barack Obama, bear market, Bollinger Bands, bull market, capitalism, central banks, China, Comex, commodities, communism, Copper, Currencies, currency, Currency and Currencies, deflation, depression, diamonds, dollar denominated, dollar denominated investments, economic, economic trends, economy, Finance, financial, Forex, Fundamental Analysis, futures, futures markets, gold, gold miners, hard assets, heating oil, How To Invest, How To Make Money, India, inflation, Investing, investments, Keith Fitz-Gerald, Latest News, Make Money Investing, Marc Faber, market crash, Markets, mining companies, mining stocks, Moving Averages, natural gas, Nuclear Weapons, oil, palladium, Peter Schiff, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, protection, rare earth metals, recession, risk, run on banks, safety, Saudi Arabia, Sean Rakhimov, Siliver, silver, silver miners, small caps, socialism, sovereign, spot, spot price, stagflation, Stocks, Technical Analysis, timber, Today, U.S. Dollar, uranium, volatility, warrants, Water

    ≈ Comments Off on Has World War III Started?

    Tags

    agricultural commodities, alternate energy, Austrian school, banking crisis, banks, bear market, Bollinger Bands, bull market, capitalism, central banks, China, Comex, commodities, communism, Copper, Currencies, currency, deflation, depression, diamonds, dollar denominated, dollar denominated investments, economic, economic trends, economy, financial, Forex, futures, futures markets, gold, gold miners, hard assets, heating oil, India, inflation, investments, Keith Fitz-Gerald, Marc Faber, market crash, Markets, mining companies, Moving Averages, natural gas, oil, palladium, Peter Schiff, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, protection, rare earth metals, recession, risk, run on banks, safety, Saudi Arabia, Sean Rakhimov, silver, silver miners, socialism, sovereign, spot, spot price, stagflation, Technical Analysis, timber, U.S. Dollar, volatility, warrants, Water

    Has World War III already started? According to Marc Faber it has! Check out his interview. Next do you think the government can lose? According to this pundit not only will it lose it is going to lose big! Finally, for years now China has been coming to the rescue by buying Treasuries and US Debt, what will happen when they and other countries stop? Continuation of series from yesterday’s post. Just In! Peter Schiff Interviwed on Russian TV- Get Prepared!  adjust your portfolios and if you own Precious Metals hang on for the ride of your life!- Good Investing!- jschulmansr

    Marc Faber on the Economy, Gold, WWIII – Seeking alpha

    By: Tim Iacono of Iacono Research

    Another good interview with Dr. Marc Faber, this one over at Bloomberg where he’s been a regular for many years (recent appearances at the likes of CNBC are somewhat unusual as he tends to go against conventional wisdom, something that abounds at CNBC).
    IMAGE

    Click to play in a new window

    There’s lots of good stuff in this one – the outlook for the global economy, oil, gold, base metals, natural resource stocks, World War III having already started…

    On the subject of alternatives to the government solutions for the current problems, he was asked how he expected the populace to stand for the government doing nothing?

    That’s the problem of society. If people can not accept the downside to capitalism, then they should become socialists and then they have a planned economy. They should go to eastern Europe twenty years ago and to Russia and China for the last 70 years.

    How do you tell that to somebody in Detroit who’s losing his home today?


    Why is he losing his home? Because of government intervention. The government – the Federal Reserve – kept interest rates artificially low and created the biggest housing bubble, not just in the U.S. but worldwide. That is what I’d explain to the worker in Detroit.

    ============================================

    How the Federal Government will Lose in 2009 – Seeking Alpha

    By: Rob Viglione of The Freedom Factory

    Through a combination of incompetence and greed, the federal government has placed itself in a position of checkmate. There is no way to finance its budget deficits without devaluing the dollar or causing interest rates to rise. With $10.6 trillion in debt, $8.5 trillion in new money created or given away in 2008, and multiple years of trillion dollar deficits planned by Obama, government has no way to fund its extravagances without either printing a lot more money or borrowing unprecedented sums.

    This means that either Treasury bonds will crash, or the dollar will suffer significant devaluation relative to foreign exchange or precious metals, especially gold.

    TV Does Great Interview With Peter Schiff (Russian TV, That Is)

    =====================================================

    Remember Dare Something Worthy Today Too!


    Market forces are telling the world to shed unproductive assets and shrink capacity, yet central banks and governments around the world, in particular the U.S., are refusing to listen. Rather than allow markets to snap back to sustainable equilibrium from previously artificial highs, the federal government clings to the notion that forcibly shuffling resources, propping up asset prices, and diluting the money supply will magically save the day.

    There are consequences to everything. The consequences of shuffling resources (taxing productive ventures and doling out those resources to failing ones, i.e. bailouts) are stunted growth for good businesses and propagation of bad ones. Artificially propping up asset prices means that those who are generally less competent remain the custodians of society’s capital, and diluting the money supply inflates aways everyone’s wealth over time, particularly harming the poor and middle class.

    For decades the federal government has gotten away with this reshuffle and inflate game, but the pawns are drowning, the rooks helpless, and the knights ready to turn on the King. Perhaps this is overly dramatic. Clearly, I doubt the capability of the Federal Reserve, Congress, and Obama to “fix” the economy; rather, I strongly believe they are destroying it by forcing us all to drink this Keynesian Kool-Aid. However, whether or not the economy recovers amidst this historic central government action, there are two phenomena we can exploit to our advantage:

    • Short the US dollar
    • Short US Treasuries

    In “When will the great Treasury unwinding begin?” I show how government debt has been bid to unsustainable levels and will likely fall. The one concern I see stated all too often is that the Federal Reserve will keep buying Treasuries to artificially depress interest rates. This will, it is claimed, keep bond prices inflated. The one undeniable counter to this is that government must somehow fund its $1.2 trillion estimated 2009 deficit. It cannot do this by issuing and then buying the same bonds. It can only raise revenue by selling bonds to other parties, or by diluting the money supply by cranking up the printing presses. There are no other options. There you have it – we have the government in checkmate!

    The likely outcome is that they will try to do both. That is why I am heavily shorting both 30-Year Treasury bonds and the dollar. Both assets will likely lose as the government becomes increasingly desperate and the world’s biggest buyers realize there are better alternatives available. Make your bets now before it becomes treasonous to bet against Big Brother!

    Disclosure: Long UDN, short TLT, long GLD.

    ==============================================

    Five New Forces to Drive Gold Higher – Seeking Alpha

    By: James West of The Midas Letter

    Gold naysayers habitually point to the relatively weak performance of gold relative to the broader market over the last 5 years. Given the market today, that argument is increasingly wrong, and the naysayers are soon to either admit their mistake, or pretend that they were never naysayers at all. That’s because during the last 3 months, five major new forces have emerged to compound the previous strong drivers of the gold price up to now.

    These new forces are as follows:

    1. China has stopped buying U.S. debt.
      An interesting piece in the New York Times today signals that China, up until now the biggest buyer of U.S. Treasuries and bonds issued by Fannie and Freddie, is moving towards an end to that policy. China holds over US$1 trillion of such paper, and as interest rates collapse, there is less and less incentive for them to buy American.China has made several adjustments to programs that used to give banks and other financial institutions within the country incentive to buy U.S. assets, which means essentially that these same customers for assets will now be looking for Chinese products.The effect this will have on gold is two-fold. In the first place, reduced demand for U.S. debt will hamper Obama’s plans to keep printing money, because the one limiting factor that still seems to be respected in terms of how much paper can be printed, is the idea that there must be a counterparty to every issuance of T-Bills to warrant continued printing. Theoretically, less demand for T-Bills will force a rise in interest rates to attract investors. But that does not appear forthcoming, which will make the U.S. dollar weak relative to other currencies – especially gold.The second effect is that by eliminating incentives for Chinese banks to acquire U.S. denominated assets, investors there will divert more funds to holding gold as a hedge against their current U.S. dollar holdings, which will be diminishing in value.
    2. Future discoveries of gold deposits will diminish dramatically.
      The biggest source of gold ounce inventory for major gold producers is the discoveries made by the several thousand juniors who scour the earth in search of favorable geology. With the collapse in base metals prices, many of these juniors are under increasing pressure to consolidate and downsize, and many more will disappear altogether.That means less money going into gold exploration, and that means the number of new discoveries that can be acquired by majors is going to go down sharply in the coming years. In theory, as gold continues to outperform all other asset classes, there will be a rush back into junior gold exploration, but that won’t happen until gold is taken much higher and investment demand for it soars.
    3. Existing by-product gold production will fall sharply
      In copper, zinc and other base metals mines around the world, gold occurs in metallic deposits as a by-product of some other dominant mineral. In the United States, 15 percent of gold production is derived from mining copper, lead and zinc ores.With the collapse in prices for these metals, the by-product production of gold is most often insufficient to justify the continued operation of the mine profitably, and it is likely that a significant amount of this by-product gold production will cease along with the shutdown of these operations. The result will be less gold production from existing operations, contributing to the now even faster growing gap between supply and demand.
    4. Gold is becoming mainstream
      One of the biggest contributors to gold’s unpopularity as a main street investment is that it has been mercilessly derided and ridiculed by mainstream investment media and institutions. There is very little opportunity for an investment advisor to insinuate himself into a gold purchase transaction, since most anybody who wants to hold the metal can visit their local bullion exchange or mint and buy as much as they’d like. Because the massive investment institutions that dominate the investment advisory business can’t make a fee out of advising you to buy gold, they try to convince you to purchase other asset classes which their firm has either originated or is a participant in a syndication of investment banks selling such products.Thanks to the widespread coverage of the questionable integrity of these complex securities, and since many main street investors have been burned by their investment advisors (they feel), there is increasing main street advice being doled out to buy gold. One need only search Google news on any given day to discover that headlines critical of gold are now replaced with headlines singing its praises.
    5. Gold is the best performing asset class of the decade
      Now that the global financial meltdown has got up a head of steam, investors are hard pressed to find any investment that has performed well over the last ten years as consistently as gold. The chart below outlines this performance and appears here courtesy of James Turk’s GoldMoney.com.
    Gold Performance: 2001-2008 (click to enlarge)
    Gold Performance 2001 - 2008

    As you can see, any investment still returning an average of 10 – 17 percent is a winner, compared to everything else you can generate a chart for. As this intelligence permeates the none-too-quick popular investment imagination, and, combined with the other 4 factors, gold is going to be where the world’s next crop of millionaires is minted.

    ===========================================
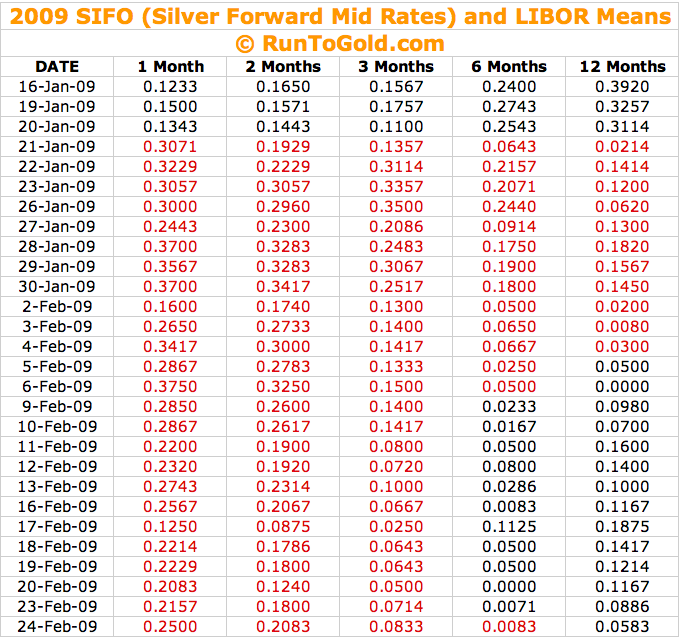
    Share this:

    • Share on Reddit (Opens in new window) Reddit
    • Share on Facebook (Opens in new window) Facebook
    • Share on LinkedIn (Opens in new window) LinkedIn
    • More
    • Share on X (Opens in new window) X
    • Share on Pinterest (Opens in new window) Pinterest
    • Share on Tumblr (Opens in new window) Tumblr
    • Print (Opens in new window) Print
    • Email a link to a friend (Opens in new window) Email
    Like Loading...

    The U.S. Dollar and Deficit-Gold Relationships

    08 Thursday Jan 2009

    Posted by jschulmansr in Bollinger Bands, capitalism, commodities, Copper, Currency and Currencies, deflation, Finance, Fundamental Analysis, gold, hard assets, How To Invest, How To Make Money, Investing, investments, Latest News, Make Money Investing, Markets, mining companies, mining stocks, Moving Averages, oil, platinum, precious metals, silver, small caps, Stocks, Technical Analysis, Today, U.S. Dollar, Uncategorized

    ≈ Comments Off on The U.S. Dollar and Deficit-Gold Relationships

    Tags

    agricultural commodities, alternate energy, Austrian school, banking crisis, banks, bear market, Bollinger Bands, bull market, capitalism, central banks, China, Comex, commodities, communism, Copper, Currencies, currency, deflation, depression, diamonds, dollar denominated, dollar denominated investments, economic, economic trends, economy, financial, Forex, futures, futures markets, gold, gold miners, hard assets, heating oil, India, inflation, investments, Keith Fitz-Gerald, market crash, Markets, mining companies, Moving Averages, natural gas, oil, palladium, Peter Schiff, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, protection, rare earth metals, recession, risk, run on banks, safety, Saudi Arabia, Sean Rakhimov, silver, silver miners, socialism, sovereign, spot, spot price, stagflation, Technical Analysis, timber, U.S. Dollar, volatility, warrants, Water

    My Note- Gold came roaring back today and being beaten down yesterday, currently Gold is up $15 at $856+ and holding above the $850 level. Today’s articles explore the relationship of the U.S. Dollar, the Deficit and National Debt; and their relationship to Gold prices. If you are not alarmed by the current deficit you should be! Now with Obama predicting a yearly deficit of over 1 Trillion dollars what does this mean for the Economy, the Dollar and the price of Gold? Read On and Find Out… Good Investing – jschulmansr

    Things We Don’t Talk About (But Should); National Debt and the $2 Trillion Deficits- Seeking Alpha

    By: Jonathan O’Shaughnessy of Emerginvest Blog & Emerginvest 

    It has been around for decades, and has been ignored by many for just as long. However, the US national debt stands to finally be thrown into the forefront of political discussion as the record for a single-year deficit looks to be beaten – by threefold.

    According to the government-run TreasuryDirect.gov, US national debt is the largest it has been in history at $10.6 trillion, or $10,638,425,746,293.80. This is at a time when the US is facing the worst economic crisis since the Great Depression, which requires record-shattering government spending to stabilize the faltering economy. In addition, global demand for US national debt is waning as countries world-wide are implementing their own financial stimulus packages. Yet economists are virtually unanimously advocating for radical government spending to stabilize the economy, which leaves future generations of Americans holding extremely large amounts of national debt.

    The problem for the average American is twofold: national debt doesn’t seemingly affect their daily lives and $10.6 trillion is a hard number to conceptualize. After a certain point, the human brain stops comprehending the magnitude of a given number, and simply categorizes it as “extremely large.” Subsequently, there is little public outrage or discussion when the US has run up a few hundred billion dollar deficit in years past. It doesn’t seem to affect their lives, no government projects are cut, and adding $0.2T onto $10.6T seems relatively insignificant.

    However, when viewed in another light, the enormity of the national debt is astonishing. According to the 2007 United States budget, and TreasuryDirect.gov, the interest alone on national debt is approximately $460 billion. It accounts for the second-highest expenditure on the US budget and if the US could forgo paying that interest on national debt for one year, the United States government could:

    1) Pay for the entire education budget of the United States six times over

    2) Reduce federal taxes by 33% for all Americans, or

    3) Write a check to every man, woman, and child in the United States for $1,500.

    Yet, that $460 billion in annual interest looks to grow substantially with looming deficits in the years to come.

    A New York Times article entitled “Obama Warns of Prospect for Trillion-Dollar Deficits,” stated: “President-elect Barack Obama on Tuesday braced Americans for the unparalleled prospect of ‘trillion-dollar deficits for years to come.’” President-elect Obama did not give details about the size of the deficit, but projections place the proposed deficit at close to $1.2 trillion for 2009, shattering the record from President Bush last year at $455B.

    That is not counting the proposed $800B 2-year stimulus package which could easily raise the deficit into the $1.7 trillion range – bringing the national debt to roughly $12.3 trillion by the end of 2009. Assuming deficits run at approximately $1 trillion per year for the next two years, which may or may not be conservative, the US could see its national debt as high as $15 trillion in three years.

    Subsequently, Obama added emphasis on tighter government regulation, quoted in the NYTimes article as saying: “’ We’re not going to be able to expect the American people to support this critical effort unless we take extraordinary steps to ensure that the investments are made wisely and managed well.’” In correlation, he created a new position, chief performance officer, in charge of eradicating government inefficiencies.

    This comes at a time however, when global demand for US debt is falling sharply. A prime example is China, one of the largest creditors to the US, which has heavily curtailed its purchases of US debt in light of the recent financial crisis. Another NYTimes article entitled: “China Losing Taste for Debt from U.S.,” states that: “China’s foreign reserves will increase by $177 billion this year — a large number, but down sharply from an estimated $415 billion last year.” The Chinese government is dealing with their own economic woes – a stock market which has shed two thirds of its value in the last year – and is attempting to implement their own economic stimulus package. Furthermore, the sharp outflow of foreign direct investment in China has further complicated the issue. The situation is similar across the world, as the Emerginvest heat map shows the damage from the past quarter (click to enlarge):

    The lack of global demand for US national debt could put severe pressure on US interest rates in the years to come if demand continues to shrink drastically. However, there is a political buffer, as the article stated that: “China’s leadership is likely to avoid any complete halt to purchases of Treasuries for fear of appearing to be torpedoing American chances for an economic recovery at a vulnerable time, said Paul Tang, the chief economist at the Bank of East Asia. ‘This is a political decision,’ he said. ‘This is not purely an investment decision.’”

    Yet even in the face of significant strain on government debt and sagging global demand, economists are virtually unanimous in calling for exorbitant amounts of government spending to stabilize the economy. Yet another NYTimes article entitled: “A Crisis Trumps Constraint,” states that: “To a degree that would have been unimaginable two years ago, economists and politicians from across the political spectrum have put aside calls for fiscal restraint and decided that Congress should spend whatever it takes to rescue the economy,” in addition to: “’It pains me to say that because I am a fiscal conservative who dislikes budget deficits and increases in government spending,’ Mr. Feldstein told the lawmakers. But he said, ‘Reviving the economy requires major fiscal stimulus from tax cuts and increased government spending.’”

    Therefore, it looks as if the U.S. is inexorably tied to unparalleled government spending in the short term, nearly guaranteeing a national debt of over $14 trillion within a few years. The Obama administration has hinted at overhauling Medicare and Social Security as ways of dampening the gargantuan deficits, but the method, and certainly the net effect of such an undertaking remains ambiguous until the budget is revealed. It seems as if, in the interest of short term self-preservation, future generations of Americans will be inevitably saddled with incomparable amounts of national debt which will heavily shape future American fiscal policy for decades.

    Disclosure: Emerginvest is an international finance portal, providing analysis and data on 120+ world markets to help individuals find investments from around the world. Emerginvest provides impartial information about world stock markets, and does not have any holdings in foreign equities.

    ===============================================

    Government Panic Could Herald Dollar Panic – Seeking Alpha

    Source: John Browne of Euro Pacific Capital

    One of the few things more troubling for an economy than government intervention is government intervention driven by panic. Time and again, history has shown that when governments rush to engineer solutions to pressing problems, unintended difficulties arise.

    In the current crisis, there is growing evidence that Washington is in a state of increasing panic. Despite its massive cash injections, market manipulations and ‘rescue’ plans, the recession is clearly deepening and spreading. With little to show thus far, politicians don’t know if they should redouble past efforts, break ground on new initiatives, or both. However all agree, unfortunately, that the consequences of doing too little far outweigh the consequences of doing too much.

    Although there are many parallels between the current crisis and the Crash of 1929, one key difference is the global profile of the U.S. dollar. In 1929, the dollar was on the rise, and would soon eclipse the British Pound Sterling as the world’s ‘reserve’ currency. Furthermore, the American economy was fundamentally so strong that in 1934 America was the only major nation able to maintain a currency tied to gold.

    Ever since, the U.S. dollar’s privileged ‘reserve’ status has been a principal factor in America’s continued prosperity. The dollar’s unassailable position has enabled successive American governments to disguise the vast depletion of America’s wealth and to successfully increase U.S. Treasury debt to where the published debt now accounts for some 100 percent of GDP. The total of U.S. government debt, including IOU’s and unfunded programs, now stands at a staggering $50 trillion, or five times GDP! If the dollar were just another currency, this never would have been possible.

    In today’s crisis however, the dollar is likely making its last star turn as the leading man in the global financial drama. Other stronger, less burdened currencies are waiting in the wings for the old gent to take his final bows.

    The dollar’s demise is being catalyzed by the neglect of the Federal government. Instead of enacting policies that would restructure the U.S. economy, and restore productive, non-inflationary wealth creation, Congress is simply financing the old crumbling edifice.

    Faced with the growing realization that America is not doing the work necessary to right its economic ship, it will not be long before America’s primary creditors begin to seriously question the nation’s ability to service, let alone repay, its debts.

    There is now the prospect (inconceivable until recently), that America could lose its prestigious ‘triple-A’ credit rating. In today’s risk adverse market, this could cost the Treasury one percent in interest on long bonds. Each additional percentage point of interest would cost America some $10 billion a year on each trillion dollars of new debt, or some $300 billion over the life of a 30-year bond.

    Many of the foreign governments who hold huge amounts of U.S. dollar Treasury debt, such as China and Japan, have announced plans to spend money on their own ailing economies. Should these foreign central banks divert to domestic initiatives some of the funds used to buy U.S. Treasuries, serious upward pressure on U.S. interest rates will result. Should they actually sell parts or all of their holdings they will likely put serious downward pressure on the U.S. dollar. Last week, a Chinese official claimed the U.S. dollar should be phased out as the world’s ‘reserve’ currency.

    In the short term, as dollar ‘carry-trades’ continue to be unwound and questions of political will and falling interest rates haunt the Euro and some other currencies, the U.S. dollar may be the recipient of some upward appreciation. But with the American government appearing increasingly to be in panic mode, a run on the U.S. dollar could develop rapidly into cascading devaluation. Even if no such panic run materializes the long-term outlook for the U.S. dollar is one of high risk and low return. This beckons major upward pressure on precious metals.

    ========================================

    What is Going On With Gold? – Seeking Alpha

    Source: The Pragmatic Capitalist

    Gold (ETF:GLD) is one of the most fascinating and talked about assets on the planet. There are more conspiracy theories and story lines behind gold than just about anything on earth. Heck, the followers of the asset even have their own club: the goldbugs. You can’t go a day without seeing a commercial about gold. If you google “buy gold” you get almost as many results as if you search “buy real estate” (15.4MM vs 16MM).

    But gold has been acting funny lately. The conspiracy theories have been running even crazier than usual (from government conspiracy to backwardation) and the goldbugs are angry. As the world economy deteriorates and the U.S. prints money like it’s going out of style, gold has not appreciated. If you had told me in December of 2007 that the global stock market would fall 40% in 2008 I would have told you to buy gold and nothing else because of its safehaven characteristics. But a funny thing happened on the way to the demise of the global economy: Gold fell.

    After rallying into the second quarter of 2008, gold went on a gut wrenching 6 month decline of over 30% – all in the midst of one of the greatest financial collapses ever. It was, if nothing else, quite a paradox. Even crazier, the US dollar stabilized and then rallied into the end of 2008. Why did this happen? How could gold fall in such an environment?

    Gold remains an anti-dollar investment. It’s as simple as that. When you buy gold you’re essentially buying a hard asset currency with the hope that one day it will become the world’s choice of currency again. If the dollar (UUP) weakens or one day fails the likelihood of a gold based currency increases. In essence, buying gold is a way of betting against the greenback and U.S. economic dominance. You can argue the extent of my argument, but you can’t really argue with the inverse correlation in the two assets:

    Click to enlarge

    The correlation is clear. If you’re betting on a rise in gold you’re betting on a falling dollar. I’ve been banking on a higher dollar for over 6 months for one reason: it’s the best currency in a bad lot. Jim Cramer should change his area of expertise to currencies, because while there isn’t always a bull market in stocks and commodities, there is always a bull market somewhere in the currency market. Trades are paired in Forex and unfortunately, it’s hard at this time to make an argument in favor of other currencies over the greenback. And as long as the greenback remains strong it’s unlikely that gold will make any sustainable run.
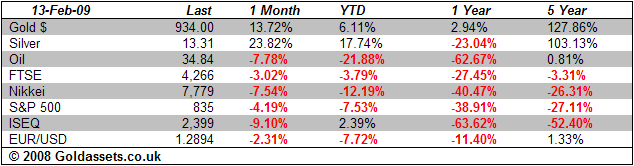
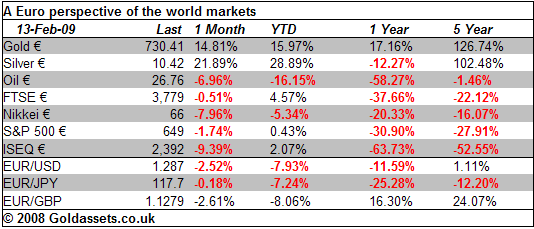
    So why is the dollar the best of the worst? It’s quite simple in my mind. Two major currencies on the planet now effectively bear zero interest: the dollar and the Yen. Of the two, the U.S. is the far superior economy. In essence, neither country can really devalue their currency all that much more unless they decide to print money to the point of insanity and although I believe the U.S. is printing wildly I am not incredibly alarmed as of yet simply because the destructive deflationary forces at work are so much greater than the inflationary response by the Fed. Inflation is certain to rear its ugly head in the coming years, but I suspect it will be relatively mild as the economic rebound is slow and the overall monetary destruction of this deflationary phase proves to be incredible.

    So, getting back to the greenback – the U.S. was first to enter a recession and it now looks like the world is catching pneumonia from our cold. Unfortunately Europe and Asia still have relatively high interest rates (read: room for currency devaluation) and simply don’t carry the same status as the U.S. – we are the reserve currency and the only true AAA nation. Yes, you can certainly make the argument that the U.S. is no longer a AAA rated country, but if we’re AA then what does that make Japan (the world’s second largest economy) or Germany? Much worse, in my opinion.

    So what we’re seeing is essentially a flight to quality in a time of financial distress? Yes, that’s right, the U.S. dollar is a higher quality asset right now than just about any currency on the planet. And if you’re a U.S. citizen you should be thanking your lucky stars it’s THE reserve currency because this crisis would likely be even worse if that wasn’t the case.

    So, before you go placing bets on gold it might be better to research the greenback first.

    ==================================================

    Not Time To Exit Commodity Positions – Seeking Alpha

    By: J.D. Steinhilber of Agile Investing

    Diversified commodities have suffered approximately the same one-year decline as stocks, but the descent has been more violent since broad commodity indexes peaked in the middle of 2008, whereas most stock indexes peaked in October 2007. Just as it is not the time to abandon stock market commitments, this is certainly not the time to exit commodity positions in the context of a diversified multi-asset portfolio.

    Cyclical commodities are not a valuable hedge to a stock portfolio in a deflationary bust and a liquidity crisis such as we have seen, but those conditions are not likely to persist over any investment horizon measured in years rather than months. Massive government reflation and stimulus efforts will support hard assets in 2009. Infrastructure spending is bullish for commodity prices, and tighter credit conditions, along with lower prices, puts pressure on the supply of commodities as suppliers curtail production.

    Gold finished the year on a very strong note and managed to produce another year of positive returns in 2008. Gold has the most attractive three and five year annualized returns of all the asset classes we track. Gold will continue to be whip-sawed by the volatility in the currency markets.

    We hold Gold (GLD) in our portfolios as an insurance policy against financial crisis and paper currency devaluation. The opportunity cost of holding gold, which produces no dividend or interest income, is now very low given that the Federal Reserve has cut the official U.S. overnight lending rate to zero to 0.25%, and has stated that “weak economic conditions are likely to warrant exceptionally low levels of the federal funds rate for some time.”

    [click to enlarge]


    ===================================================

    How Will Obama’s “Trillion Dollar Deficits” Affect the Markets? – Seeking Alpha

    By: Simit Patel of Informed Trades.com

    The New York Times has an article this week reporting on US President-elect Barack Obama’s warning that there will be ‘trillion-dollar deficits for years to come.” What does that mean for the markets?

    The first line of recourse will be the issuance of Treasury bonds; in other words, the US government will look to borrow money, offering to pay it back with interest. The key question, though, is to what extent buyers of Treasuries will be easily found. As we have discussed previously, the very low yield on bonds coupled with the fact that the economic pains are being felt all around the world suggest one of two possibilities: bond rates will have to go up or the Federal Reserve will have to “monetize the debt” — meaning it will simply have to print more money.

    I have stated and continue to believe that the result of increased deficit spending, due largely to government bailouts, in this environment will be debt monetization (even if there is a rate hike, that will only increase the future debt, and thus will only delay and exacerbate debt monetization). I believe this will prove to be inflationary, that it will devalue the US dollar, and that this is the real way the bailouts will be paid for; not via a direct tax, but rather a tax through inflation. Economist Mike Shedlock, however, offers a counter viewpoint:

    The Fed at some point will resort to out and out monetization, and that will have the inflationists screaming at the top of their lungs. However, banks will still be reluctant to lend, and consumers and businesses will be reluctant to borrow. In addition, I expect the velocity of money printed to be close to zero and for the savings rate to rise. In aggregate, these are not hyperinflationary things. Heck, they are not even inflationary things.

    Admittedly, I am one of those inflationists who will be screaming at the top of my lungs.

    There are two reasons I believe debt monetization will be inflationary:

    1. I disagree with the notion that banks won’t lend and consumers won’t borrow. As I recently noted, we are seeing a declining TED spread as well as an increase in many money supply metrics (M1, M2, MZM). And even in this environment, we have seen companies like Verizon be able to secure a massive $17 billion loan.
    2. Even if lending is reduced due to the economic climate, debt monetization increases the likelihood that foreigners will not only stop buying Treasuries, but that they will sell the ones they have, and will dump US dollar holdings out of a concern of dollar devaluation by the part of the Federal Reserve. This suggests there will be a “run on the currency,” similar to what was seen in Argentina. See our previous article on the similiarities between the US economic crisis and the Argentinian crisis of 2001 for more on this subject.

    How to Trade This Scenario

    Timing is the key issue for trading this; we are currently seeing a rally in the market, though I expect that at some point in the second half of 2009 we will see the concerns about the Treasury market begin to manifest. As a trend-following trader I look for momentum that corresponds to my fundamental viewpoint, with the exception of precious metals, which I treat as buy and hold type investments.

    With that in mind, here are the conclusions I am making based on the trillion dollar deficit scenario:

    1. US dollar will fall in value. For stock market traders, UDN is an ETF to watch.
    2. Dollar hedges like gold and silver will rise. GLD and SLV are corresponding ETFs.
    3. Both monetization of debt as well as a hike in interest rates will send bond prices falling, as a rate hike devalues all bonds previously issued at a lower rate while monetization of debt introduces inflation concerns and the possiblity of the bond being paid back with a currency that is worth less.
    4. A rate hike, which I think is increasingly unlikely given the Fed’s behavior though still possible, will be bearish for US stocks. DOG and SH are inverse ETFs worth considering in such a scenario.

    Disclosure: Long gold and silver; currently short US dollar against Australian dollar.

    ==============================================

    My Note: Whether as “Portfolio Insurance”, or as a Speculative Investment, I think now is the time to buy and Invest in  Gold and Precious Metals in any form. I am calling for $1000 to $1250 Gold later this year and even higher if the Middle East Situation disintergrates and gets worse. Other factors are mentioned in detail above, don’t kick yourself later, buy Precious Metals and Miners at these ridiculously low levels NOW!

    My- Disclosure: I am long Physical Precious Metals, Etf’s, and Mining/Producer Stocks. I.e. my money is where my mouth is! Remember to do your own Due Diligence and read all Prospectus’s before making any investment. -jschulmansr

    Share this:

    • Share on Reddit (Opens in new window) Reddit
    • Share on Facebook (Opens in new window) Facebook
    • Share on LinkedIn (Opens in new window) LinkedIn
    • More
    • Share on X (Opens in new window) X
    • Share on Pinterest (Opens in new window) Pinterest
    • Share on Tumblr (Opens in new window) Tumblr
    • Print (Opens in new window) Print
    • Email a link to a friend (Opens in new window) Email
    Like Loading...

    Gold-History Repeating Itself?

    06 Tuesday Jan 2009

    Posted by jschulmansr in Bollinger Bands, capitalism, commodities, Copper, Currency and Currencies, Finance, Fundamental Analysis, gold, hard assets, How To Invest, How To Make Money, inflation, Investing, investments, Jschulmansr, Latest News, Make Money Investing, Markets, mining stocks, Moving Averages, oil, precious metals, silver, small caps, Stocks, Technical Analysis, Today, U.S. Dollar, Uncategorized

    ≈ Comments Off on Gold-History Repeating Itself?

    Tags

    agricultural commodities, alternate energy, Austrian school, banking crisis, banks, bear market, Bollinger Bands, bull market, capitalism, central banks, China, Comex, commodities, communism, Copper, Currencies, currency, deflation, depression, diamonds, dollar denominated, dollar denominated investments, economic, economic trends, economy, financial, Forex, futures, futures markets, gold, gold miners, hard assets, heating oil, India, inflation, investments, Keith Fitz-Gerald, market crash, Markets, mining companies, Moving Averages, natural gas, oil, palladium, Peter Schiff, physical gold, platinum, platinum miners, precious metals, price, price manipulation, prices, producers, production, protection, rare earth metals, recession, risk, run on banks, safety, Saudi Arabia, silver, silver miners, socialism, sovereign, spot, spot price, stagflation, Technical Analysis, timber, U.S. Dollar, volatility, warrants, Water

    Today’s action: Gold opened down by a few dollars and now has reversed itself and is cusrrently up $7-10 oz. Based off of chart formations it would appear that  Gold is breaking out to the upside and getting ready to challenge the $900 level, If it can break that then we are set up for a test of the $950-$975 level. If it fails here, a pullback to the $800 level (support base) will probably occur. Today’s articles include one about a new 2yr gold price cycle that appears to be forming. Next some questions answered about the markets for 2009. Finally a special report from Gold World about Gold Backed Banking. Enjoy and good investing! – jschulmansr

    Gold’s 2-year cycle – MineWeb

    A Mineweb reader has noticed a recent two-year cycle for gold price behaviour which, if it continues will likely give some guidance to price movements this year and next.

    By: Joseph Cafariello

    EDMONTON, CANADA –

    There seems to be a two-year cycle in the gold price which has been repeating itself since about 2004.  The even years follow one pattern, while the odd years follow another pattern.  The even years tend to reach exaggerated extremes to the upside and to the downside on a percentage basis, while the odd years tend to be a little calmer with less volatility.

    For example, 2008 went very much like 2006, with exaggerated highs reached in the spring of each year, and a late start to the traditional autumn-winter-spring upswing, which began around October/November of 06 and 08.  On the odd-number side, 2007 went much like 2005, with moderate highs reached in May of each year, and an early start to the traditional autumn-winter-spring upswing, which began around August/September of 05 and 07.

    If this is indeed a reliable cycle, we can expect 2009 to be much like 2005 and 2007 all throughout the year.  The first half of 2009 should see gold follow the same pattern as the first halves of 2005 and 2007.  In the springs of 05 and 07, gold kept hitting its head against the previous year’s high all throughout the spring.  More than once during the spring of 2007, gold topped out at about $690, coming to within about 5% of the 2006 high of $735.  Similarly, the spring of 09 should see gold hitting its head against 2008’s high of $1,035, coming to within 5% of it, or up to about $985.  That will be the high for the first half of 2009 at around the beginning of May, though this will not be the high for 2009 as a whole.

    Given the odd-number year pattern, we might also expect the back half of 2009 to be much like the back halves of 2005 and 2007.  In both 2005 and 2007, the summertime pull-backs were modest, and the autumn-winter-spring upswings started early, at around August/September of 05 and 07.  The latter half of 2009, then, should see a modest summer-time pull-back of about 5% to 7% of its spring 09 high, taking gold down from $985 in May 09 to about $925 by August 09.  However, the low for 2009 will still be the upcoming January low of $800, which is now only about a week or two away.  The lows of January 2005 and January 2007 were also “the” or “close to the” annual lows for those years.  So the low of 2009 will be at around $800 in January.

    The high for 2009 will come in December.  The traditional autumn-winter-spring upswing in 2009-10 will be much as it was in 2005-06 and 2007-08, with an early start.  The year-end run for 09 will begin around August or the beginning of September, jumping from about $925 in Aug/Sep 09 and rising steadily until the end of December 09.  The annual highs for 2005 and 2007 were hit in or near December of each year, and each high was about 20% higher than the average of their first halves.  Thus, the annual high of 2009 will be hit in or near December, and will be 20% higher than the average of its first half, putting the 2009 high at about $1,150 in December.

    The traditional autumn-winter-spring upswing, however, will certainly not end in 2009, but will spill over into the spring of 2010 much as it did in the springs of 2006 and 2008.  The high in the spring of 2008 was about 40% higher than high in the spring of 2006.  Hence, the high in the spring of 2010 will be about 40% higher than 2008’s high of $1,035, putting gold at about $1,450 in the spring of 2010.  Then, the summertime pull back of 2010 will be just as stark as were the summertime pullbacks of 2006 and 2008.

    And so the two-year cycle will continue, where even-number years follow a pattern of extremes, while the odd-number years are calmer, but with a nice upward kick at the end.  This two-year cycle with even-number years on the extreme side and odd-number years on the moderate side will continue until the commodity boom is over (say around the year 2030, when the populations of China and India finally achieve a 75% middle-class), and until the US dollar recovers at around the same year (2030), when the rest of the world will be looking to the US as a nice place to shop given its then-to-be dirt-cheap dollar.

    The above comment was contributed by Mineweb reader Joseph Cafariello who describes himself as “A raving gold bug and proud of it”

    ==========================================

    2009 Market Q&A: Four Questions Answered – Seeking Alpha

    Source: Eric Roseman of The Sovereign Society

    By Eric Roseman

    Over the last several weeks I’ve received numerous questions from Sovereign Society subscribers, including individuals who frequent our daily blog.

    As we start 2009, I thought this would be an ideal forum to collect some of these important questions and attempt to give you my best conclusions. I can’t reprint all of these inquiries; but I’ve compiled several excellent questions from our members.

    Overall, I don’t like forecasting. I generally believe it’s a total waste of time and most consensus estimates ahead of 2008 ended in the basement with the majority of analysts dead wrong about the economy, the market and just about everything else.

    I have to admit that I never expected the markets to crash, the banking system to go bust or the dollar to skyrocket in the midst of the worst financial crisis in 75 years. To be fair, I think most pros failed to make accurate predictions.

    Question: I’m a retired investor living on income. Prior to the big rally in Treasury bonds, I held most of my savings in short-term Treasury’s and bank term deposits. But with short-term rates under 1% and government bonds yielding a pittance, I’m nervous. What should I do to supplement my income?

    Comment: This is perhaps the most challenging environment for retirees in more than a generation. With money-market funds yielding almost nothing, Treasury bonds yielding around 2% and bank CDs paying under 1%, retirees must supplement their income.

    My advice is to take a small portion of your savings, say 20%, and scatter that sum across a dozen or more investment grade corporate bonds. I emphasize “investment grade” and not junk debt. Investment grade debt includes anything rated BBB or better in my book and, to make it easier, I would stick to issues rated A- or higher.

    The Dow Jones Corporate Bond Index now yields 6.90% – down from its post-crash high yield of 8.87% in early $100 bill imageOctober. Still, investors can tap into non-financial bonds like IBM, Johnson & Johnson (JNJ), Wal-Mart (WMT) and Kraft Foods (KFT) – all paying 5.5% or more. Or, look at corporate bonds issued by America’s largest banks, including JPMorgan Chase (JPM), Goldman Sachs (GS), Wells Fargo (WFC) and US Bancorp (USB). These banks won’t default.

    A good strategy to keep things simple is to buy a laddered portfolio of corporate bonds ranging from two years all the way to seven years. This should at least give your nest egg a boost and if you feel comfortable with this formula, then increase your position to say 35% of your portfolio. But remember, don’t go whole-hog; at some point over the next 12 months, perhaps later, Treasury bond prices will get smashed and long-term rates will head higher as the government expands credit to the moon. Keep your powder dry.

    Question: Do you think we’ll avoid another Great Depression? Despite all the money thrown at the markets since late 2007 we’re still in the midst of a severe credit contraction and the global economy has literally fallen off a cliff since October.

    Comment: I think we’ll avoid another Great Depression but only because government will nationalize or partially nationalize key industries. Without government intervention, the free market would have resulted in massive failures and a total collapse of the banking system and the broader global economy. There’s no doubt in my mind that the government made a big mistake not rescuing Lehman Brothers last September. Once you’re bailing out major banks, then do it right. But in all honesty, we don’t know what transpires behind the Fed’s walls or the Treasury’s. There’s some crazy buddy system in progress with special interests influencing government policy. The government doesn’t give a damn about you or me. What they care about is protecting their interests. That’s why we must protect our assets and, in the end, I believe gold will triumph above all paper money, especially against the dollar.

    I don’t advocate government intervention; but these are not normal times and the consequences might have resulted in the death of capitalism and perhaps the emergence of a new social order, similar to what occurred in post-Weimar Germany in the 1920s. Harsh economic times usually result in a new socio-economic regime. If the Fed and Treasury fail to rescue the credit system, then we might face similar consequences. The world as we know it will come to an end.

    It’s hard to know exactly what goes on behind the Federal Reserve’s closed doors and at the Treasury’s. Thus far, government efforts have been bold since the October crash, including major central banks worldwide. Major credit indicators have indeed improved since November but the housing market – the crux of the crisis – is still in a freefall. Housing must stabilize before this severe recession ends.

    In my eyes, it seems that bailouts and backstops are not addressing the real problem; most TARP money is ending up in bank coffers again and, in most cases, these institutions aren’t lending. The core of this credit crisis lies with the consumer and with housing. If you’re going to fork out several trillion dollars to fix or remedy this crisis then give the money to the consumer – not the banks. The consumer is in a severe bear market with personal assets plummeting over the last 18 months, including real estate, stocks, most bonds and now, possibly his or her job might be next on the chopping block.

    Give consumer households $50,000 or more and allow them to clean-up their busted balance sheets, keep their homes (service mortgages) and pay off installment debt. You might not agree with me and, in all fairness, it’s against the tenets of the Sovereign Individual; but what good will all this money do if it’s basically squandered by government and ending up in the pockets of reckless bankers again? I have serious doubts about how the government is dealing with this crisis and I don’t think Obama’s spending package will help much at all despite perhaps growing the economy for a few quarters.

    Question: What about the banks? With governments now standing behind their biggest financial institutions, is the worst over?

    Comment: The global banking system, for all intents and purposes, is effectively bust or bankrupt. This is especially the case in the United States, Europe and, to a lesser extent, in Japan. More than a dozen emerging market banks are totally bust, including Iceland, the Baltics, Hungary, Romania, Bolivia, Ukraine, Ecuador, Argentina, etc. Not a pretty picture.

    I think we’re more than 75% through the worst at this juncture. Governments now stand behind the largest banks in each country and, in some cases, even guarantee entire deposits until 2010 (e.g. European Union). I wouldn’t worry about the largest banks failing at this point. The worst is now behind us.

    Question: I know you’re a big gold bug, but isn’t the euro a strong currency and do you think it’s a better hedge against the dollar than gold? Is it too late to purchase gold coins and, if not, where would you suggest I buy coins?

    Comment: I have absolutely zero faith in the U.S. dollar and other currencies, including the euro or yen. In the end, all currencies will decline vis-à-vis gold and, in fact, since 2005 the world’s currencies have been losing their relative value to gold bullion. Despite big moves by the yen and euro over the last several years, they pale against gold.

    Increasingly, the average man in the street will realize that paper money is not protecting his purchasing power and will revolt against fiat money. At The Sovereign Society, we’ve driven home this message since our first year of publication in 1997. Gold is the only asset in this world that isn’t someone else’s liability; with U.S. interest rates effectively at 0%, paper money now competes with gold, which also pays 0% interest. In a zero percent world, which asset would you rather own? I think the answer is obvious.

    The government’s enormous spending plans to rescue the financial system and bailout almost every ailing industry Gold Coin Imageassures dollar destruction because the Fed is now on course to print money like never before to quash deflation. We all better hope and prey that the Fed can drain excess bank liquidity very quickly when this credit crisis ends. If not, we’ll have some serious inflation – much worse than what we saw prior to July 2008.

    I think every investor should hold at least 10% of his assets in physical gold. This means coins, wafers or bars. Getting gold coins today is difficult because the U.S. Mint has stopped selling Eagles since last summer while other dealers are complaining about tight supplies amid booming investor demand. I suggest KITCO or First Federal Coin Corporation.

    Also, I would not hold or store all of my physical gold at my home domicile. I strongly suggest parking some of your gold in Switzerland, too. Remember, you must report assets outside of the United States and Canada.

    I’m convinced we’ll see some sort of government confiscation of gold again just like we did in the 1930s. Back then, FDR did allow Americans to hold a maximum of 100 ounces. I’m not so sure the next confiscation will be so generous.

    I hope you found this helpful.

    ===============================================

    2009 Gold Outlook – Gold World

    How To Invest in Gold in 2009

    By Luke Burgess

    The investment markets are yielding to the fact that the global economy will remain weak for the better part of 2009.

    As a result, investors will continue to seek safe havens.

    Under normal conditions, these safe haven investments would include land and real estate. These assets have intrinsic value; or in other words, their value will never fall to zero. But with falling prices, investing in real estate is out of the question for most people right now. And there’s little doubt that investors will look elsewhere for safety against financial crisis.

    The best safe haven asset in the world right now is still gold because it is never considered to be a liability.

    And we believe that safe haven investment demand will drive gold prices during 2009. With this in mind, we would like to present a broad overview of Gold World‘s 2009 gold outlook. But before we get into that, let’s review what happened to gold prices in 2008.

    Gold Was One of the Best Investments of 2008

    In March 2008, gold prices hit a record high of $1,033 an ounce as the gold bull market entered its seventh year of life. This was followed by a normal 18% correction, which drove gold prices back down to $850 an ounce.

    Gold prices subsequently rebounded and were once again closing in on the $1,000 level in mid-July. At the same time, however, the fundamental and psychological effects of the slowing housing and credit markets were just beginning to devalue significantly the investment markets across the board.

    As a result, many long gold positions had to be sold in order to cover losses from investments in other markets. Over the next several months, this forced selling pressure pushed gold prices down.

    Gold prices were also held down during the second half of 2008 as the U.S. dollar enjoyed a +20% rally. Foreign governments, institutions, and banks began buying the U.S. dollar, which despite a legion of problems continues to be the world’s most important reserve currency, as a hedge against domestic economic turmoil.

    20090105_2009_gold_outlook.png

    These factors contributed to a significant drop in the price of gold, which officially bottomed out for the year at an intraday low of $683 an ounce in October 2008.

    Gold prices have subsequently bounced off of the $700 level as major selling has dried up, and fresh buying has come into the market.

    Despite three 20% corrections and serious deflation in the market, gold exited 2008 with a positive 5.4% gain for the year. Although subtle, this gain outperformed every major equity index and commodity in the world. Here are just a few examples…

    Index/Commodity
    Percent Change During 2008
    Dow Jones
    -34%
    NASDAQ
    -41%
    S&P 500
    -39%
    TSX -35%
    TSX Venture -74%
    Oil
    -55%
    Silver
    -23%
    Copper
    -54%
    Gold
    +5%

    This made gold one of the best investments of 2008.

    And the 2009 gold outlook looks just as strong.

    Gold’s 2009 Outlook

    Despite a bit of downside in the immediate future, we expect gold to have a stellar year.

    Global economic turmoil and deflation will undoubtedly continue to influence gold prices in the near-term. A short-term pullback in gold prices from current levels to $800—maybe even a bit lower—is not out of the question. However, we expect gold prices to break new records during 2009.

    For our current perspective, we expect gold prices to reach as high as $1,300 during 2009, which would be a profit of over 50% from current levels.

    Gold prices in 2009 will be supported more heavily by supply/demand fundamentals than in the previous years of this gold bull market.

    As we’ve previously discussed, during the third quarter of 2008, world gold demand outstripped supply by 10.5 million ounces. This deficit was worth $8.5 billion and was the largest supply/demand deficit since the gold bull market of the 1970s.

    Official 4Q 2008 world gold supply/demand figures will be calculated and reported later this month. Gold World will report them to you when the data is released.

    In the meantime, though, all estimates suggest that there will be another very large deficit in world gold supplies from the fourth-quarter, with investment demand continuing to drive the market.

    We expect that a continuing surge in investment demand could push gold prices as high as $1,300 at one point during 2009.

    There will likely be a bit more volatility in the gold market in 2009 as more and more speculators come into the market. It is likely that the gold market will experience three or four price peaks (selling points) during 2009.

    How to Invest in Gold for 2009

    As we expect a near-term drop in gold prices as a result of continuing deflation, we are advising our readers to hold off on any physical gold buying for the immediate future. As previously mentioned, gold prices could dip back down to $800 before recovering again.

    Nevertheless, we expect 2009 to be another great year for gold investors.

    Good Investing,

    Luke Burgess and the Gold World Research Team
    www.GoldWorld.com

    =================================================

    Gold World Special Report – Gold Backed Banking

    Special Report – Here’s How To Get Your Own Copy – Simply Subscribe

    January, 2009

    Gold Backed Banking

    It’s a wonder Americans aren’t rioting in the streets.

    Not including the $700 billion blank check issued to the banks and signed by the US taxpayer, the sum of liabilities assumed by the US government from the finance industry in the past 6 months alone exceeds 50% of the GDP.

    Despite this unprecedented government intervention, the solvency of other every commercial and investment bank is still at stake!

    Recognize this all-but-forgotten quote?

    “The central bank is an institution of the most deadly hostility existing against the Principles and form of our Constitution. I am an Enemy to all banks discounting bills or notes for anything but Coin. If the American People allow private banks to control the issuance of their currency, first by inflation and then by deflation, the banks and corporations that will grow up around them will deprive the People of all their Property until their Children will wake up homeless on the continent their Fathers conquered.”
    — Thomas Jefferson, Founding Father, Third President of the United States, and the principal author of the US Declaration of Independence

    How bout a drink from the cup of truth…

    The Bush administration’s $700 billion bailout plan may keep some banks afloat for the time being. But fundamental problems are still deeply rooted within the financial markets that threaten to bring down the whole system.

    The hard truth is that there is no 100% safe place to keep your money.

    Physical cash and gold are the safest places to hold your wealth right now. Anyone who tells you otherwise has either a motive or no clue.

    Those with the means to do so should be holding at least some physical cash and gold.

    Of course, people will debate why you should hold these assets…

    Gold is the ultimate in hedging against financial turmoil. But as it stands today, it’s quite rare to find someone willing to trade a product or service for gold. In other words, it’s difficult to spend gold like money, which has been a criticism of owning physical gold for decades.

    Today’s digital age allows consumers to move electronic fiat money around at speeds exponentially faster than ever before. This morning I paid my cable bill with my check card. The entire transaction was completed within 5 minutes. Had I paid by mailing a check, it could have taken up 1-2 days to reach the cable company and 3-5 days to clear my account.

    So what if there was a way gold could be used as easily as electronic money?

    The World’s Only “100% Backed-by-Gold Bank”

    You might have a hard time believing this, but you can actually put yourself on a personal gold standard with a new kind of currency, and it’s rapidly growing among gold bugs.

    Understand first, this new currency is not legal tender issued by any government. That means there’s no debt, inflation, geopolitical turmoil, or any other considerations normally associated with government-issued currency.

    The currency comes in electronic form, but can be used like any other currency in the world today to pay for goods and services, and even settle debt. But there’s one major difference that sets this currency apart from every other in the world:

    It’s 100% backed by gold.

    In fact, in most cases you can instantly exchange this currency for physical gold at any time… a feature taken away from the US dollar decades ago.

    This currency has a new system fully established, making it as easy to use as the current banking industry’s electronic money. Right now, in fact, there are already over 3,000 outfits—and climbing—in which you can pay online using this currency.

    How the “Gold Bank” Works

    Customers transfer funds from traditional bank accounts into these unique gold-backed bank accounts, and earn interest on their funds prior to placing an order.

    Meanwhile, for customers already holding gold and silver in secured (and insured) vaults, their metals are insured and held in specialized bullion vaults. Their metals assets go through an annual audit, and are fully reported to customers.

    Once customers’ funds are in the database, customers’ orders are made through its secure online system. Database servers record all transactions and store currency and metal balances.

    The Advantages of Using this Currency?

    Being backed by gold, the purchasing power of this currency fluctuates in relation to the price of gold.

    This means that as the price of gold increases, the purchasing power of the account increases. On the flip side, however, if the price of gold falls, so does the value of the account. Nonetheless, the risk of significant price fluctuation in gold is small compared to the risk of value fluctuations among fiat currencies, especially the US dollar.

    And despite a short-term correction, the price of gold has increased significantly over the past five years. So this factor has worked out to the advantage of anyone holding this currency over that period. And with +$2,000 gold on the horizon, holders of this currency should do quite well in the future.

    Now you should know that I’m in no way affiliated with this service, nor do I receive any compensation from it. That said…

    I Recently Put the Final Touches on my New Research Report…

    This report shares all the details about the new gold-backed electronic currency, and it’s yours free after you take a risk-free trial of the Mining Speculator service.

    It’s your chance to get in on the biggest and best buying opportunity in junior gold and silver stocks… ever.

    That’s right. The junior gold market is about to blast off, after a brutal beat-down sparked by the financial crisis. Truth is, it’s pushed many gold and silver stocks to new lows…

    … Which is why you don’t want to wait a minute longer to position yourself in the Mining Speculator’s mining and precious metals portfolio. Our team of analysts scour the earth for opportunities in gold, as protection against the financial uncertainties engulfing the U.S. and world markets.

    It’s the ultimate opportunity in a period of great crisis.

    You see, as our government continues to lose control of its ability to manage and prop up markets, gold and silver will undoubtedly make meteoric moves that will stun the populace.

    And just in case you still harbor doubts about gold, consider this… reported last week in the Financial Times…

    “… Investors in gold are demanding ‘unprecedented’ amounts of bullion bars and coins and moving them into their own vaults as fears about the health of the global financial system deepen.”

    And since gold bullion is getting harder and harder to come by, more investors are looking for the next best alternative, and that’s…

    Precious Metals Mining Stocks

    Bottom line: Junior mining stocks will begin to make major moves to the upside, rewarding those who got in early and held on… and those who get in now at what are, frankly, bargain share prices.

    You see, nothing can keep gold from doubling up and hitting $2,000 an ounce… causing shares in our mining exploration companies to skyrocket.

    I’m talking about junior mining stocks with the potential to double, triple—even quadruple!

    Of course, many people have trouble accepting gold as an investment—even now that they’ve witnessed a financial upheaval that’s shaken our country by the shoulders.

    But I also know that those who have heard me out-and followed through with my research and recommendations-have made extraordinary, life-altering returns.

    Which is why I maintain…

    There’s never been a better time-a more crucial time-to protect your portfolio with gold and precious metals.

    And for a brief time, we’re making it easy to do just that… for as little as $25.

    To get immediate inside access to the junior mining companies poised for major run-ups – the ones I’ve visited firsthand and carefully selected after exhaustive research and quality controls – simply take a trial of my Mining Speculator advisory.

    When you sign up for Mining Speculator, I will immediately send you the free report on the new gold-backed currency mentioned in this editorial.

    So, for only $25 you’ll begin to receive my Mining Speculator junior stock advisory… one that held an average 212% gain over five years… plus you’ll get our new special report on “The World’s Only 100% Backed-by-Gold Bank.”

    All you have to do is click here to get started.

    Good investing,

    Greg McCoach, Investment Director, Mining Speculator
    Luke Burgess, Editor, Gold World

    ====================================================

    My Note: I do not receive any renumeration or commissions for recommending either the Gold backed banking or the Mining Speculator. As Always be sure to do your own due diligence and read the prospectus before making any investments or deposits into financial institutions.-jschulmansr

    Share this:

    • Share on Reddit (Opens in new window) Reddit
    • Share on Facebook (Opens in new window) Facebook
    • Share on LinkedIn (Opens in new window) LinkedIn
    • More
    • Share on X (Opens in new window) X
    • Share on Pinterest (Opens in new window) Pinterest
    • Share on Tumblr (Opens in new window) Tumblr
    • Print (Opens in new window) Print
    • Email a link to a friend (Opens in new window) Email
    Like Loading...
    ← Older posts
    Newer posts →

    Authors

    • jschulmansr's avatar jschulmansr
      • Free Crypto!
      • Free Crypto Currency
      • This is Blessed!
      • Trump Rally Charleston
      • Trump Rally Charleston

    Blog at WordPress.com.

    Privacy & Cookies: This site uses cookies. By continuing to use this website, you agree to their use.
    To find out more, including how to control cookies, see here: Cookie Policy
    • Subscribe Subscribed
      Dare Something Worthy Today Too!

      Have a WordPress.com account? Log in now.

    • Dare Something Worthy Today Too!
      View site in Reader
      Manage subscriptionsSign upLog in
      Report this content
      Collapse this bar
    Loading Comments...
    %d